


Timbercreek Financial earnings date
Timbercreek Financial (58O) Q3 2026 Earnings Report
DE:58O Q3 2026 EPS Results
- Actual EPS
- -EUR 0.25
- Consensus EPS
- EUR 0.10
- Beat/Miss
- Missed by -EUR 0.34
- One Year Ago EPS
- EUR 0.06
DE:58O Q3 2026 Revenue Results
- Actual Revenue
- EUR 25.24M
- Expected Revenue
- EUR 16.20M
- Beat/Miss
- Beat by +EUR 9.03M
- YoY Revenue Growth
- +6.69%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 11/11/2026
- Time
- After Close
- Conference Call
- Wednesday, November 11, 2026
Timbercreek Financial's next earnings date is estimated for March 2, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q3 2026 Earnings Slide Deck
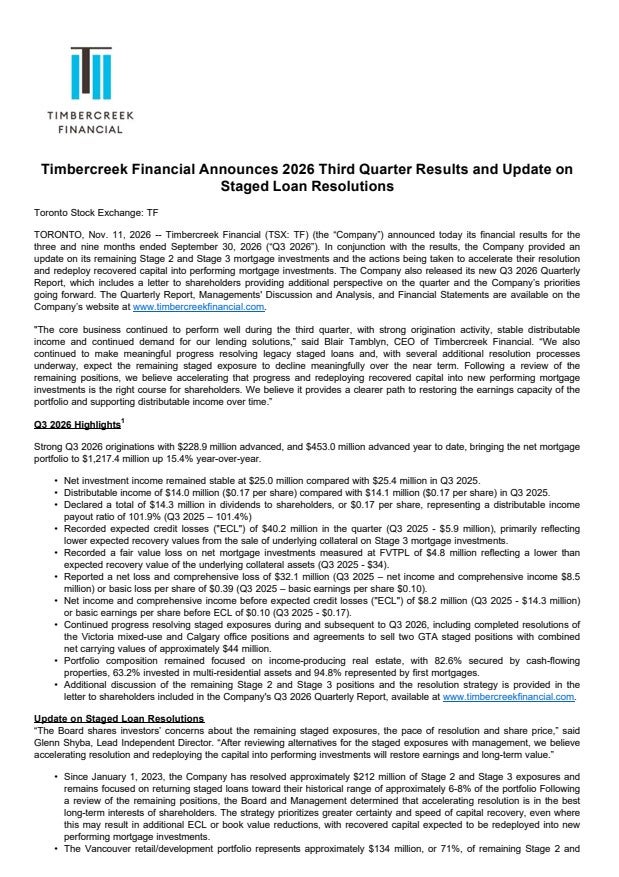
Q3 2026 Earnings Call Summary
The call presented a resilient and growing core lending business, with strong originations, syndication growth, conservative portfolio characteristics, and tangible progress on resolving legacy exposures. However, these positives were offset by a $32.1 million quarterly net loss, significant ECL charges, elevated staged loans, a temporarily expected 135% payout ratio, high credit facility utilization, and uncertainty around the timing and recovery of the Vancouver assets. Overall sentiment was mixed and cautious, with management focused on accelerating resolutions and redeploying capital.
Management expects the payout ratio to increase temporarily to approximately 135% in Q4 and remain elevated through the Vancouver sale process, currently expected to be completed by the end of Q1 2027, subject to market conditions and execution; following resolution and redeployment, dividend coverage is expected to improve and the payout ratio to trend back toward its historical average, with the 2027 plan showing an annual DI payout ratio back in the neighborhood of 100%. Stage 2 and Stage 3 loans are targeted to return to approximately 6% to 8% of the portfolio, with further progress expected in the near term and, taken holistically, material progress planned in 2027, the next 2, 3 quarters. Management said it expects LOIs for the Vancouver assets before the end of the year and a late Q1 closing would be the normal timeline, and expects the weighted average mortgage rate at the end of 2027 to be high 7s, versus 7.6% today or at quarter end, with potential upside to that number with interest rate increases.
- Strong Mortgage OriginationsTimbercreek advanced approximately $229 million during Q3. Through the first 9 months of 2026, net new mortgage originations reached $453 million, compared with approximately $258 million in the prior-year period.
- Stable Core Income and Distributable IncomeNet investment income was $25 million in Q3, compared with $25.4 million in the prior-year period. Distributable income was $14 million, or $0.17 per share, compared with $14.1 million, or $0.17 per share, in Q3 of last year.
- Conservative and Diversified Core PortfolioAt quarter end, 82.6% of the portfolio was invested in cash-flowing properties, 63% was invested in multi-residential assets, and 94.8% of investments were first mortgages. Weighted average loan-to-value remained conservative at 69.8%, and the portfolio remained diversified across property types in Canada's major urban markets.
- Progress on Legacy Loan ResolutionsSince the beginning of 2023, Timbercreek has resolved more than $212 million of Stage 2 and Stage 3 exposures. During Q3 and after quarter end, it completed the resolution of the Victoria mixed-use position and the Calgary office position.
- Additional Staged Loan Sales UnderwayLetters of intent are in place to sell two GTA staged positions in the coming months, with a combined net carrying value of approximately $44 million. Additional smaller resolution initiatives are also advancing.
- Active Lending Environment and Portfolio GrowthThe lending environment remained active through Q3, with healthy demand across target markets. Timbercreek advanced approximately $229 million, including 12 new mortgage investments, while portfolio repayments totaled approximately $151 million. The net mortgage portfolio increased to approximately $1.22 billion at quarter end.
- Syndication Growth Supports Capacity and FeesThrough the first 9 months of 2026, syndications increased to $885 million from approximately $628 million in the prior-year period. Management said syndications support balance sheet capacity, contribute to fee generation, and provide institutional third-party validation of originated volume.
- Attractive Redeployment OpportunitiesManagement said borrower activity and the strength of the pipeline provide attractive opportunities to redeploy capital recovered from staged loan resolutions into new performing investments at current market returns. Multi-residential activity remains significant, with continued discipline on leverage structure and sponsor quality.
- Strong Cash-Generating Base for the DividendManagement stated that the substantial majority of the portfolio continues to perform and generate cash income, providing a strong foundation for the monthly dividend.
- Balance Sheet Growth and Active Capacity ManagementNet mortgage investments totaled approximately $1.22 billion at September 30, up approximately 15% year-over-year, reflecting strong deployment activity through the first 9 months of the year. Management continues to manage balance sheet capacity through portfolio repayments and syndication activity.
- No Current Covenant BreachesManagement stated that there were no covenant breaches during the quarter. Forward-looking covenant relief was negotiated to provide enough headroom to work through the Vancouver portfolio on an interim basis.
- Attractive Current Lending ValuationsManagement said that, following the interest-rate reset, valuations are attractive for lenders because fresh capital is being deployed at lower values than before. The company also reported seeing continued green shoots in most of its participating markets.
- Plan to Return Stage Loans Toward Historical LevelsManagement's objective is to return Stage 2 and Stage 3 loans to the historical range of approximately 6% to 8% of the portfolio. The company said it intends to accelerate resolutions, recover capital, and redeploy it into performing mortgage investments.
- Expected Improvement in Dividend Coverage After ResolutionManagement expects dividend coverage to improve and the payout ratio to trend back toward its historical average as Vancouver assets are resolved and recovered capital begins contributing to earnings.
DE:58O Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Mar 02, 2027 | 2026 (Q4) | 0.06- | -0.01 | ― | ― |
| Nov 11, 2026 | 2026 (Q3) | 0.10-0.25 | 0.06 | -490.00% (-0.31) | |
| Jul 29, 2026 | 2026 (Q2) | 0.110.06 | 0.1 | -40.00% (-0.04) | |
| May 05, 2026 | 2026 (Q1) | 0.110.08 | 0.11 | -27.78% (-0.03) | |
| Feb 25, 2026 | 2025 (Q4) | 0.11-0.01 | 0.02 | -133.33% (-0.03) | |
| Oct 29, 2025 | 2025 (Q3) | 0.110.06 | 0.11 | -41.18% (-0.04) | |
| Jul 30, 2025 | 2025 (Q2) | 0.110.10 | 0.12 | -21.05% (-0.03) | |
| May 05, 2025 | 2025 (Q1) | 0.100.11 | 0.11 | 5.88% (+0.01) | |
| Feb 26, 2025 | 2024 (Q4) | 0.100.02 | 0.11 | -83.33% (-0.10) | |
| Oct 30, 2024 | 2024 (Q3) | 0.110.11 | 0.13 | -15.00% (-0.02) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
