

PayPal Holdings (PYPL) Q3 2026 Earnings Report
MX:PYPL Q3 2026 EPS Results
- Actual EPS
- MXN 27.25
- Consensus EPS
- MXN 24.62
- Beat/Miss
- Beat by +MXN 2.63
- One Year Ago EPS
- MXN 25.18
MX:PYPL Q3 2026 Revenue Results
- Actual Revenue
- MXN 160.88B
- Expected Revenue
- MXN 163.77B
- Beat/Miss
- Missed by -MXN 2.89B
- YoY Revenue Growth
- +1.11%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 10/27/2026
- Time
- Before Open
- Conference Call
- Tuesday, October 27, 2026
PayPal Holdings's next earnings date is estimated for February 9, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
Q3 2026 Earnings Slide Deck
Q3 2026 Earnings Call Summary
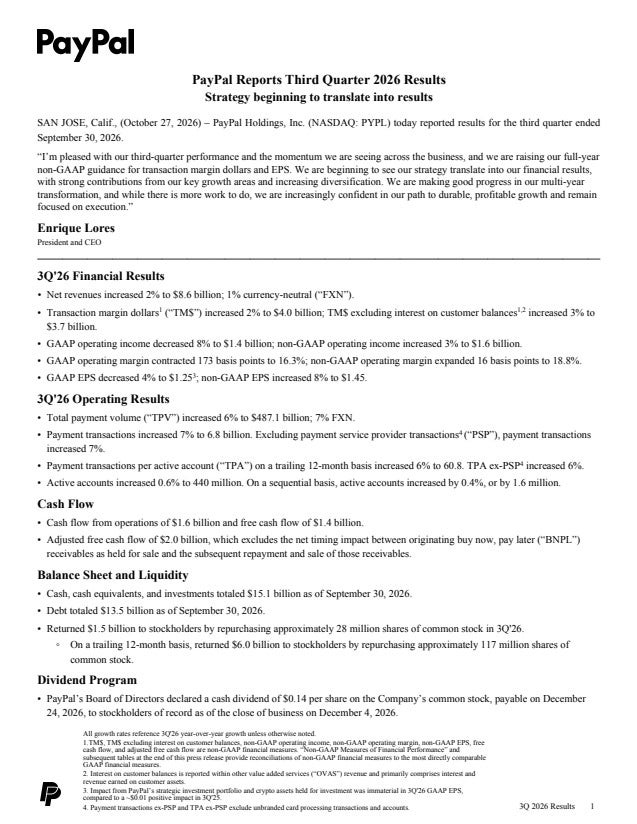
The call was broadly positive. PayPal reported better-than-expected transaction margin dollars, 8% non-GAAP EPS growth, strong cash generation, raised full-year guidance, progress in cost savings and technology modernization, and double-digit momentum in financial services, Venmo, and parts of PSP. The main challenges were low branded checkout growth, persistent EU de minimis pressure, a 4% decline in international revenue on a currency-neutral basis, and the fact that the transformation and merchant playbook remain early with execution still ahead.
For full-year 2026, PayPal raised guidance to approximately $15.7 billion in transaction margin dollars, or $14.6 billion excluding interest on customer balances, mid-single-digit growth in non-transaction operating expenses, and approximately $5.60 in non-GAAP EPS, with at least $6.5 billion of adjusted free cash flow and approximately $6 billion in share repurchases; online branded checkout is expected to deliver low-single-digit TPV growth on a currency neutral basis, with similar 1%-2% online branded growth throughout the fourth quarter. For the fourth quarter, PayPal expects low-double-digit revenue growth on a currency neutral basis, slightly positive growth in transaction margin dollars, TM dollars excluding interest on customer balance to be slightly positive, flat to low-single-digit growth in non-transaction operating expenses, and approximately $1.43 in non-GAAP EPS. PayPal remains on track for at least $1.5 billion in gross run-rate cost savings over the next two to three years, with a run-rate of more than $700 million exiting the fourth quarter; over time, it expects sustainable total company transaction margin dollar growth in the mid-single-digit range and solid double-digit EPS growth, while targeting 2027 non-GAAP EPS growth similar to this year and planning further transaction margin dollar and operating expense investment.
- Solid Third-Quarter Financial PerformanceTransaction margin dollars grew approximately 2%, or 3% excluding interest on customer balances, while non-GAAP EPS grew 8% to $1.45 and exceeded guidance. Revenue grew 2% on a spot basis and 1% currency neutral.
- Strong Cash Generation and Shareholder ReturnsAdjusted free cash flow was $2 billion in the quarter. PayPal returned more than $1.6 billion through buybacks and dividends, including $1.5 billion of share repurchases, bringing trailing 12-month repurchases to $6 billion.
- Full-Year Guidance RaisedPayPal raised full-year 2026 guidance to approximately $15.7 billion of transaction margin dollars, or $14.6 billion excluding interest on customer balances; approximately $5.60 of non-GAAP EPS; at least $6.5 billion of adjusted free cash flow; and approximately $6 billion in share repurchases.
- Financial Services Becoming a Larger Growth EngineFinancial services, including buy now, pay later, credit, debit, and merchant lending, represented more than 20% of transaction margin dollars in 2026 and grew double-digits. PayPal said these products provide attractive economics, expand its total addressable market, and increase consumer ARPA by between 2x and 5x versus consumers not using financial services.
- Strong Pay Later MomentumPay Later distribution broadened through merchants including Amazon in Germany and Austria, American Eagle, Aerie, and Dick's Sporting Goods. Pay Later TPV grew 25% and was described as outpacing the market.
- Venmo Sustains Double-Digit GrowthVenmo TPV sustained double-digit growth for the eighth consecutive quarter. Pay with Venmo TPV grew 43% in the quarter, while management also described growth of more than 40% for Pay with Venmo. Venmo ARPA grew double-digits, driven by adoption of monetized products.
- Venmo Debit Card Expansion and EngagementThe Venmo debit card reached 6.7 million monthly active accounts, up more than 55%, with a record 1.6 million first-time users in the third quarter. Management also reported more than 60% year-over-year debit-card growth, and monthly active accounts using both the debit card and Pay with Venmo nearly doubled year-over-year.
- Venmo Product ExpansionPayPal relaunched the Venmo credit card with rewards for splitting purchases with friends, launched P2P transfers by scanning and splitting receipts, and expanded Pay with Venmo usage into areas including travel, college tuition, and prediction markets. Management said only 23% of Venmo customers currently use its financial services and identified a 4x to 5x opportunity to increase ARPA.
- PSP and Braintree GrowthPSP volume grew 8%, while Braintree TPV grew 10%, supported by profitable front-book wins, high retention, and expansion with existing merchants. PayPal is expanding value-added services such as risk as a service, payouts, invoicing, and merchant lending.
- Higher Value-Added Services AttachmentValue-added services attachment in PSP increased to 6% from 5% a year ago. PayPal is investing in specialized sales teams focused on increasing attachment and monetization.
- Branded Checkout Stabilization and U.S. ProgressBranded checkout TPV growth remained relatively stable in the 1%-2% range for four quarters, with continued improvement in the U.S. for the third consecutive quarter and stabilization in Germany. PayPal reported improved relative share of checkout among merchant cohorts where its full experience, presentment, selection, and marketing playbook had been implemented.
- Merchant Playbook Showing TractionPayPal cited more than 40% growth over the last six months with a leading U.S. sports entertainment platform, more than 50% Venmo growth with that partner, and an increase in BNPL growth from 7% to 20% at a leading U.S. omnichannel retailer after expanding the Pay Later offering.
- Operating Efficiency and Cost SavingsPayPal reduced headcount by more than 2,000, removed three organizational layers across most areas, reduced management roles by more than a quarter, and kept non-transaction operating expense growth to 1%. The company remains on track to achieve at least $1.5 billion in gross run-rate cost savings over two to three years, including more than $700 million exiting the fourth quarter.
- AI and Automation Productivity GainsAI chat agents now support customer service across 190 countries and six languages and have resolved more than 24 million contacts year-to-date.
- Technology Modernization ProgressPayPal migrated 7.5 billion customer records to cloud infrastructure, completed the global rollout of its new mobile app on modern architecture, and began processing select Venmo payments on PayPal rails. Venmo authentication now runs entirely on PayPal's identity platform.
- Faster Credit Decisions Through AIPayPal's modular risk platform, using real-time data and AI, cut credit decision times nearly in half in Canada, Italy, and Spain.
- Agentic Commerce OpportunityPayPal is collaborating with Meta and other AI companies to integrate PayPal into AI personal agents and agentic commerce. Management emphasized PayPal's trust, security, transaction history, and consumer and merchant protections as key elements of its value proposition.
- Lower Transaction and Credit Loss RatesThe transaction expense rate declined, largely due to mix and partner incentives. Transaction loss also declined as a result of work on onboarding, fraud prevention, and risk management, while credit loss declined due to a reserve release related to expected credit externalization and disciplined underwriting.
- Long-Term Growth FrameworkManagement believes the strategy can drive sustainable total-company transaction margin dollar growth in the mid-single-digit range, supported by operating leverage and disciplined capital allocation, enabling solid double-digit EPS growth over time. PayPal is targeting 2027 non-GAAP EPS growth similar to this year while investing for faster, more durable growth.
- Balanced Credit Funding FlexibilityPayPal plans to continue using a balanced approach between on-balance-sheet and off-balance-sheet credit growth. Management cited flexibility across European Buy Now Pay Later, a U.S. revolving credit partnership, and the U.S. Pay in 4 funding program.
- Disciplined M&A FrameworkManagement said M&A may support growth in financial services, Venmo, or processing, but any transaction must meet strategic, financial-return, and operational-integration criteria. Share buybacks and dividends remain the primary capital-return priorities.
MX:PYPL Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Feb 09, 2027 | 2026 (Q4) | 26.76- | 23.11 | ― | ― |
| Oct 27, 2026 | 2026 (Q3) | 24.6227.25 | 25.18 | 8.21% (+2.07) | |
| Jul 28, 2026 | 2026 (Q2) | 24.0225.93 | 26.31 | -1.43% (-0.38) | |
| May 05, 2026 | 2026 (Q1) | 23.8825.18 | 24.99 | 0.75% (+0.19) | |
| Feb 03, 2026 | 2025 (Q4) | 24.1923.11 | 22.36 | 3.36% (+0.75) | |
| Oct 28, 2025 | 2025 (Q3) | 22.5925.18 | 22.55 | 11.67% (+2.63) | |
| Jul 29, 2025 | 2025 (Q2) | 24.3726.31 | 22.36 | 17.65% (+3.95) | |
| Apr 29, 2025 | 2025 (Q1) | 21.8224.99 | 20.3 | 23.15% (+4.70) | |
| Feb 04, 2025 | 2024 (Q4) | 21.1022.36 | 27.81 | -19.59% (-5.45) | |
| Oct 29, 2024 | 2024 (Q3) | 20.1822.55 | 24.43 | -7.69% (-1.88) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
