


Definity Financial Corp. earnings date
Definity Financial Corp. (DFYFF) Q3 2026 Earnings Report
DFYFF Q3 2026 EPS Results
- Actual EPS
- $0.25
- Consensus EPS
- $0.20
- Beat/Miss
- Beat by +$0.06
- One Year Ago EPS
- $0.72
DFYFF Q3 2026 Revenue Results
- Actual Revenue
- $1.25B
- Expected Revenue
- $1.03B
- Beat/Miss
- Beat by +$229.06M
- YoY Revenue Growth
- +28.21%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 11/05/2026
- Time
- After Close
- Conference Call
- Thursday, November 5, 2026
Definity Financial Corp.'s next earnings date is estimated for February 11, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q3 2026 Earnings Slide Deck
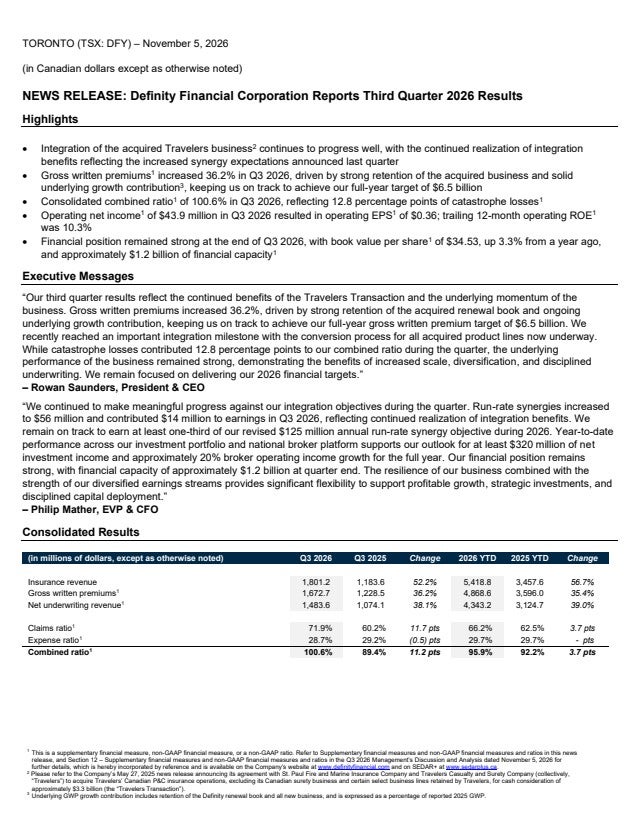
Q3 2026 Earnings Call Summary
The call was strongly positive overall. Management reported substantial premium growth, successful Travelers integration, accelerated synergy realization, resilient book value, higher investment income, strong broker momentum, measurable AI benefits, and substantial financial capacity. The primary challenges were elevated catastrophe losses, higher combined ratios, competitive pressure in large commercial accounts, and the expected near-term reduction in Alberta auto premiums, but management described these issues as understood, actively managed, or temporary.
Management maintained full-year 2026 gross written premium guidance of $6.5 billion and full-year net investment income guidance of at least $320 million, expects the national broker platform to achieve approximately 20% growth, and remains confident in realizing at least 1/3 of the $125 million synergy target by the end of 2026; integration costs remain estimated at $150 million to $170 million, with approximately 1/3 of those costs for 2027, and business conversions and exits of the remaining transition service agreements are expected by late 2027. Commercial industry growth is expected to be in the low single digits over the next 12 months, with mid- to high single-digit pricing in SME, low to mid-single digits in middle market, mid- to high single-digit growth in specialty, and 2x outperformance of the industry in terms of growth; Alberta average premiums are expected to decline in the mid-teens range on January 1, 2027, and management remains confident in its midterm objective of sustainable mid-teens operating ROE, with the Travelers transaction expected to deliver a more than 200 basis point improvement in operating ROE.
- Strong Premium Growth and Full-Year GuidanceThird-quarter gross written premiums increased 36.2% year over year to $1.7 billion, bringing year-to-date premiums to $4.9 billion and keeping the company on track to achieve its full-year guidance of $6.5 billion. Growth included a 25.7% contribution from the acquired renewal book and 10.5% underlying growth.
- Travelers Integration Progressing Ahead of PlanMore than 1/3 of the acquired portfolio has been converted to Definity platforms, all product lines are now in the conversion process, and all new claims from converted policies are being managed in Definity's system. The company has retained all more than 100 new brokers acquired through the transaction, is converting between 30,000 and 40,000 policies, and remains on track to complete conversions and exit remaining transition service agreements by late 2027.
- Strong Integration Retention and ExecutionCustomer retention for the acquired business is tracking strongly and converging with Definity's underlying levels. Approximately 1,000 employees are actively involved in the integration, the company has executed against 2,500 major integration milestones, onboarded approximately 400,000 individual clients, migrated and rationalized more than 1,000 external supplier agreements, and secured required regulatory approvals across all provinces.
- Accelerated Synergy CaptureNine months after closing, Definity had achieved $56 million of run-rate synergy savings, representing almost 45% of the increased $125 million target. Year-to-date results included $31 million of earned synergies, and management remained confident it could realize at least 1/3 of the synergy target by the end of 2026.
- Resilient Earnings and Book Value GrowthOperating EPS was $0.36 for the quarter, while book value per share increased 3.3% year over year to $34.53. The company said underlying results remained strong and nearly flat year over year despite the addition of the acquired business and elevated catastrophe losses.
- Personal Auto Growth and Favorable Pricing EnvironmentPersonal auto gross written premiums grew 38.1% to $714 million, including 23.3% growth from retention of the acquired renewal book and 14.8% underlying growth. Approximately half of the underlying growth was unit-count growth, with growth occurring across nearly every jurisdiction. Management described Ontario's pricing environment as favorable, with rate adequacy supporting margin protection and continued unit growth.
- Personal Property and Commercial Top-Line ExpansionPersonal property gross written premiums increased 35.3% to $486 million, including 10.6% underlying growth. Commercial Insurance premiums increased 34.2% to $472 million, supported by pricing and volume increases in small business and specialty lines.
- Commercial Specialty and SME MomentumIn commercial insurance, SME pricing was in the mid- to high-single digits with strong retention, while middle-market pricing was in the low- to mid-single digits with retention broadly in line with historical levels. Specialty insurance, which represents about 1/3 of the portfolio, was achieving mid- to high-single-digit growth. Management expects its portfolio construction and capabilities to support growth at 2x the industry rate.
- Higher Investment Income and Outlook MaintainedThird-quarter net investment income increased 46.6% year over year to $79.3 million, driven by interest income from the larger post-acquisition portfolio and trading into higher prevailing yields. Management maintained its full-year outlook of at least $320 million and expected fourth-quarter investment income to increase sequentially.
- Broker Platform Continues to GrowThe national broker platform, ranked among the top 10 brokers in Canada, generated $29.3 million of total broker operating income, including $18.7 million of distribution income and $10.6 million of intercompany commission income. Total broker operating income increased 10.2% year over year and 17.6% year to date, keeping the platform on track for approximately 20% full-year growth. Since the platform was established, premium acquired CAGR has been about 30%, distribution revenue CAGR about 25%, and operating income CAGR about 30%.
- Strong Capital PositionDespite absorbing nearly $400 million of combined pretax catastrophe losses and unrealized bond devaluations during the quarter, Definity maintained nearly $1.2 billion of total financial capacity. Management said this provided capacity to fund organic and inorganic growth, support the broker network, and pursue capital deployment priorities.
- AI Capabilities Delivering Measurable BenefitsDefinity has more than 250 AI and data practitioners and more than 140 active models and solutions. Its first fully agentic AI solution for broker first notice of loss produced an early 50% reduction in claims administration effort for broker-submitted claims. AI is also being used in underwriting submission intake, fraud detection, appraisals, contact centers, coding, and system replatforming.
- Long-Term ROE Expansion OpportunityManagement said the Travelers transaction is expected to deliver more than a 200-basis-point improvement in operating ROE on top of organic plans. The company remained confident in its progress toward a sustainable mid-teens operating ROE as synergies continue to flow through over the next two years.
- Disciplined Market Positioning and Growth StrategyManagement characterized overall market conditions as favorable. Personal auto and personal property conditions were expected to remain firm, while Definity continued to focus commercial growth on SME and specialty niches where pricing conditions remain positive. The company also said its expense management, underwriting discipline, broker relationships, and portfolio shaping were supporting profitable growth.
DFYFF Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Feb 11, 2027 | 2026 (Q4) | 0.83- | 0.69 | ― | ― |
| Nov 05, 2026 | 2026 (Q3) | 0.200.25 | 0.72 | -65.05% (-0.47) | |
| Jul 30, 2026 | 2026 (Q2) | 0.650.68 | 0.59 | 15.48% (+0.09) | |
| May 07, 2026 | 2026 (Q1) | 0.610.68 | 0.46 | 49.23% (+0.22) | |
| Feb 12, 2026 | 2025 (Q4) | 0.660.69 | 0.67 | 4.21% (+0.03) | |
| Nov 06, 2025 | 2025 (Q3) | 0.550.72 | 0.09 | 692.31% (+0.63) | |
| Jul 31, 2025 | 2025 (Q2) | 0.540.59 | 0.66 | -10.64% (-0.07) | |
| May 08, 2025 | 2025 (Q1) | 0.480.46 | 0.46 | 0.00% (+0.00) | |
| Feb 13, 2025 | 2024 (Q4) | 0.630.67 | 0.6 | 10.47% (+0.06) | |
| Nov 07, 2024 | 2024 (Q3) | 0.030.09 | 0.11 | -13.33% (-0.01) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
