


Leon's Furniture earnings date
Leon's Furniture (74W) Q3 2026 Earnings Report
DE:74W Q3 2026 EPS Results
- Actual EPS
- EUR 0.38
- Consensus EPS
- EUR 0.38
- Beat/Miss
- Beat by +EUR 0.01
- One Year Ago EPS
- EUR 0.41
DE:74W Q3 2026 Revenue Results
- Actual Revenue
- EUR 424.55M
- Expected Revenue
- EUR 423.61M
- Beat/Miss
- Beat by +EUR 943.38K
- YoY Revenue Growth
- -0.86%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 11/05/2026
- Time
- After Close
- Conference Call
- Thursday, November 5, 2026
Leon's Furniture's next earnings date is estimated for February 24, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q3 2026 Earnings Slide Deck
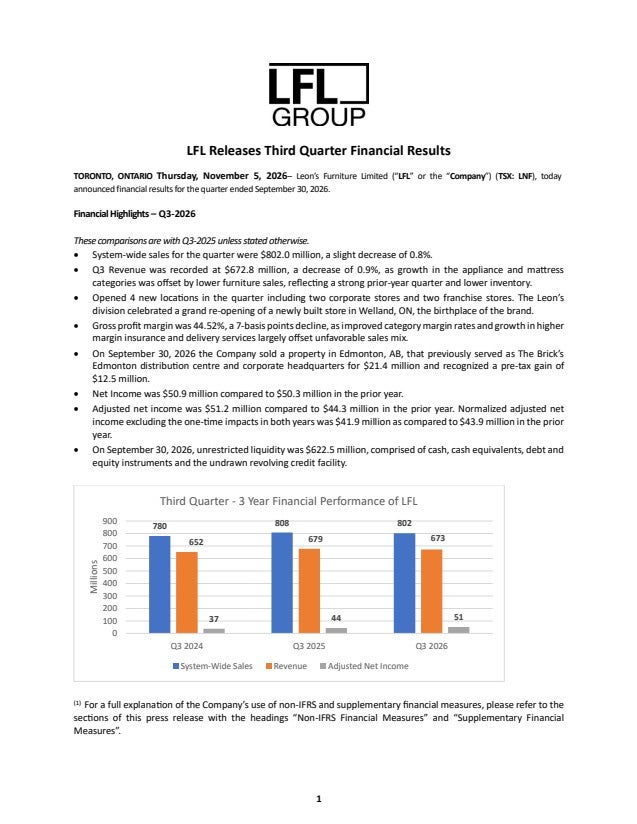
Q3 2026 Earnings Call Summary
The call conveyed a cautiously positive outlook. The company faced declining revenue, weaker same-store sales, cautious consumers, furniture-related inventory constraints, and lower normalized earnings, but management emphasized disciplined execution, stable gross margins, growth in appliances, mattresses, and commercial sales, strong liquidity, continued investment, and improving inventory availability heading into the fourth quarter.
For the fourth quarter, LFL expects to open 2 new franchise stores, with comparisons easing, inventory in a better position than at the end of the third quarter, and inventory delay impact “not going to be as meaningful as Q3,” although some inventory expected in the back half of Q4 may be pushed to Q1; shipping delays in certain lanes are continuing, the objective is to “hold the rate close to last year,” and fuel remains the main pressure in delivery expense. Management plans to attack Black Friday “aggressively,” with November the “biggest month” and “the make or break it for the quarter,” while commercial opportunities from a competitor exit are expected over the next 12 to 18 months; more 2027 plans will be provided on the February call, the centralized-distribution test will resume in 2027, and the REIT initiative remains guided by market conditions and regulatory approvals.
- Appliances Returned to GrowthAppliance sales increased in both the retail and commercial channels. Management attributed the retail improvement to a tighter assortment, deeper inventory on best sellers, enhanced store presentation, and clearer marketing around delivery, haul away, and installation.
- Mattress Category Delivered a Third Consecutive Quarter of GrowthMattress sales grew for the third consecutive quarter. The company launched a new Brick mattress in partnership with Skechers, expanded its premium-brand assortment, and increased marketing activity to pursue further sales and market share.
- Commercial Sales Increased and Share Opportunities EmergedCommercial channel sales grew. Management said the growth represented share gains, including business that became available after a large competitor exited the market, with additional opportunities expected over the next 12 to 18 months. Appliance Canada's move into the Leon's store in Richmond, British Columbia also helped the business.
- Digital Engagement and E-Commerce ImprovedOnline sessions grew strongly and e-commerce sales increased. Management described the digital platform as a research and qualification engine that brings customers into stores with clear purchase intent.
- Gross Margin Held Essentially FlatGross profit margin was 44.52%, essentially flat year-over-year. Improved margin rates in furniture, appliances, and electronics, together with increased revenue from higher-margin insurance and delivery services, largely offset the unfavorable category mix. Through nine months, margin remained within a few basis points of the prior year.
- Cost Discipline ContinuedAlthough SG&A as a percentage of revenue increased 25 basis points to 35.76%, expenses were slightly down in dollar terms year-over-year, reflecting the cost discipline maintained during the quarter.
- Reported Adjusted Earnings and EPS IncreasedIncluding a $12.5 million gain from the sale of the former Brick head office and distribution center, adjusted net income was $51.2 million and adjusted diluted EPS was $0.74, compared with $0.65 last year.
- Strong Liquidity PositionThe company ended the quarter with $622.5 million in unrestricted liquidity, including cash, marketable securities, and its undrawn revolver. Management said this liquidity provides flexibility to invest, navigate volatility, and act opportunistically.
- Store Network Continued to ExpandLFL opened eight stores during the year for a net increase of four. During the quarter, it opened four locations, celebrated the reopening of a newly built Leon's store in Welland, and reached 304 stores. Two additional franchise stores are expected to open in the fourth quarter.
- Capital Allocation Included Distribution-Center Ownership and Share RepurchasesThe company completed the purchase of the remaining 50% of its current Edmonton distribution center and continued its normal capital-allocation priorities of reinvestment, maintaining a strong balance sheet, and returning capital to shareholders. It repurchased approximately 120,000 shares for approximately $2.9 million during the fourth quarter.
- Financing Penetration and Average Unit Price ImprovedAverage unit price was higher in the quarter, supported in part by sales execution and financing programs. Financing penetration improved from the second quarter and helped increase average basket size in a value-conscious environment.
- Inventory Position Improved Entering the Fourth QuarterManagement said inventory was in a better position at the end of the third quarter and that much of the inventory expected at the end of the third quarter arrived in October. The company expects the inventory-delay impact to be less meaningful in the fourth quarter than in the third quarter.
- Continued Investment and Strategic InitiativesManagement said it continues to invest through the cycle, including measured store expansion, ownership of the Edmonton distribution center, work on centralized distribution capacity, and the REIT initiative. The centralized-distribution test remains a key priority for 2027, while the REIT timing remains guided by market conditions and regulatory approvals.
DE:74W Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Feb 24, 2027 | 2026 (Q4) | 0.46- | 0.47 | ― | ― |
| Nov 05, 2026 | 2026 (Q3) | 0.380.38 | 0.41 | -6.46% (-0.03) | |
| Aug 06, 2026 | 2026 (Q2) | 0.330.32 | 0.29 | 10.87% (+0.03) | |
| May 07, 2026 | 2026 (Q1) | 0.180.18 | 0.22 | -17.14% (-0.04) | |
| Feb 25, 2026 | 2025 (Q4) | 0.480.47 | 0.62 | -25.25% (-0.16) | |
| Nov 06, 2025 | 2025 (Q3) | 0.390.41 | 0.34 | 20.37% (+0.07) | |
| Aug 07, 2025 | 2025 (Q2) | 0.290.29 | 0.28 | 4.55% (+0.01) | |
| May 08, 2025 | 2025 (Q1) | 0.140.22 | 0.15 | 45.83% (+0.07) | |
| Feb 25, 2025 | 2024 (Q4) | 0.450.62 | 0.45 | 37.50% (+0.17) | |
| Nov 07, 2024 | 2024 (Q3) | 0.350.34 | 0.47 | -28.00% (-0.13) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
