


Intermap Technology earnings date
Want to see TSE:IMP full AI Analyst Report?
Intermap Technology (IMP) Q3 2026 Earnings Report
TSE:IMP Q3 2026 EPS Results
- Actual EPS
- -CAD 0.07
- Consensus EPS
- ―
- Beat/Miss
- ―
- One Year Ago EPS
- -CAD 0.03
TSE:IMP Q3 2026 Revenue Results
- Actual Revenue
- CAD 2.52M
- Expected Revenue
- ―
- Beat/Miss
- ―
- YoY Revenue Growth
- +6.75%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 11/16/2026
- Time
- After Close
- Conference Call
- Monday, November 16, 2026
Intermap Technology's next earnings date is estimated for April 1, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q3 2026 Earnings Slide Deck
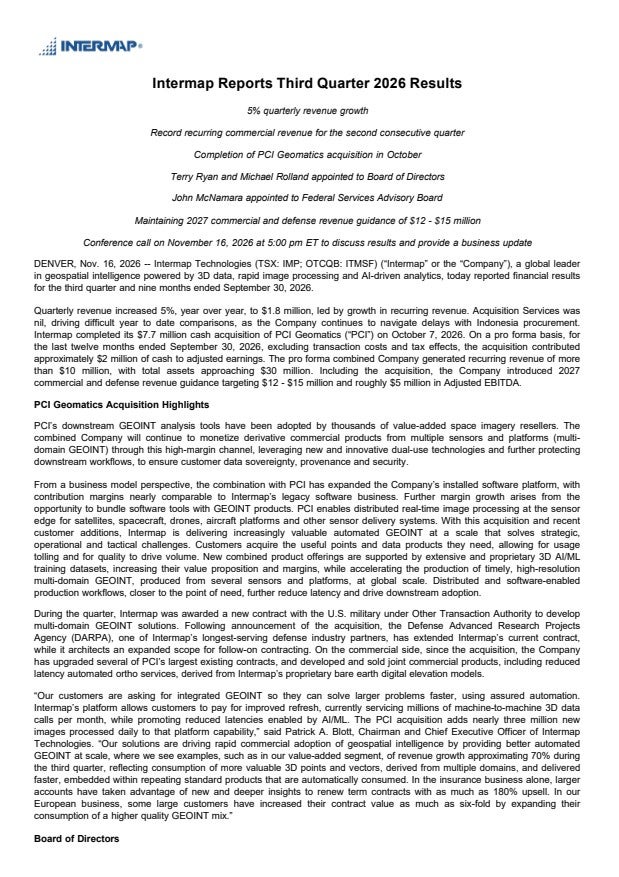
Q3 2026 Earnings Call Summary
The call was broadly constructive, supported by record commercial recurring revenue, 5% total revenue growth, 12% third-quarter growth excluding Indonesia-related Acquisition Services, completion of the PCI acquisition, new defense contracts, strong insurance upsells and maintained 2027 guidance. These positives were offset by a substantially larger net loss, higher cash usage and operating expenses, continued Indonesia procurement delays, zero Acquisition Services revenue and constraints from the U.S. continuing resolution. Highlights outweighed the lowlights, although execution remains dependent on Indonesia and government contracting timelines.
Intermap is maintaining its 2027 commercial and defense revenue guidance, targeting $12 million to $15 million of revenue with roughly $5 million in adjusted EBITDA, driven by AI-powered insurance analytics, telecommunications and critical infrastructure vertical markets and defense and intelligence requirements; the guidance excludes pending government mapping procurements in 2026 and 2027, including Indonesia until formal contract awards occur. Management also said it budgets approximately $1 million of investment per quarter to pursue Indonesia and has a medium-term objective of a 70% government, maybe a little more, and 30% commercial mix.
- Record Commercial Recurring RevenueIntermap achieved the highest commercial recurring revenue in its history for the second consecutive quarter. Total revenue increased 5% to $1.8 million, Value-added Data was a clear area of growth, revenue excluding Acquisition Services increased 12% in Q3, and revenue for the first nine months increased 2% compared with the same period in 2025.
- PCI Geomatics Acquisition CompletedIntermap completed its acquisition of PCI Geomatics on October 7 for $7.7 million in cash. Pro forma revenue for the combined company for the first nine months exceeded $10 million, mostly recurring; pro forma total assets approximated $30 million, pro forma total debt was $1.9 million, and PCI contributed approximately $2 million of cash to adjusted earnings excluding transaction costs, accounting and tax effects.
- 2027 Revenue and EBITDA Guidance MaintainedIntermap maintained its 2027 commercial and defense revenue guidance of $12 million to $15 million with roughly $5 million in adjusted EBITDA. The guidance is driven by AI-powered insurance analytics, telecommunications, critical infrastructure vertical markets, and defense and intelligence requirements.
- Expansion of Defense Contract PortfolioThe company added a new U.S. SOCOM other transaction authority contract focused on multi-domain geospatial intelligence products. Intermap was also placed on a new U.S. Military contract under other transaction authority, while DARPA extended Intermap's current contract and is architecting an expanded scope for follow-on contracting expected in Q1 next year.
- Expanded Multi-Domain GEOINT CapabilitiesPCI adds satellite and aerial image processing, orthorectification and analytics capabilities to Intermap's risk management solutions. PCI processes north of 3 million images per day, while Intermap's platform services millions of machine-to-machine 3D calls per month. Management stated that the combined companies have substantial capacity for multi-domain GEOINT across satellite, airborne and drone platforms.
- Strong Insurance Customer UpsellsIntermap said some large insurance accounts are digging deeper into the data and renewing term contracts with upsells of as much as 180%, supported by an improved mix of GEOINT products.
- Positive PCI Integration and Customer DemandManagement said the PCI transaction is working out very favorably and that both companies are excited about the combination. The transaction was driven by customers asking for multi-domain GEOINT, distributed processing and on-premise data sovereignty capabilities.
- Commercial Go-to-Market InvestmentIntermap has hired sales representatives and marketing professionals focused on the space vertical to build out the front end of the PCI-related business and support bundled and multi-domain products.
- Indonesia Procurement Process AdvancementIndonesia upgraded oversight of its ILAS program and placed the procurement under the jurisdiction of the Attorney General. Management described this as an important step forward and said Intermap has the past performance, technology, capability and expertise to help complete the program on time and within budget.
- No Outstanding Indonesia Deliverable IssuesIn response to a question about the Sulawesi audit and formal acceptance of deliverables, management stated that there were no outstanding quality issues or financial disputes.
- U.S. Government Demand Pull Through OTAsManagement said the U.S. government has become a demand pull and is supporting product development with new contracts. Core customers with urgent requirements are using other transaction authorities to continue work and help evolve Intermap's product roadmap.
- Expansion Opportunities Across Government and Commercial MarketsIntermap said it is interested in carefully selected complementary or bolt-on acquisitions in insurance, telecommunications, critical infrastructure and government markets. The company is also adding new jurisdictions, especially in Southeast Asia and South America.
- Strategic Revenue Mix ObjectiveManagement described a medium-term objective of managing toward an approximately 70% government and 30% commercial revenue mix, while noting that commercial total addressable markets are growing at a much faster rate.
- Improved Dilutive Securities PositionThe number of dilutive securities declined from 2,429,000 at year-end to 1,338,000 at September 30.
- Cash and Working Capital Position Before PCI ClosingIntermap ended September with $12 million in cash, $8.4 million in working capital and $13.9 million in shareholders' equity. These balances were before the October PCI acquisition.
TSE:IMP Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Apr 01, 2027 | 2026 (Q4) | ―- | -0.06 | ― | ― |
| Nov 16, 2026 | 2026 (Q3) | ―-0.07 | -0.03 | -150.00% (-0.04) | |
| Aug 13, 2026 | 2026 (Q2) | ―-0.04 | -0.01 | -200.00% (-0.03) | |
| May 13, 2026 | 2026 (Q1) | ―-0.06 | -0.03 | -100.00% (-0.03) | |
| Mar 31, 2026 | 2025 (Q4) | 0.00-0.06 | -0.03 | -100.00% (-0.03) | |
| Nov 13, 2025 | 2025 (Q3) | 0.01-0.03 | 0.04 | -164.52% (-0.07) | |
| Aug 14, 2025 | 2025 (Q2) | -0.01-0.01 | 0.03 | -150.00% (-0.04) | |
| May 15, 2025 | 2025 (Q1) | 0.01-0.03 | -0.04 | 25.93% (+0.01) | |
| Mar 27, 2025 | 2024 (Q4) | 0.040.04 | -0.05 | 193.75% (+0.09) | |
| Nov 14, 2024 | 2024 (Q3) | ―0.03 | -0.03 | 203.33% (+0.06) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
