


Dexterra Group earnings date
Want to see TSE:DXT full AI Analyst Report?
Dexterra Group (DXT) Q3 2026 Earnings Report
TSE:DXT Q3 2026 EPS Results
- Actual EPS
- CAD 0.22
- Consensus EPS
- CAD 0.22
- Beat/Miss
- Missed by -CAD 0.00
- One Year Ago EPS
- CAD 0.21
TSE:DXT Q3 2026 Revenue Results
- Actual Revenue
- CAD 291.23M
- Expected Revenue
- CAD 305.56M
- Beat/Miss
- Missed by -CAD 14.33M
- YoY Revenue Growth
- +3.56%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 11/04/2026
- Time
- After Close
- Conference Call
- Wednesday, November 4, 2026
Dexterra Group's next earnings date is estimated for March 10, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q3 2026 Earnings Slide Deck
Q3 2026 Earnings Call Summary
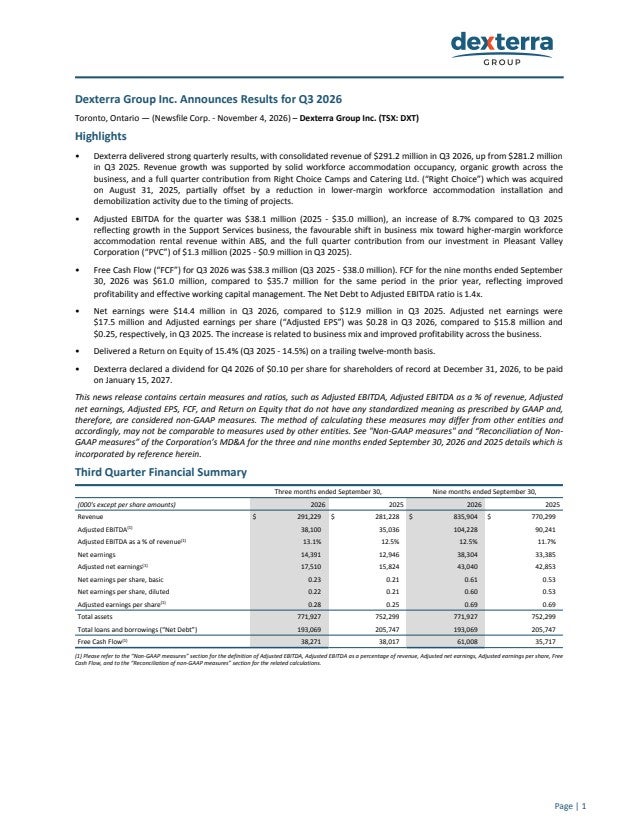
The call was strongly positive overall. Dexterra reported record annual adjusted EBITDA, revenue and EBITDA growth, margin expansion, strong free cash flow, improved leverage, achievement of its return on equity target, and progress across its Canadian and U.S. growth initiatives. The main negative factors were unusually low wildfire support activity, a CAD 10 million year-over-year decline in installation and demobilization revenue due to project timing, near-term PVC cash flow neutrality, and uncertainty around the timing of project awards and data center expansion.
Management expects support services adjusted EBITDA margins to exceed 9% over the medium term and be in that 9% range, while Asset Based Services adjusted EBITDA margins are expected to be overall at the higher end of our 30%-40% range in 2026. The company continues to expect to generate the majority of its free cash flow in the back half of 2026, with annual adjusted EBITDA to free cash flow conversion to exceed 50%, and remains committed to net debt to adjusted EBITDA of less than 2.5x. New FM and IFM contracts are expected to mobilize and ramp up through the first half of 2027; installation and demobilization activity is expected to include some in Q4, more in 2027, and be probably increasing through 2027. Dexterra expects to acquire additional beds over the next 12 months, including an additional 1,500 beds, with approximately 2,500 beds available for deployment over the medium term, increasing deployable capacity by 4,000 total and overall fleet capacity to 14,000 beds total.
- Record EBITDA and Strong Q3 Financial PerformanceManagement described Q3 as traditionally Dexterra's strongest quarter and reported record annual adjusted EBITDA, revenue of CAD 291 million versus CAD 281 million last year, adjusted EBITDA of CAD 38 million, up 9% year-over-year, adjusted EBITDA margin of 13% versus 12.5%, and adjusted net earnings per share of CAD 0.28, up 12%.
- Broad-Based Revenue Growth Despite Lower Wildfire ActivityRevenue growth was supported by strong workforce accommodation occupancy and rental activity, positive organic growth, and contributions from the Right Choice acquisition, despite significantly lower wildfire support and workforce accommodation installation and demobilization activity compared with the same quarter last year.
- Market Capitalization MilestoneDexterra surpassed CAD 1 billion in market capitalization for the first time in the company's history, which management attributed to progress in facilities management, workforce accommodations, strategic acquisitions, disciplined capital allocation, and consistent financial performance.
- Support Services Revenue and EBITDA GrowthSupport services revenue increased 8% year-over-year to CAD 253 million, driven primarily by strong workforce accommodation occupancy, continued U.S. facilities management growth, and the Right Choice acquisition. Organic growth was 4.5%, adjusted EBITDA increased 18% to CAD 29 million, and adjusted EBITDA margin expanded to 11.5% from 10.5%.
- Mid-Single-Digit Organic Growth Across Support Services PlatformsManagement said organic growth for both the facilities management business and workforce accommodation remote services was within expectations at a mid-single-digit level for the quarter, with no significant difference between the two platforms.
- Higher Workforce Accommodation Occupancy Supported MarginsHigh occupancy in workforce accommodations helped drive the higher support services margin. Excluding PVC, support services adjusted EBITDA margin increased to 11% from 10%, primarily due to higher-margin workforce accommodation contracts.
- PVC Contribution and Platform DevelopmentDexterra's 40% investment in PVC contributed CAD 1.3 million to adjusted EBITDA in Q3 versus CAD 0.9 million in Q3 2025. The partnership is progressing, including on-time and on-budget modernization of the proprietary PVC Connect facility management software.
- Asset Based Services Margin ExpansionAsset Based Services generated CAD 39 million of revenue. Higher-margin rental revenue increased 2.3%, supported by strong equipment utilization, solid access matting revenue, and a contribution from Right Choice. Adjusted EBITDA was CAD 16 million, consistent with the prior year, while adjusted EBITDA margin expanded to 41% from 34% due primarily to a favorable shift toward high-margin rental revenue.
- Effective Inflation and Supply Chain ManagementManagement said inflationary pressures were being managed through supply chain initiatives, contractual inflation terms, and price adjustments. Direct costs represented a lower percentage of revenue for both business segments than in the same period last year.
- Strong Free Cash Flow and Balance Sheet ImprovementDexterra generated CAD 38 million of free cash flow in Q3 and CAD 61 million year-to-date, driven by strong profitability and positive improvements in working capital. Net debt declined to CAD 193 million from CAD 206 million at Q2, and net debt-to-adjusted EBITDA improved to 1.4x from 1.6x at the end of 2025.
- Return on Equity Target AchievedTrailing 12-month return on equity was 15.4% at the end of Q3, exceeding the company's 15% target.
- Growth Capital for Workforce Accommodation FleetQ3 capital expenditures were CAD 15 million, including CAD 12 million of growth capital for approximately 500 workforce accommodation beds that are being refurbished for deployment into growth pipelines. Management described the investment as disciplined, cost-effective, targeted, and expected to generate attractive returns.
- Liquidity and Shareholder ReturnsDexterra's CAD 425 million credit facility matures in 2029 and has significant available capacity, plus an uncommitted CAD 150 million accordion. The company purchased approximately 118,000 shares in Q3, maintains an NCIB allowing buybacks of up to 3 million shares, and declared a dividend of CAD 0.10 per share payable January 15, 2027.
- Strong and Diverse Growth PipelineManagement described the sales pipeline as strong and diverse across Canada and the U.S. The remote-side opportunity set was described as substantial and among the largest the company has seen, spanning mining, energy, infrastructure, government, defense, workforce accommodations, and remote facilities management.
- U.S. Facilities Management Platform Positioned for GrowthDexterra has established its U.S. leadership, executive sales leadership, and sales team supporting PVC, CMI, and self-perform IFM. Management said the platform has the resources needed for the near to mid-term and is seeing traction on new projects in both Canada and the U.S.
- New Facilities Management WinsThe company secured new FM and IFM contract wins in 2026, including within PVC, and expects to mobilize and ramp up those contracts through the first half of 2027.
- Nation-Building Opportunity and Indigenous PartnershipsDexterra is actively pursuing bids and proposals across energy projects, pipelines, mining, defense, government infrastructure, power, roads, data centers, and other opportunities. Management highlighted more than 80 Indigenous community partnerships, Canada-wide market presence, and experience in turnkey workforce accommodations, hospitality, catering, and facilities management.
- Planned Fleet ExpansionDexterra currently has approximately 2,500 fleet beds available for deployment over the medium term and is pursuing an additional 1,500 beds, which would increase deployable capacity by 4,000 beds and overall fleet capacity to 14,000 beds. The company expects to acquire the additional beds over the next 12 months and will use its Grande Prairie refurbishment facility.
- Pricing Positivity in Elastic SegmentsManagement reported pricing positivity in elastic segments, including open camps, turnkey opportunities, and equipment rental. It has already seen pricing uplift in bids and contracts in those segments and expects pricing to increase as contract awards are made and equipment is deployed.
- Data Center Business Development ActivityDexterra is active on workforce accommodation opportunities in Louisiana and West Texas, is bidding on Canadian data center-related projects, and is pursuing a facilities management bid for an operating U.S. data center.
- Tariff Exposure and Inflation OutlookManagement said the business remains well-insulated from the direct impact of tariffs because it employs its workforce locally and sources the majority of materials and supplies domestically in Canada and the U.S. Based on current conditions, it does not expect inflation to have a material impact on the business over the near term.
- Capital Allocation and Technology PrioritiesManagement reiterated priorities of supporting the dividend, making sustaining and high-return capital investments, maintaining debt-to-adjusted EBITDA below 2.5x, and pursuing accretive acquisitions. The company is also continuing strategic investments in enterprise and client-facing technology to drive innovation, operational efficiency, and service differentiation.
TSE:DXT Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Mar 10, 2027 | 2026 (Q4) | 0.19- | 0.12 | ― | ― |
| Nov 04, 2026 | 2026 (Q3) | 0.220.22 | 0.21 | 4.76% (+0.01) | |
| Aug 04, 2026 | 2026 (Q2) | 0.160.16 | 0.19 | -15.79% (-0.03) | |
| May 06, 2026 | 2026 (Q1) | 0.150.22 | 0.14 | 57.14% (+0.08) | |
| Mar 03, 2026 | 2025 (Q4) | 0.180.12 | 0.11 | 9.09% (+0.01) | |
| Nov 04, 2025 | 2025 (Q3) | 0.220.21 | 0.12 | 75.00% (+0.09) | |
| Aug 05, 2025 | 2025 (Q2) | 0.200.19 | 0.14 | 35.71% (+0.05) | |
| May 06, 2025 | 2025 (Q1) | 0.140.14 | -0.06 | 333.33% (+0.20) | |
| Mar 06, 2025 | 2024 (Q4) | 0.140.11 | 0 | ― | |
| Nov 05, 2024 | 2024 (Q3) | 0.210.12 | 0.21 | -42.86% (-0.09) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
