

Thinkific Labs (THNCF) Q3 2026 Earnings Report
THNCF Q3 2026 EPS Results
- Actual EPS
- -$0.06
- Consensus EPS
- -$0.02
- Beat/Miss
- Missed by -$0.04
- One Year Ago EPS
- $0.01
THNCF Q3 2026 Revenue Results
- Actual Revenue
- $18.97M
- Expected Revenue
- $18.81M
- Beat/Miss
- Beat by +$156.65K
- YoY Revenue Growth
- +4.00%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 11/03/2026
- Time
- After Close
- Conference Call
- Tuesday, November 3, 2026
Thinkific Labs's next earnings date is estimated for March 10, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q3 2026 Earnings Slide Deck
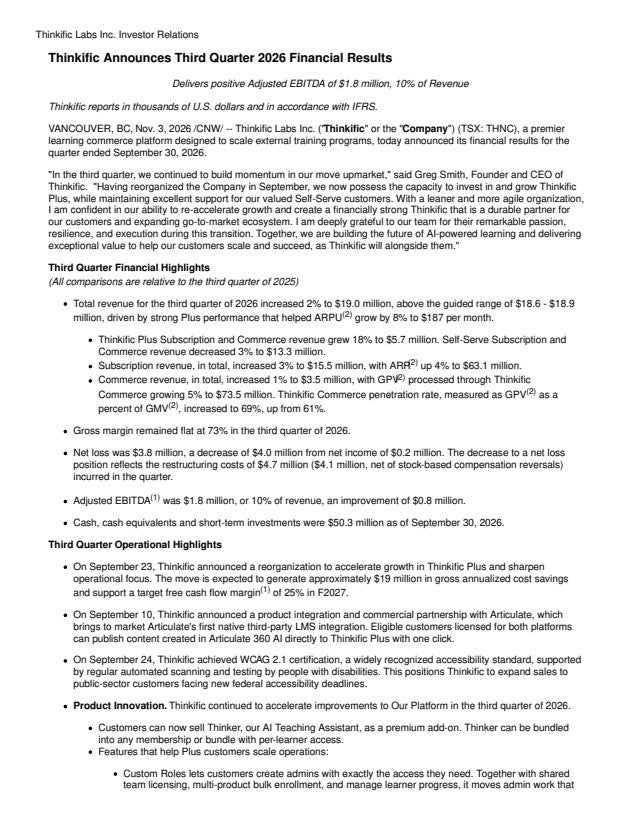
Q3 2026 Earnings Call Summary
The call was strongly positive overall. Management highlighted accelerating Plus growth, revenue above guidance, improved monetization, substantial cost savings, stronger profitability, faster product development and promising enterprise partnerships. These positives outweighed the ongoing Self-Serve revenue and ARR declines, lower GMV and restructuring-related cash costs.
For Q4 2026, Thinkific expects revenue of $18.9 million to $19.2 million and adjusted EBITDA of 20% to 25% of revenue, with continued Plus ARR growth and a return to contraction in Self-Serve ARR; the EBITDA outlook includes the full run rate benefit of September headcount cost reductions, which comprised approximately 2/3 of the total expense rationalization announced. The company expects approximately $19 million in gross annualized savings, with the full amount realized in 2027, and says Self-Serve subscription revenue will continue to decline in the low single digits going forward, with greater volatility over the next couple of quarters. Longer-term comments are not formal 2027 guidance; assuming modest overall revenue growth, Thinkific continues to target 25% free cash flow margins.
- Plus Growth Accelerated Through Upmarket FocusThinkific Plus growth accelerated to 18% from 12% two quarters ago. The company said its focus on larger, more successful customers is showing a direct tie to revenue, with improved go-to-market execution and product capabilities supporting higher-value use cases.
- Reorganization Improved Focus and Operating SpeedThe reorganization created more capacity for the fastest-growing market, simplified the organization, clarified ownership and accelerated decision-making. Thinkific said it is already seeing gains in output and velocity, particularly in R&D, while its sales organization was essentially unaffected and continued executing without interruption.
- No Reported Degradation in Customer MetricsFollowing the reorganization, Thinkific reported no related degradation in customer support, customer satisfaction or retention. Management said some key areas have actually accelerated since the changes.
- Permanent Cost Efficiencies and Savings PlanThe company expects approximately $19 million in gross annualized savings compared with the expenses it would have incurred without the reorganization. Savings came from flattening operational layers, rationalizing noncore spending and reducing headcount-related expenses, with the majority of the benefit expected beginning in Q4 and the full amount realized in 2027.
- Q3 Revenue Exceeded GuidanceThird-quarter revenue was $19.0 million, up 2% year-over-year and slightly above the guidance range of $18.6 million to $18.9 million.
- ARR Increased and Pricing Updates Supported ResultsTotal ARR increased by $1.4 million during the quarter. The increase was significantly supported by the August 15 Self-Serve pricing change, Thinkific's first Self-Serve pricing update in many years, which was phased in as subscription periods ended.
- Plus Revenue Increased 18%Plus revenue was $5.7 million, up 18% year-over-year. Growth benefited from improved go-to-market execution, product capabilities supporting higher-value use cases and higher year-over-year GPV contributing to improved Commerce revenue in the segment.
- Plus Subscription Growth AcceleratedManagement clarified that Plus subscription growth excluding Commerce was in the mid- to high-teens range, specifically approximately 15% to 18% in Q3, and was accelerating. A six-digit Plus customer booked during the quarter contributed some additional lift to deal size, but management said the growth was not one-time in nature.
- Improved Monetization and Payments PenetrationGPV was $74 million, up 5% compared with 2025, as higher payments penetration more than offset the decline in GMV. Payments penetration reached 69.3%, up 2.5 percentage points sequentially. Average revenue per user increased 8% year-over-year to $187 per month, reflecting a mix shift toward higher-value Plus customers.
- Strong Profitability and Cash PositionAdjusted EBITDA was $1.8 million, or 10% of revenue, supported by lower operating expenses. Adjusted operating expenses were $13.7 million, down 1% year-over-year. Cash and short-term investments were $50 million at September 30, and management said the company is in the strongest financial position in its history.
- Q4 Profitability Guidance IncreasedFor Q4 2026, Thinkific expects revenue of $18.9 million to $19.2 million and adjusted EBITDA of 20% to 25% of revenue. The EBITDA outlook includes the full run-rate benefit of the September headcount cost reductions.
- Long-Term Free Cash Flow Target MaintainedThinkific continues to target a 25% free cash flow margin in 2027, based on modest overall revenue growth and planned further non-headcount-related operating expense reductions. The company also reiterated its commitment to maintaining a strong balance sheet and not spending ahead of growth.
- Articulate Partnership Expanded Enterprise OpportunityThinkific partnered with Articulate, a workplace training platform used by 125,000 organizations worldwide. Customers can publish Articulate content directly to Thinkific Plus in one click, representing Articulate's first native integration with a third-party LMS. The partnership has already helped with deals and pipeline generation, produced strong lead generation and introduced Thinkific to larger customers than historically. The arrangement includes two-way promotion, sales-team collaboration, in-product exposure and temporary exclusivity.
- New Go-to-Market Channels EmergingThe upmarket focus is creating new go-to-market opportunities, including in-person events, reseller partnerships and the Articulate relationship. Thinkific said introductions are moving in both directions between the companies and are creating expansion opportunities for both platforms.
- Product Development Velocity IncreasedThinkific said it is executing its product roadmap at a significantly faster pace than last year, releasing new customer-facing functionality each week. Management attributed the acceleration partly to AI as well as process improvements and said the increased velocity is beginning to influence retention, expansion and new-deal opportunities.
- Expanded Enterprise Administration and Learning FeaturesThe company introduced significantly improved custom roles and permissions, multi-learning-product and multi-learner enrollment programs, phased subscription pricing and Group Experiences. These capabilities address the needs of larger organizations managing multiple sites, learner groups, products, content libraries and corporate clients.
- AI Teaching Assistant Became a Premium Add-OnThinker, Thinkific's AI teaching assistant, became available as a premium add-on. Customers can package it into memberships and sell direct learner access, creating a new profit center for customers.
- Reimagined Learning and Building Experience ReleasedThinkific launched a completely reimagined learning experience, builder and player for all customers. Management said the new functionality enables more modern and customizable learning experiences and differentiates Thinkific from other learning systems.
- Accessibility Compliance Opened Regulated-Market OpportunitiesThinkific achieved WCAG 2.1 AA accessibility compliance. Management said this is already creating opportunities in higher education, government and other regulated industries facing new federal accessibility mandates.
- Self-Serve Price Increase Had Better-Than-Budgeted RetentionManagement said the Self-Serve pricing change produced a positive return, with customer retention and stickiness better than budgeted. The company attributed the favorable response partly to the relatively small individual customer impact, simple communication and the long period since the prior price update.
- Disciplined AI Cost ManagementThinkific expects to spend more on AI over the next year but said it is not operating in 'token maxing mode.' The company is selecting different models for different tasks, including less expensive models when frontier models are unnecessary, and said it does not expect increased AI spending to erode the gains from the restructuring.
- Potential Capital Deployment OptionsWith cash expected to continue growing, management and the Board will evaluate how to deploy capital in 2027. Options include internal investment and potentially returning some cash to shareholders.
THNCF Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Mar 10, 2027 | 2026 (Q4) | 0.01- | 0.01 | ― | ― |
| Nov 03, 2026 | 2026 (Q3) | -0.02-0.06 | 0.01 | -700.00% (-0.07) | |
| Aug 05, 2026 | 2026 (Q2) | -0.020.00 | 0.01 | -100.00% (-0.01) | |
| May 04, 2026 | 2026 (Q1) | -0.01-0.02 | 0.01 | -300.00% (-0.03) | |
| Mar 05, 2026 | 2025 (Q4) | 0.000.01 | -0.01 | 200.00% (+0.02) | |
| Nov 12, 2025 | 2025 (Q3) | 0.000.01 | 0.01 | 0.00% (+0.00) | |
| Aug 06, 2025 | 2025 (Q2) | 0.000.01 | 0.01 | 0.00% (+0.00) | |
| May 06, 2025 | 2025 (Q1) | 0.000.01 | -0.01 | 200.00% (+0.02) | |
| Mar 05, 2025 | 2024 (Q4) | 0.01-0.01 | 0 | ― | |
| Nov 05, 2024 | 2024 (Q3) | -0.010.01 | -0.01 | 200.00% (+0.02) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
