

Starbucks (SBUX) Q4 2026 Earnings Report
MX:SBUX Q4 2026 EPS Results
- Actual EPS
- MXN 15.03
- Consensus EPS
- MXN 13.51
- Beat/Miss
- Beat by +MXN 1.52
- One Year Ago EPS
- MXN 9.77
MX:SBUX Q4 2026 Revenue Results
- Actual Revenue
- MXN 171.78B
- Expected Revenue
- MXN 173.35B
- Beat/Miss
- Missed by -MXN 1.56B
- YoY Revenue Growth
- -4.45%
Earnings Announcement Details
- Quarter
- Q4 2026
- Date
- 10/29/2026
- Time
- After Close
- Conference Call
- Thursday, October 29, 2026
Starbucks's next earnings date is estimated for February 2, 2027, based on past reporting schedules.
Q4 2026 Earnings Call Audio
Q4 2026 Earnings Slide Deck
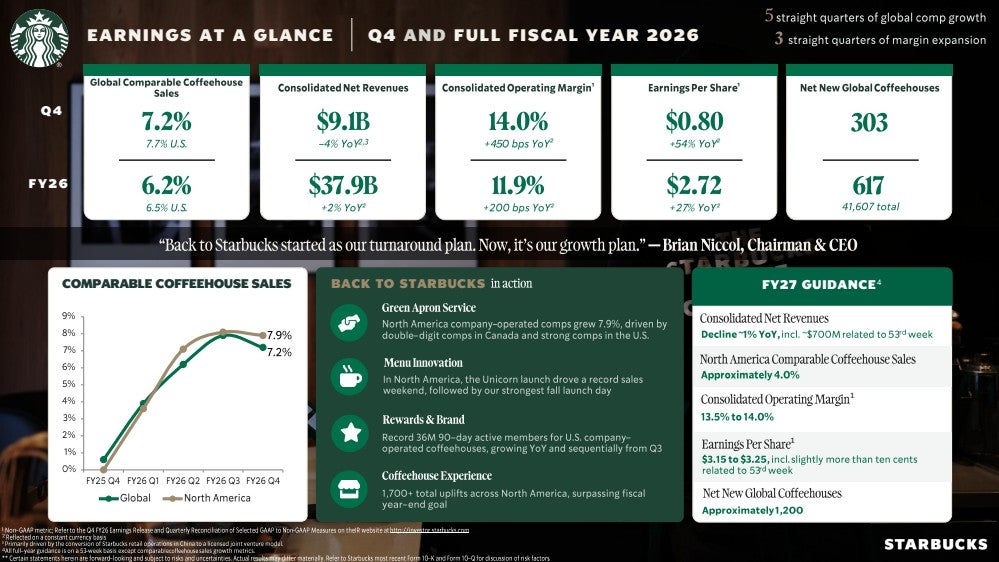
Q4 2026 Earnings Call Summary
The call was strongly positive. Starbucks reported five consecutive quarters of global comp growth, substantial fourth-quarter and full-year margin expansion, strong EPS growth, record Rewards membership and progress on its Back to Starbucks strategy. Management also raised or provided constructive fiscal 2027 expectations, citing continued cost savings, operational improvements, international unit growth and technology initiatives. The main negatives were the consolidated revenue decline tied to the China licensing transition, expected fiscal 2027 revenue and Channel Development declines, North American store closures and a temporary reduction in company-operated openings. Overall, the highlights significantly outweighed the lowlights.
For fiscal '27, Starbucks expects North America comps to grow approximately 4%, full year consolidated net revenues to decrease by approximately 1% year-over-year, including approximately $700 million of revenues related to the 53rd week, and Channel Development net revenues to decline by approximately 10%; it expects consolidated operating margin of 13.5% to 14%, up approximately 190 basis points at the midpoint, EPS of $3.15 to $3.25, growing close to 18% year-over-year at the midpoint, and approximately 1,200 net new coffeehouses globally, including approximately 1,100 net new openings internationally with China contributing about half and 90 to 100 net new coffeehouses in North America, about half from the licensed portfolio. The company expects North America net revenue growth to slightly exceed comp growth, pricing to remain focused and well below CPI, consolidated G&A dollars to be flat to slightly down year-over-year, international operating margin to begin the year at around 20% and improved slightly through the year, channel development operating margin to remain in the mid- to high 40% range over the longer term, its effective tax rate to be roughly in line with or slightly below fiscal '26, capital expenditures to be approximately 5% of net revenues, and approximately $1 billion towards share repurchases; guidance includes a benefit of slightly more than $0.10 related to the 53rd week.
- Strong Fourth-Quarter Comp GrowthGlobal comparable sales increased 7.2%, marking the fifth consecutive quarter of comp growth. North America company-operated comps grew 7.9%, while U.S. comps increased 7.7%, including transaction growth of 2.4% and ticket growth of 5.2%.
- Full-Year Revenue, Margin and EPS GrowthFiscal 2026 consolidated net revenues grew 2.1% to $37.9 billion. Consolidated operating margin expanded 200 basis points to 11.9%, and EPS increased approximately 27% to $2.72, exceeding the high end of guidance.
- Fourth-Quarter Margin Expansion and EPS GrowthFourth-quarter consolidated operating margin expanded 450 basis points year-over-year to approximately 14%, the third consecutive quarter of margin expansion. Fourth-quarter EPS increased approximately 54% to $0.80.
- North America Revenue and Margin PerformanceNorth America fourth-quarter net revenues grew 6.3% to $7.3 billion. North America operating margin expanded 440 basis points to approximately 16%, driven primarily by sales leverage, disciplined execution and cost savings.
- Improved Coffeehouse ExecutionMore than 80% of North America company-operated coffeehouses delivered positive comps in the quarter, up from less than 50% a year ago. Average service times remained on target, and the company continued refining Smart Queue and operating routines to improve throughput and consistency.
- Higher Inventory Availability and Supply-Chain ProgressInventory availability reached an all-time high, with daily delivery reaching close to 90% of North America company-operated coffeehouses. Starbucks said supply-chain work is intended to improve demand forecasting, ordering accuracy and replenishment cycles, with replenishment expected to improve over the next 6 to 12 months.
- Coffeehouse Uplift Program Exceeded GoalStarbucks completed more than 1,700 coffeehouse uplifts across North America by fiscal year-end, surpassing its goal. Uplifted coffeehouses continued to show transaction lift across access points, dayparts, formats and loyalty groups, and the company expects to complete more than 2,000 uplifts in fiscal 2027.
- Record Starbucks Rewards Membership90-day active Starbucks Rewards members reached a record 36 million, increasing both year-over-year and sequentially from the third quarter. Starbucks said Rewards members led transaction and sales growth, with members moving into higher-frequency tiers.
- Brand and Product Innovation MomentumStarbucks reported near-record brand affinity and continued strength in Espresso, Refreshers, Matcha and the artisanal bake case. The Unicorn launch across 34 markets delivered a record sales weekend for the North America company-operated business, while the company reported its strongest North America fall launch day and robust sales from the global Peanuts collaboration.
- Delivery Growth and Digital ExpansionU.S. delivery revenues have more than tripled over the past five years, and Starbucks said delivery transactions have been largely incremental. The company plans to integrate delivery directly into the Starbucks app in the second quarter and allow customers to earn and redeem Stars on delivery orders.
- International Unit GrowthStarbucks ended fiscal 2026 with 41,607 coffeehouses globally, including 617 net new openings for the full year, ahead of its most recent expectations. International ended the quarter with 23,431 coffeehouses and 498 net new openings in the fourth quarter, while Starbucks surpassed 6,000 coffeehouses in Asia Pacific and grew to more than 1,900 in Latin America and the Caribbean.
- International Growth OpportunitiesThe company said international is expected to lead global unit growth in fiscal 2027, with net new coffeehouse openings accelerating by nearly 50% compared with fiscal 2026, or approximately three new coffeehouses per day. Starbucks sees potential to grow its international footprint from more than 23,000 coffeehouses today to nearly 40,000 over the long term, including the potential to double its presence in China and India.
- Fiscal 2027 Earnings and Margin GuidanceStarbucks expects fiscal 2027 consolidated operating margin of 13.5% to 14%, up approximately 190 basis points at the midpoint, and EPS of $3.15 to $3.25, growing close to 18% year-over-year at the midpoint. The guidance includes a benefit of slightly more than $0.10 from the 53rd week.
- Cost-Savings Program ProgressStarbucks has achieved more than 50% of its $2 billion gross savings program. The company expects additional savings from operating expenses and cost of goods sold to become more evident in fiscal 2027 and fiscal 2028, while consolidated G&A dollars are expected to be flat to slightly down year-over-year.
- Technology, AI and Drive-Thru InitiativesFiscal 2027 will include rollout of new staffing, scheduling and point-of-sale systems. Starbucks will test AI models in the drive-thru to help baristas input orders more accurately and efficiently, while also exploring personalized digital menus, easier payment and mobile ordering from cars and emerging AI platforms.
- Partner Retention and Leadership DevelopmentHourly partner turnover remains well below the industry average, which Starbucks attributed to industry-leading pay and benefits, improved staffing and flexible schedules. More than 3,000 North America coffeehouse coaches are enrolled, all hired from within the company, and Starbucks plans to expand the program in fiscal 2027.
- Shareholder Returns and Capital AllocationStarbucks raised its quarterly dividend to $0.63 per share, representing its 16th consecutive annual increase. The company expects to deploy approximately $1 billion toward share repurchases, maintain its investment-grade balance sheet and spend approximately 5% of net revenues on capital expenditures in fiscal 2027.
- Afternoon Occasion and Matcha GrowthStarbucks reported increased afternoon attach following upgrades to its food and pastry case, with traffic and sales improving across all dayparts. Its Matcha business has become a more than $1 billion platform and is growing substantially year-over-year, with cold beverages and cold foam contributing to afternoon demand.
MX:SBUX Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Feb 02, 2027 | 2027 (Q1) | 14.17- | 10.52 | ― | ― |
| Oct 29, 2026 | 2026 (Q4) | 13.5115.03 | 9.77 | 53.85% (+5.26) | |
| Jul 29, 2026 | 2026 (Q3) | 12.4015.97 | 9.4 | 70.00% (+6.58) | |
| Apr 28, 2026 | 2026 (Q2) | 7.999.40 | 7.7 | 21.95% (+1.69) | |
| Jan 28, 2026 | 2026 (Q1) | 11.0110.52 | 12.97 | -18.84% (-2.44) | |
| Oct 29, 2025 | 2025 (Q4) | 10.459.77 | 15.03 | -35.00% (-5.26) | |
| Jul 29, 2025 | 2025 (Q3) | 12.169.40 | 17.48 | -46.24% (-8.08) | |
| Apr 29, 2025 | 2025 (Q2) | 9.137.70 | 12.78 | -39.71% (-5.07) | |
| Jan 28, 2025 | 2025 (Q1) | 12.5312.97 | 16.91 | -23.33% (-3.95) | |
| Oct 30, 2024 | 2024 (Q4) | 16.3115.03 | 19.92 | -24.53% (-4.89) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
