

MSA Safety (MSA) Q2 2026 Earnings Report
MX:MSA Q2 2026 EPS Results
- Actual EPS
- MXN 44.53
- Consensus EPS
- MXN 39.61
- Beat/Miss
- Beat by +MXN 4.92
- One Year Ago EPS
- MXN 35.81
MX:MSA Q2 2026 Revenue Results
- Actual Revenue
- MXN 9.34B
- Expected Revenue
- MXN 9.21B
- Beat/Miss
- Beat by +MXN 130.90M
- YoY Revenue Growth
- +6.16%
Earnings Announcement Details
- Quarter
- Q2 2026
- Date
- 07/30/2026
- Time
- After Close
- Conference Call
- Thursday, July 30, 2026
Q2 2026 Earnings Call Audio
Q2 2026 Earnings Slide Deck
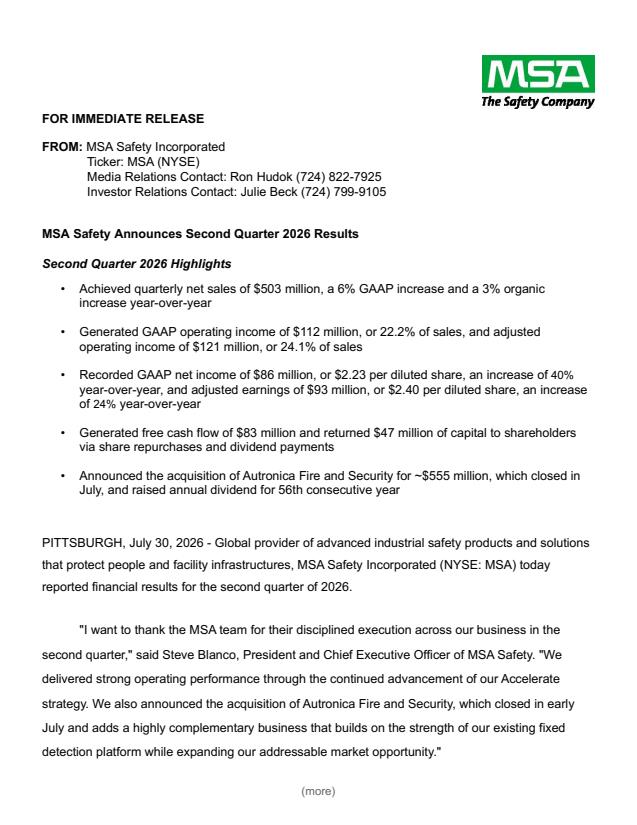
Q2 2026 Earnings Call Summary
The call conveyed solid financial performance: double-digit margin expansion, strong EPS growth, robust free cash flow and successful M&A execution, alongside clear product and technology momentum (MSA+ adoption and industrial PPE strength). Offsetting this were notable regional headwinds—chiefly the Middle East conflict—timing delays in fire-service AFG orders, some non-recurring tariff benefit to margins, and supply-chain/input-cost pressures that are expected to temper gross margins in H2. Management maintained a positive outlook (low-double-digit total revenue growth for 2026 with mid-single-digit organic growth) while signaling disciplined capital allocation and a target leverage range.
MSA guided to low-double-digit total revenue growth for 2026, driven by mid-single-digit organic growth, a mid-single-digit contribution from acquisitions and 1–2 points of favorable translational FX, reiterated mid-single-digit organic guidance, and expects full-year adjusted gross margin of 47.5%–48.5% (with a moderate H2 tempering as higher-cost inventory from the Middle East flows through over 90–120 days); interest expense is modeled at $40–43 million, tax rate and pension income are unchanged, and the company will prioritize debt repayment while continuing share repurchases at a lower H2 pace; pro forma net leverage post‑Autronica is ~1.8x (Q2 adjusted net leverage was 0.8x, net debt down $33M sequentially), liquidity was $1.2B at quarter end ($600M pro forma), weighted average interest rate was 3.8%, first‑half returns to shareholders were $118M (Q2 $47M), first‑half free cash flow conversion was 94%, the quarter included a ~$4M tariff refund (~100 bps benefit), and going forward M&C and MSA+ contributions are reflected in organic results.
- Revenue GrowthSecond quarter sales of $503 million, up 6% on a reported basis and up 3% organically year-over-year; currency translation provided a ~2 percentage-point tailwind and M&C contributed ~1 percentage-point.
- Earnings and Margin ExpansionAdjusted EPS of $2.40, up 24% versus prior year; GAAP diluted EPS $2.23, up 40%. GAAP gross margin of 49.5% (up ~290 basis points year-over-year and +210 bps sequentially). Adjusted operating margin of 24.1%, up ~270 bps year-over-year.
- Strong Free Cash Flow and Capital ReturnsGenerated $83 million of free cash flow in the quarter (96% of earnings) and first-half free cash flow conversion of 94%; returned $47 million to shareholders in Q2 and $118 million in the first half (a 45% increase versus prior year).
- Acquisition and M&A ActivityCompleted acquisition of Autronica Fire & Security in early July; M&A pipeline described as robust and management remains active while targeting a net leverage sweet spot of 1.5x–2.5x.
- Product and Technology MomentumMSA+ connected solutions represented >50% of portable gas detection growth and now account for 14% of total portable sales (up from 10% a year ago); early customer feedback for ALTAIR io 6 is positive and adoption accelerating.
- Industrial PPE StrengthOrganic industrial PPE sales increased 16% year-over-year, driven by strong demand across core industrial markets and OEM/product adoption (e.g., H2 type 2 safety helmet adoption in Americas).
- Healthy Balance Sheet MetricsQuarter-end liquidity of $1.2 billion (pro forma post-Autronica ~$600 million), net debt decreased sequentially, adjusted net leverage 0.8x (pro forma 1.8x after acquisition) and weighted average interest rate ~3.8%.
MX:MSA Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Nov 02, 2026 | 2026 (Q3) | 38.70- | 36 | ― | |
| Jul 30, 2026 | 2026 (Q2) | 39.6144.53 | 35.81 | 24.35% (+8.72) | |
| May 04, 2026 | 2026 (Q1) | 33.8836.92 | 31.17 | 18.45% (+5.75) | |
| Feb 11, 2026 | 2025 (Q4) | 41.9144.16 | 41.75 | 5.78% (+2.41) | |
| Oct 28, 2025 | 2025 (Q3) | 34.6436.00 | 33.95 | 6.01% (+2.04) | |
| Aug 04, 2025 | 2025 (Q2) | 32.5635.81 | 37.29 | -3.98% (-1.48) | |
| Apr 29, 2025 | 2025 (Q1) | 29.3031.17 | 29.87 | 4.35% (+1.30) | |
| Feb 12, 2025 | 2024 (Q4) | 41.6041.75 | 38.22 | 9.22% (+3.53) | |
| Oct 23, 2024 | 2024 (Q3) | 33.4933.95 | 33.03 | 2.81% (+0.93) | |
| Jul 24, 2024 | 2024 (Q2) | 36.3337.29 | 33.95 | 9.84% (+3.34) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
