

Keyera Corp. (KEYEN) Q2 2026 Earnings Report
MX:KEYEN Q2 2026 EPS Results
- Actual EPS
- MXN 15.99
- Consensus EPS
- MXN 2.65
- Beat/Miss
- Beat by +MXN 13.35
- One Year Ago EPS
- MXN 7.39
MX:KEYEN Q2 2026 Revenue Results
- Actual Revenue
- MXN 29.96B
- Expected Revenue
- MXN 26.71B
- Beat/Miss
- Beat by +MXN 3.25B
- YoY Revenue Growth
- +44.97%
Earnings Announcement Details
- Quarter
- Q2 2026
- Date
- 08/06/2026
- Time
- Before Open
- Conference Call
- Thursday, August 6, 2026
Keyera Corp.'s next earnings date is estimated for November 10, 2026, based on past reporting schedules.
Q2 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q2 2026 Earnings Slide Deck
Q2 2026 Earnings Call Summary
The call emphasized multiple strong operational and financial achievements — record segment margins, successful integrations and project execution (including KFS Frac 2 delivered 20% under budget and early), meaningful day‑1 synergies ($90M), dividend growth (+4%), and reaffirmed guidance and multi‑year growth targets. Offsetting items include a weaker marketing quarter driven by the AEF outage (marketing realized margin $36M), temporarily elevated leverage at 3.3x net debt/EBITDA with a plan to deleverage by 2028, modest near‑term maintenance/integration costs, and an ongoing Competition Tribunal matter. Overall, the positives (acquisitions, record margins, project delivery, synergies and clear growth/hedging strategy) materially outweigh the near‑term challenges and risks.
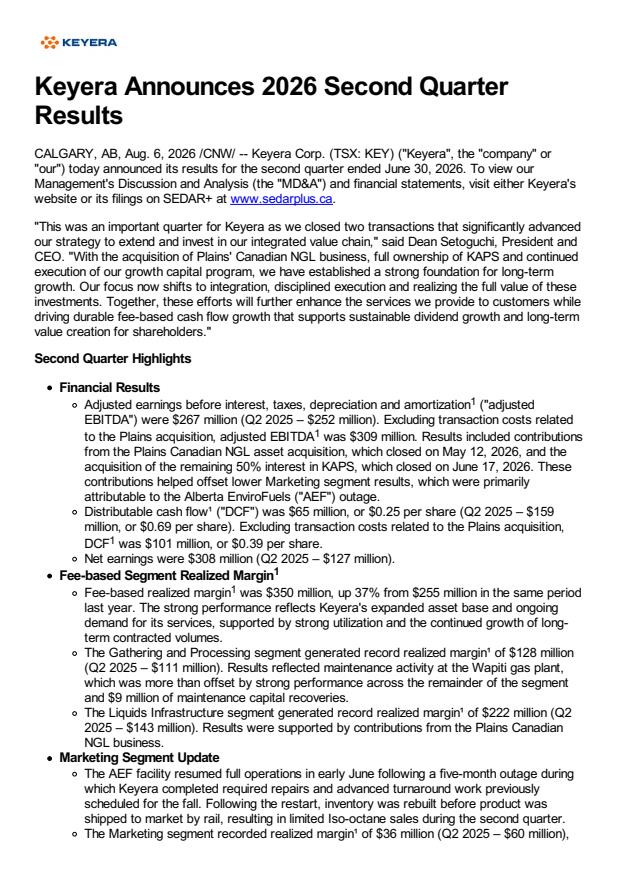
Keyera reaffirmed its 2026 realized margin guidance of $360–$390 million, while keeping 2026 growth capital, maintenance capital and cash tax guidance unchanged; Q2 reported adjusted EBITDA (ex‑transaction costs) of $309M, distributable cash flow of $101M or $0.39/share, and net earnings of $308M, with segment realized margins of $128M (Gathering & Processing), $222M (Liquids Infrastructure) and $36M (Marketing). Management highlighted delivery of $90M of day‑one synergies and a current synergy target of $120–$140M, on‑time/on‑budget execution of KFS North, KFS Frac 3, KAPS Zone 4 and ACE Rail Terminal (KFS Frac 2 placed into service >1 month early and ~20% below original budget), a Board‑approved 4% dividend increase, and a balance‑sheet focus to deleverage from Q2 net debt/adjusted EBITDA of 3.3x back into a stated ~2.5–3.0x target by 2028; fee‑based adjusted EBITDA per share CAGRs of 16–18% (2025–2027) and 7–8% (2027–2029) underpinned the outlook, together with marketing and frac‑spread hedging (65%+ coverage noted) to support cash flow.
- Strategic Acquisitions ClosedClosed two strategic deals in the quarter: Plains' Canadian NGL business and the remaining 50% interest in KAPS, expanding Keyera's NGL and condensate connectivity and access to eastern and mid-continent markets.
- Record Segment Realized MarginsGathering & Processing delivered a new quarterly record realized margin of $128 million; Liquids Infrastructure delivered a new quarterly record realized margin of $222 million (results included contributions from the Plains assets and KAPS).
- Strong Corporate Earnings and Cash FlowAdjusted EBITDA (ex-transaction costs) of $309 million; distributable cash flow of $101 million (or $0.39/share); net earnings of $308 million for the quarter.
- Plains Contribution Above ExpectationsPlains' Canadian NGL business contributed incremental strength to Liquids Infrastructure (management cited ~ $78 million of incremental contribution in Q2) and is performing better than initial underwriting across pipelines, fractionation and Empress extraction cuts.
- Operational Execution and Project DeliveryKFS Frac 2 debottleneck placed into service in early June, more than one month ahead of schedule and 20% below original budget; other projects (KFS North, KFS Frac 3, KAPS Zone 4, ACE Rail Terminal) progressing on time and on budget.
- Dividend Increase and Capital DisciplineBoard approved a 4% annual dividend increase, reflecting confidence in cash flow and balance sheet while preserving financial flexibility for fee-based growth.
- Synergies and Integration ProgressDay‑1 synergies of $90 million realized; management targets total synergies of $120–$140 million and is identifying additional commercial, operating and G&A upside from integration.
- Confirmed Guidance and Growth Outlook2026 marketing realized margin guidance reaffirmed at $360–$390 million; fee‑based adjusted EBITDA per share CAGR targets of 16–18% (2025–2027) and 7–8% (2027–2029) underpinned by contracted projects, capacity fill, and synergy targets.
- Operational Recovery at AEF and Hedging PositionAEF facility restarted in early June and performing well with a renewed operating plan to maximize iso‑octane over a 4‑year cycle; management has layered hedges (including ~65% frac spread hedged for parts of 2027) to protect cash flow during integration and deleveraging.
MX:KEYEN Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Nov 10, 2026 | 2026 (Q3) | 6.64- | 4.97 | ― | ― |
| Aug 06, 2026 | 2026 (Q2) | 2.6515.99 | 7.39 | 116.36% (+8.60) | |
| May 14, 2026 | 2026 (Q1) | 1.18-7.12 | 7.66 | -192.98% (-14.79) | |
| Feb 12, 2026 | 2025 (Q4) | 5.775.24 | 5.24 | 0.00% (+0.00) | |
| Nov 14, 2025 | 2025 (Q3) | 6.884.97 | 10.89 | -54.32% (-5.91) | |
| Aug 07, 2025 | 2025 (Q2) | 5.007.39 | 8.33 | -11.29% (-0.94) | |
| May 15, 2025 | 2025 (Q1) | 6.997.66 | 4.17 | 83.87% (+3.49) | |
| Feb 13, 2025 | 2024 (Q4) | 6.565.24 | 2.82 | 85.71% (+2.42) | |
| Nov 14, 2024 | 2024 (Q3) | 7.7210.89 | 4.57 | 138.24% (+6.32) | |
| Aug 08, 2024 | 2024 (Q2) | 6.948.33 | 9.27 | -10.14% (-0.94) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
