


Mattr earnings date
Mattr (MTTRF) Q3 2026 Earnings Report
MTTRF Q3 2026 EPS Results
- Actual EPS
- $0.30
- Consensus EPS
- $0.28
- Beat/Miss
- Beat by +$0.02
- One Year Ago EPS
- $0.03
MTTRF Q3 2026 Revenue Results
- Actual Revenue
- $295.81M
- Expected Revenue
- $275.06M
- Beat/Miss
- Beat by +$20.75M
- YoY Revenue Growth
- +34.44%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 11/12/2026
- Time
- After Close
- Conference Call
- Thursday, November 12, 2026
Mattr's next earnings date is estimated for March 10, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q3 2026 Earnings Slide Deck
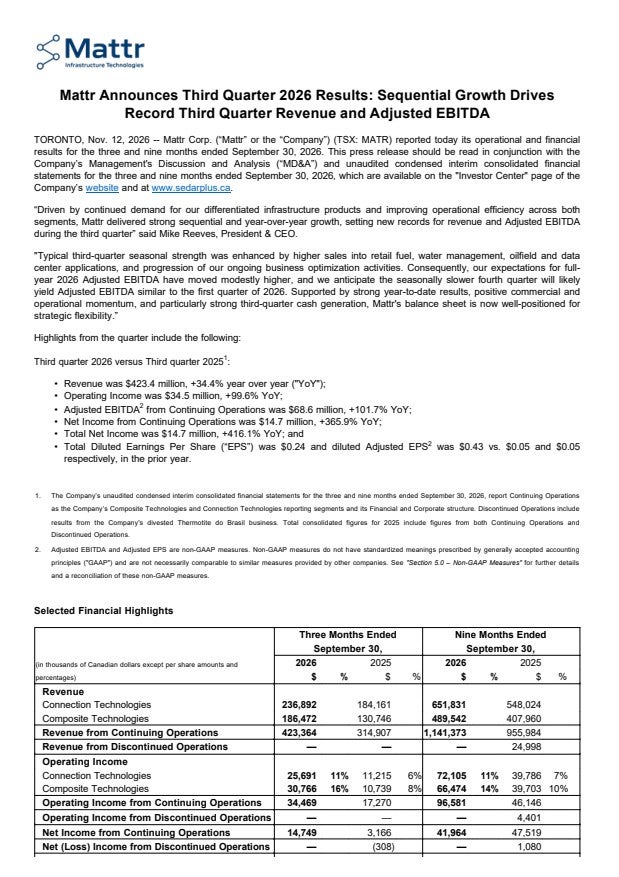
Q3 2026 Earnings Call Summary
The call was strongly positive, driven by record Q3 results, 34% year-over-year revenue growth, adjusted EBITDA more than doubling, strong performance across both operating segments, robust end-market demand, rising backlog, improved cash generation and debt reduction. The main challenges are the 50% Section 338 tariffs on certain Canadian-made products, a potential CAD 20 million 2027 adjusted EBITDA impact if tariffs remain, near-term AmerCable capacity constraints, seasonal Q4 and Q1 activity patterns, and uncertainty in the Middle East. Management emphasized that tariff exposure is being actively mitigated and maintained confidence in long-term growth, margin expansion and operational execution.
Management expects Q4 adjusted EBITDA will be similar to the first quarter of 2026, with full year 2026 adjusted EBITDA modestly above the outlook we provided last quarter; full year capital expenditures are expected to be between CAD 35 million and CAD 45 million, including approximately CAD 15 million for maintenance needs. If Section 338 tariffs are withdrawn in the near future, Mattr expects year-over-year adjusted EBITDA growth in 2027, while if no change in tariff policy occurs, the potential full year impact to 2027 adjusted EBITDA would be approximately CAD 20 million and adjusted EBITDA in 2027 would likely be similar to 2026. 2027 CapEx is expected to be modestly above Mattr's normal course annual run rate of CAD 40 million to CAD 50 million, while the company still believes it will hit its 70% conversion. Xerxes is expected to deliver 10% or more total output growth for at least the next 3 years, and potentially 4 to 5 years; Composite Technologies is expected to deliver margin growth, with the segment potentially moving into the low to mid-20s, while Connection Technologies in 2027 is likely to be in a similar range of margin than in 2026, excluding tariffs. AmerCable's expansion is expected to add approximately 25% to 30% to productive capacity, or likely CAD 100 million of revenue support on the low end, with perhaps half of that a run rate within 12 months and full capacity within 24 months.
- Record Third-Quarter ResultsMattr delivered record third-quarter results, with continuing operations revenue greater than CAD 400 million, increasing 34% year-over-year, while adjusted EBITDA more than doubled year-over-year.
- Strong Connection Technologies PerformanceConnection Technologies delivered strong growth in both revenue and adjusted EBITDA. Its Wire and Cable businesses benefited from higher shipping volumes and strong copper prices, with demand across mining, industrial, data center, infrastructure and oilfield applications.
- Strong Composite Technologies GrowthComposite Technologies revenue increased by more than 40% year-over-year and adjusted EBITDA more than doubled. The segment's performance was supported by higher production and shipping volumes, improved gross profit and absorption, and strong results from both Xerxes and Flexpipe.
- Record Xerxes PerformanceXerxes delivered record revenue and adjusted EBITDA, supported by rising production output, higher production and shipping volumes, progressively higher demand in fuel and water applications, and favorable customer and product mix.
- Flexpipe Growth and Large-Diameter Product AdoptionFlexpipe delivered strong performance, with North American and international activity rising, increased international deliveries, and early sales of newly introduced Large Diameter Products accelerating. The 8-inch products have been well received, with a substantial customer list placing orders or installing products, product performance exceeding expectations, and installation speed trending favorably.
- Improved Manufacturing Performance and Portfolio BenefitsManagement said the quarter demonstrated the benefits of Mattr's portfolio transformation, technology acceleration and manufacturing infrastructure investments, with stronger output, improved mix and higher margins across the business. The company also cited disciplined commercial choices and an attractive portfolio mix as contributors to higher-quality results.
- Strong Operating Cash Flow and Debt ReductionCash provided by operating activities from continuing operations was CAD 77.8 million in the quarter, driven by improved operational performance and a release of working capital. Strong cash generation allowed Mattr to pay down over CAD 40 million of debt during the quarter.
- Improved Balance Sheet FlexibilityAt quarter-end, net debt to adjusted EBITDA was 2.38x, or 1.61x excluding lease liabilities. Management said the balance sheet is now well positioned for strategic flexibility, with the credit facility below CAD 100 million.
- Capital Allocation Flexibility and Share RepurchasesMattr's capital allocation priorities remain focused on reinvesting in attractive organic opportunities, reducing debt, preserving flexibility for strategic growth and repurchasing shares opportunistically. The company bought back shares in Q3 and plans to continue buybacks in Q4, with prior guidance indicating low single-digit millions, potentially up to approximately CAD 5 million per quarter.
- Strong End-Market DemandManagement observed strong and sustainable customer demand across primary end markets. Mining trends are favorable, North American power generation and distribution investments continue to create opportunities across utility, nuclear and broader electrification applications, data center construction is driving incremental demand, and North American retail fuel and water management markets remain very active.
- Positive Oilfield and Flexpipe Sector OutlookOilfield activity remains generally stable, with elevated commodity prices driving modestly rising customer capital spending in most major U.S. basins. Management expects this trend to continue over the coming quarters, while technology-driven share gains from larger-diameter Flexpipe adoption support the sector outlook.
- Xerxes Demand, Market Expansion and Production GrowthDemand for Xerxes composite underground tanks remains strong across traditional end markets, while demand is rising in less traditional applications, including data center and other backup fuel and liquid storage use cases. Convenience store operators are accelerating new-to-industry construction, aging-tank replacement activity is rising, and water-management demand and market share are increasing.
- Xerxes Production Expansion and Margin OpportunityXerxes has elevated total tank production by greater than 10% over the last 12 months. Continued investments in manufacturing automation and efficiency are expected to enable similar annual production expansion in 2027 and beyond without adding facilities in new locations. Management expressed confidence in continued growth and margin expansion.
- Composite Technologies Margin Expansion OutlookComposite Technologies reported Q3 margins of 22.3%. Management expects year-over-year margin growth from 2026 to 2027, with the segment potentially exceeding 20% on a full-year basis in 2027 and moving into the low to mid-20s. Growth is expected to come from increased production, new technology and continued operational efficiency, particularly at Xerxes.
- Long-Term Xerxes Output Growth PotentialManagement expects Xerxes production growth of 10% or more for at least the next 3 years, and potentially 4 to 5 years, supported by prior investments, rising demand and continued operational efficiency improvements.
- Flexpipe Technology FunnelFlexpipe's 8-inch product family is expected to support continued revenue growth from 2026 to 2027, and productive output is being increased to meet demand. The high-temperature product is in final testing with a customer in the Middle East and is expected to reach commercial approval around the middle of 2027, potentially enabling sales in the second half of 2027. The applicable Middle East market spends more than CAD 1 billion annually on steel products addressing the relevant application.
- International Flexpipe ActivityInternational quoting activity is higher than it was 12 months ago, when it was at a cyclic low. Activity is elevated across several international markets, including Latin America, and management expects a good international year for Flexpipe in 2027, although it may not reach a peak level. Large international orders are not included in the company's outlook and would be incremental if received.
- High Order Backlog and VisibilityOrders in backlog are materially higher than they were 12 months ago and are nearly at the all-time high for the current portfolio. Management described visibility into roughly the first third of 2027 as reasonably good, with Xerxes having visibility into largely the full year of 2027.
- Tariff Mitigation and Manufacturing RepositioningMattr has largely offset existing tariff impacts through pricing actions and adjustments to sourcing and production. The company is actively repositioning production within its existing network, including using existing U.S. facilities in Ohio and Arkansas to manufacture affected products and redirecting Canadian capacity toward non-U.S. markets. The transition is expected to be substantially completed during 2027 without adding new facilities.
- AmerCable Capacity ExpansionInvestment is underway to materially expand AmerCable's capacity beginning in early 2028. Equipment scheduled for installation in late 2027 is expected to add approximately 25% to 30% to the facility's productive capacity, representing likely CAD 100 million of revenue support at the low end and potentially more over time depending on mix.
- Future Connection Technologies UpsideManagement said Connection Technologies remains below its ultimate margin potential. Further progress is expected from building critical mass in Shawflex, operational improvements in DSG, and increased AmerCable capacity as the business moves from 2027 into 2028.
- M&A PipelineManagement said its M&A pipeline is in a good place, with opportunities generally expected to be tuck-in acquisitions, primarily in the Connection Technologies segment, particularly Wire and Cable and DSG. The company also cited potential capacity expansion opportunities in Composites.
- Capital Investment and Cash Conversion TargetsMattr expects 2026 capital expenditures of CAD 35 million to CAD 45 million, including approximately CAD 15 million for maintenance needs. Management described the normal annual capital expenditure run rate as CAD 40 million to CAD 50 million and expects 2027 capital spending to be slightly elevated while still targeting 70% cash flow conversion.
MTTRF Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Mar 10, 2027 | 2026 (Q4) | 0.12- | 0.03 | ― | ― |
| Nov 12, 2026 | 2026 (Q3) | 0.280.30 | 0.03 | 760.00% (+0.27) | |
| Aug 12, 2026 | 2026 (Q2) | 0.270.27 | 0.08 | 225.00% (+0.19) | |
| May 13, 2026 | 2026 (Q1) | 0.040.08 | 0.24 | -67.65% (-0.16) | |
| Mar 12, 2026 | 2025 (Q4) | -0.020.03 | -0.01 | 300.00% (+0.04) | |
| Nov 12, 2025 | 2025 (Q3) | 0.090.03 | 0.16 | -78.26% (-0.13) | |
| Aug 13, 2025 | 2025 (Q2) | 0.090.08 | 0.22 | -61.29% (-0.13) | |
| May 14, 2025 | 2025 (Q1) | 0.110.24 | 0.11 | 112.50% (+0.13) | |
| Mar 13, 2025 | 2024 (Q4) | -0.05-0.01 | 0.02 | -157.14% (-0.04) | |
| Nov 13, 2024 | 2024 (Q3) | 0.140.16 | 0.79 | -79.65% (-0.63) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
