

MDA Space Ltd (MDA) Q2 2026 Earnings Report
MDA Q2 2026 EPS Results
- Actual EPS
- $0.26
- Consensus EPS
- $0.25
- Beat/Miss
- Beat by +$0.01
- One Year Ago EPS
- $0.27
MDA Q2 2026 Revenue Results
- Actual Revenue
- $356.79M
- Expected Revenue
- $320.66M
- Beat/Miss
- Beat by +$36.13M
- YoY Revenue Growth
- +33.57%
Earnings Announcement Details
- Quarter
- Q2 2026
- Date
- 08/07/2026
- Time
- Before Open
- Conference Call
- Friday, August 7, 2026
MDA Space Ltd's next earnings date is estimated for November 5, 2026, based on past reporting schedules.
Q2 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q2 2026 Earnings Slide Deck
Q2 2026 Earnings Call Summary
The call conveys a strongly positive operational and strategic momentum: high revenue growth (Q2 +34% YoY), raised guidance, robust bookings (book-to-bill 1.6x), major contract wins (Telesat expansion, CSA RADARSAT, others), and transformational M&A (BCT, CLS) that materially expand capabilities and pro forma scale. Near-term financial headwinds include working-capital-driven negative operating cash flow and free cash flow, higher CapEx, dilution from equity issuance and acquisition-related financing/leverage risks. Management emphasizes disciplined financing, conservative leverage targets, and continued organic growth, while acknowledging near-term cash impacts. On balance, the call highlights significant growth and strategic advances while flagging manageable near-term cash and execution risks.
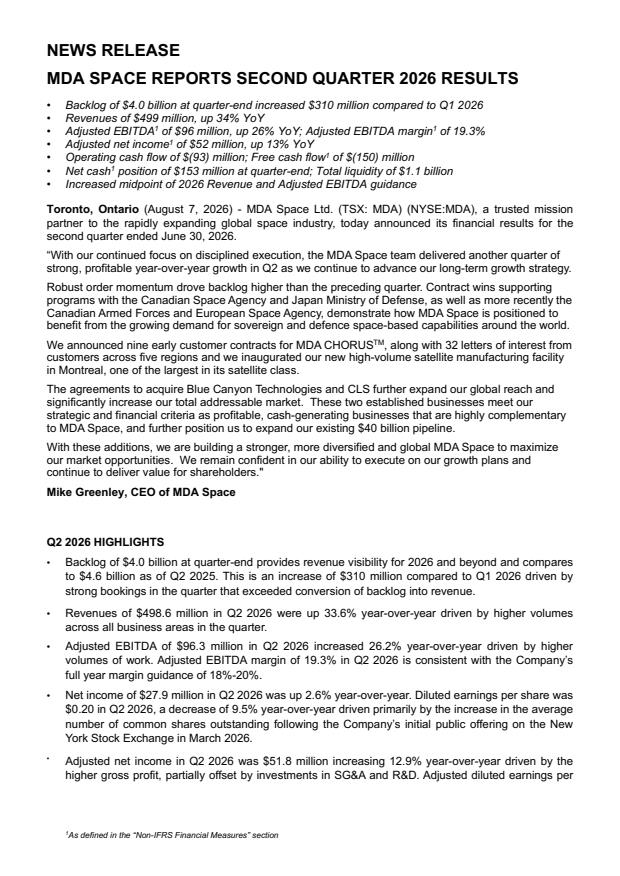
MDA updated 2026 guidance to revenue of $1.8–$1.9 billion (midpoint $1.85B, ~13% y/y at midpoint) and adjusted EBITDA of $330–$370M (midpoint $350M, ~8% y/y), with an unchanged adjusted EBITDA margin target of 18–20% and CapEx guidance of $225–$275M; free cash flow is expected to be neutral-to-negative. For context, Q2 revenue was $499M (+34% y/y) with adjusted EBITDA $96M (19.3% margin), H1 revenue was $963M (+33% y/y) with H1 adjusted EBITDA $187M (19.4% margin), Q2 adjusted net income was $52M and adjusted diluted EPS $0.36. Backlog was $4.0B (Q2 net bookings >$800M, book-to-bill 1.6x) — pro forma backlog would be $4.4B after the ~ $400M Telesat expansion — and the opportunity pipeline is ~$40B (including ~$10B down-selected follow‑ons). H1 CapEx was $145M (vs $98M LY); operating cash flow H1 was negative $33M (vs +$320M LY) and free cash flow negative $178M (vs +$222M LY). Balance sheet and financing: net cash $153M at quarter end, total liquidity ~$1.1B (~$400M cash + ~$700M credit); management completed ~$1.75B financing (23M‑share bought deal raising $1.15B and $600M senior notes) toward two acquisitions (total ~ $2B cost), which would lift pro forma 2026 revenue to ~$2.5B and, management said, support roughly ~50% growth into 2027 while targeting pro forma leverage of 1.5x–2.5x net debt to LTM adjusted EBITDA.
- Strong Revenue and Profit GrowthQ2 revenue of $499M, up 34% YoY; first half revenue $963M, up 33% YoY. Q2 adjusted EBITDA $96M, up 26% YoY, with adjusted EBITDA margin of 19.3%. First half adjusted EBITDA $187M with a 19.4% margin.
- Raised Full-Year GuidanceRaised midpoint of 2026 guidance to $1.85B revenue and $350M adjusted EBITDA. Updated full-year revenue range $1.8B–$1.9B (midpoint implying ~13% YoY growth) and adjusted EBITDA $330M–$370M (midpoint implying ~8% YoY growth).
- Robust Bookings, Backlog and Book-to-BillQ2 net order bookings exceeded $800M, book-to-bill of 1.6x. Ending backlog $4.0B (up ~$300M QoQ); Telesat Lightspeed scope expansion added ~225 satellites and increased contract value by ~$474M (pro forma backlog ~$4.4B).
- Broad-Based Segment Momentum and Major Contract WinsSatellite Systems revenue $336M (+44% YoY) driven by Telesat Lightspeed; Robotics & Space Operations $100M (+13%) driven by Canadarm3 activity; GeoIntelligence $63M (+20%) on new programs. Significant awards include a CSA SAR follow-on >$600M, Telesat expansion (~$474M), Mitsubishi Electric (Japan MoD payloads), BAE Systems MEO EPOCH 2 payload work and an OHB lunar landing sensors pre-auth.
- Strategic M&A to Expand Capabilities and GeographyAgreed acquisitions: Blue Canyon Technologies (adds ~ $225M revenue) and majority interest in CLS (adds ~ $465M revenue). Pro forma 2026 revenue with both would be ~$2.5B. Acquisition strategy verticalizes capabilities (e.g., GN&C, geointelligence) and expands U.S. and European presence.
- Operational & Technology Investments Driving Future GrowthOpened a new high-volume Montreal satellite manufacturing facility (doubled floor space). MDA CHORUS integration complete and targeted for launch later in the year. Advancing on-orbit compute, SatixFy-derived space-grade chips, and enterprise AI (Chat MDA deployed to ~4,000 employees). CLS brings substantial compute and data assets (command center ~900 servers).
MDA Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Nov 05, 2026 | 2026 (Q3) | 0.21- | 0.25 | ― | ― |
| Aug 07, 2026 | 2026 (Q2) | 0.250.26 | 0.27 | -5.26% (-0.01) | |
| May 07, 2026 | 2026 (Q1) | 0.230.27 | 0.21 | 31.03% (+0.06) | |
| Mar 04, 2026 | 2025 (Q4) | 0.280.32 | 0.2 | 60.71% (+0.12) | |
| Nov 14, 2025 | 2025 (Q3) | 0.240.25 | 0.2 | 25.00% (+0.05) | |
| Aug 07, 2025 | 2025 (Q2) | 0.210.27 | 0.14 | 100.00% (+0.14) | |
| May 08, 2025 | 2025 (Q1) | 0.180.21 | 0.11 | 93.33% (+0.10) | |
| Mar 07, 2025 | 2024 (Q4) | 0.190.20 | 0.16 | 21.74% (+0.04) | |
| Nov 15, 2024 | 2024 (Q3) | 0.150.20 | 0.06 | 250.00% (+0.14) | |
| Aug 08, 2024 | 2024 (Q2) | 0.090.14 | 0.06 | 137.50% (+0.08) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
