

Intermap Technology (ITMSF) Q2 2026 Earnings Report
ITMSF Q2 2026 EPS Results
- Actual EPS
- -$0.03
- Consensus EPS
- ―
- Beat/Miss
- ―
- One Year Ago EPS
- -$0.01
ITMSF Q2 2026 Revenue Results
- Actual Revenue
- $1.93M
- Expected Revenue
- ―
- Beat/Miss
- ―
- YoY Revenue Growth
- -35.60%
Earnings Announcement Details
- Quarter
- Q2 2026
- Date
- 08/13/2026
- Time
- After Close
- Conference Call
- Thursday, August 13, 2026
Intermap Technology's next earnings date is estimated for November 17, 2026, based on past reporting schedules.
Q2 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q2 2026 Earnings Slide Deck
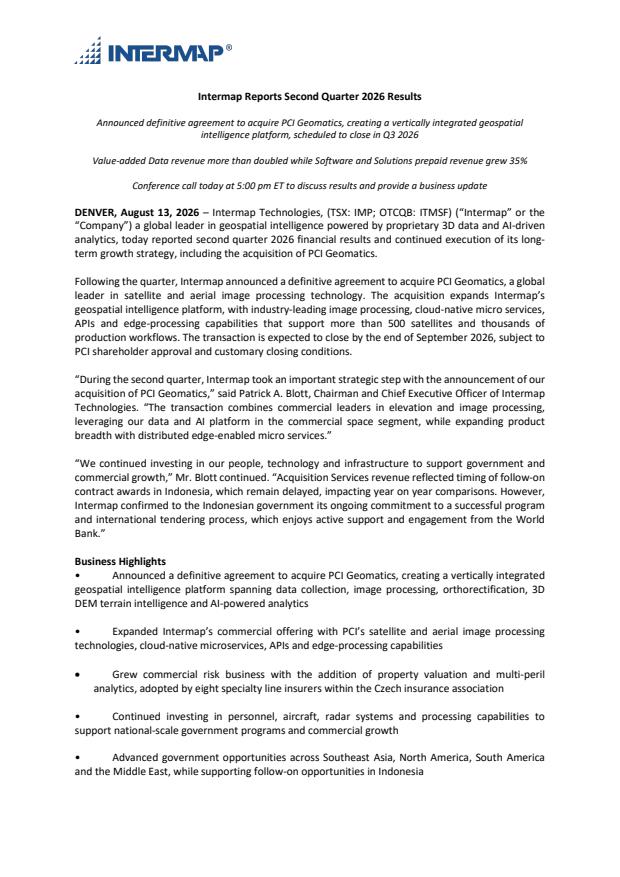
Q2 2026 Earnings Call Summary
The call presents a balanced mix of strategic progress and near-term financial weakness. Highlights include a transformative acquisition (PCI Geomatics) that expands capabilities and recurring revenue potential, strong growth in value-added data and AI-driven products, defense contract wins, and continued investment in platform capacity with a modest cash runway ($16.2M). Lowlights center on significant revenue declines (Q2 down ~33% and H1 down ~53%), a widened net loss and negative adjusted EBITDA, the absence of acquisition services revenue due to Indonesia procurement delays, and dependency on the timing/outcome of the Indonesian follow-on award and the PCI close—both material near-term variables. Given the meaningful strategic positives that could drive long-term upside but material short-term operational and timing risks that have depressed results, the overall tone is cautiously optimistic but uncertain.
Management reiterated guidance for double‑digit commercial revenue growth and said the company’s prior $30.0M target would likely be conservative if Indonesia awards this year and Intermap wins, but timing of that award is the principal near‑term variable and guidance will be updated after the PCI Geomatics close; PCI is expected to close by end‑September with CAD 11.0M cash at closing. For context, Q2 revenue was $2.0M and revenue for the first six months was $3.4M, with Software & Solutions at $1.3M (software prepaid up 35%), Value‑added Data $0.7M (vs $0.3M prior year), Acquisition Services $0 (vs $1.4M prior), net loss $2.1M ($0.03/share), adjusted EBITDA -$1.4M, cash $16.2M, working capital $12.6M, and contract liabilities $3.5M (≈88% relates to prepaid software/license revenue).
- Strategic Acquisition of PCI GeomaticsDefinitive agreement to acquire PCI Geomatics for CAD 11 million in cash, expected to close by end of September (subject to shareholder approval). Transaction adds image processing, cloud-native microservices, APIs and edge processing capabilities; company expects material recurring subscription revenue and positive net cash flow from the combined business.
- Commercial Revenue and Product AdoptionCommercial business performing better than expected with guidance for double-digit commercial growth. Software & Solutions revenue remained steady at $1.3M for the quarter and software prepaid contracts grew 35% year-over-year, driven by adoption of new AI-driven products, including insurance subscriptions with an agentic AI risk assistant.
- Value-Added Data GrowthValue-added Data revenue increased to $700,000 from $300,000 year-over-year, a more than 133% increase (more than doubled), reflecting strong organic growth and uptake of analytics products.
- Defense and Strategic Technology WinsAwarded third Fast Track strategic technology research contract through a leading defense prime supporting U.S. research on position, navigation and timing in GPS-denied environments; DARPA contract converted and continued engagement with other U.S. government programs, validating geospatial-to-intelligence strategy.
- Investment in Platform and CapacityInvested $2.2M in property and equipment during first six months vs $0.2M prior-year period to support platform, sensors, data archive and processing capabilities (11x year-over-year increase), demonstrating capital deployment toward growth and integration readiness for PCI.
- Liquidity and Balance Sheet ResourcesEnded the quarter with $16.2M in cash, $12.6M in working capital and $17.7M in shareholders' equity, and management indicates the PCI acquisition and integration plan is underwritten without relying on near-term Indonesia receipts.
- Potential Upside from Indonesia Follow-onManagement states Indonesia follow-on awards remain active; if awards occur this year and Intermap wins, the current company guidance of $30M for 2026 could be conservative—representing meaningful upside contingent on award timing and outcome.
ITMSF Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Nov 17, 2026 | 2026 (Q3) | ―- | -0.02 | ― | ― |
| Aug 13, 2026 | 2026 (Q2) | ―-0.03 | -0.01 | -200.00% (-0.02) | |
| May 13, 2026 | 2026 (Q1) | ―-0.04 | -0.02 | -100.00% (-0.02) | |
| Mar 31, 2026 | 2025 (Q4) | 0.00-0.04 | -0.02 | -100.00% (-0.02) | |
| Nov 13, 2025 | 2025 (Q3) | 0.01-0.02 | 0.03 | -164.52% (-0.05) | |
| Aug 14, 2025 | 2025 (Q2) | -0.01-0.01 | 0.02 | -150.00% (-0.03) | |
| May 15, 2025 | 2025 (Q1) | 0.01-0.02 | -0.03 | 25.93% (+0.01) | |
| Mar 27, 2025 | 2024 (Q4) | 0.030.03 | -0.03 | 193.75% (+0.06) | |
| Nov 14, 2024 | 2024 (Q3) | ―0.02 | -0.02 | 203.33% (+0.04) | |
| Aug 14, 2024 | 2024 (Q2) | ―0.01 | -0.03 | 152.63% (+0.04) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
