

Firan Tech (FTGFF) Q3 2026 Earnings Report
FTGFF Q3 2026 EPS Results
- Actual EPS
- $0.29
- Consensus EPS
- $0.13
- Beat/Miss
- Beat by +$0.16
- One Year Ago EPS
- $0.09
FTGFF Q3 2026 Revenue Results
- Actual Revenue
- $45.93M
- Expected Revenue
- $37.20M
- Beat/Miss
- Beat by +$8.73M
- YoY Revenue Growth
- +34.16%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 10/07/2026
- Time
- After Close
- Conference Call
- Wednesday, October 7, 2026
Firan Tech's next earnings date is estimated for February 10, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q3 2026 Earnings Slide Deck
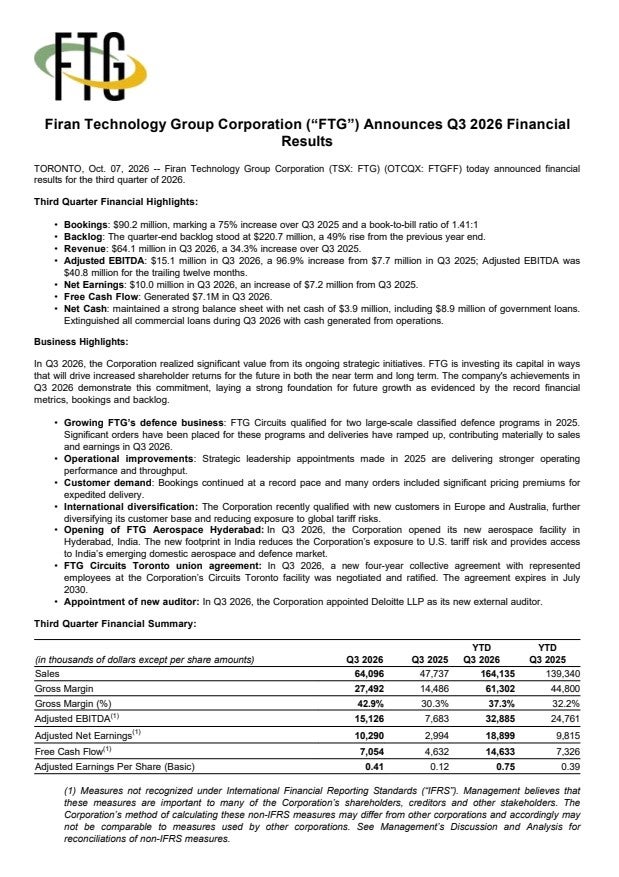
Q3 2026 Earnings Call Summary
The call was strongly positive, led by record bookings, revenue, backlog, margins, EBITDA, earnings, free cash flow, and a move to net cash. Demand across aerospace and defense remains strong, classified defense programs are ramping, and international diversification and new product initiatives are progressing. The principal cautions were tariff- and AI-driven input cost increases, short-term visibility on expedited pricing, equipment and order-timing delays, higher working-capital and investment requirements, customer concentration, and execution challenges associated with the pace of growth.
FTG expects CapEx to be closer to FTG's long-term target of 3% of revenue, though as it adds production capacity in Canada, the U.S., and India, this rate may tick higher to 4% or 5% in the next couple of quarters; approximately 84.8% of the record $221 million backlog is expected to be converted to revenue through Q3 2027 or in the next 12 months, the two classified defense programs will ramp through next year and then sustain for some number of years after that, with management saying “by the end of next year” is fair for reaching run rate, and each has $50 million-$100 million annual potential; Hyderabad is expected to have no real incremental benefit to FTG before 2027, is expected to be certified to key aerospace standards by the end of this year, and first shipments of the Edge+ WQAR manufactured at FTG should happen in Q4 this year, while the first SATCOM radio shipment from Chatsworth is expected in Q4 this year and further WestJet WVSS-II installations are expected through the balance of this year.
- Record Third-Quarter ResultsFTG reported record revenues, earnings, bookings, and backlog in Q3 2026, supported by continued strong end-market demand. Bookings were $90 million, up 75% versus Q3 2025, with a 1.41:1 book-to-bill ratio. Revenue was $64 million, up 34.3%, adjusted EBITDA was $15.1 million, up 97% from $7.5 million, net earnings were $10 million, and free cash flow was positive $7.1 million.
- Record Backlog and Strong Revenue VisibilityQuarter-end backlog was $221 million, up 49% from 2025 year-end. Approximately 84.8% of the backlog is expected to convert to revenue through Q3 2027, or in the next 12 months.
- Improved Gross Margin and ProfitabilityGross margin increased to $27.5 million, or 42.9% of sales, from $14.5 million, or 30.3%, in Q3 2025. The improvement was attributed to top-line growth, improved profitability at Aero Calgary and several U.S. sites, increased throughput, limited added resources, and pricing premiums for quick-turnaround deliveries.
- Strong Adjusted EBITDA and Net Earnings GrowthAdjusted EBITDA was $15.1 million, or 23.6% of sales, compared with $7.7 million, or 16.1%, in Q3 2025. Net earnings were $10 million, or $0.39 per diluted share, compared with $2.8 million, or $0.11 per diluted share. The earnings comparison benefited from a 12% tax rate in Q3 2026 versus 30% in Q3 2025.
- Debt Repayment and Positive Net CashFTG repaid all interest-bearing bank debt in Q3 and ended the quarter with net cash of $3.9 million, compared with net debt of $2.9 million in Q2 2026 and $8.1 million at 2025 year-end. Primary liquidity totaled $94 million, consisting of $66 million of working capital and $28 million of unused credit facilities.
- Defense Program Orders and Ramp-UpFTG received significant orders and began ramping deliveries for two large-scale classified defense programs qualified in 2025. The programs contributed materially to Q3 sales and earnings, represented an estimated 10% of quarterly revenue, are both multi-year programs, and are expected to ramp through next year before sustaining for several years.
- Strong Circuits Segment PerformanceCircuits sales were $45.1 million in Q3, up 40% from Q3 2025. Minnetonka and Fredericksburg each increased sales by between 75% and 80%, while the Minnetonka site achieved the highest sales in its history in Q3.
- Aerospace Segment Growth and Product ProgressAerospace sales increased 18% to $19.8 million in Q3. Aero Calgary again delivered profitable results, supported by licensing revenue, hardware sales, product certification, and weather-data revenue. The company also certified and shipped the first WVSS weather sensors and obtained its first STC to install WVSS-II on a Boeing 737 MAX 8.
- Aero Calgary Revenue Plan AdvancingLicensing revenue for the SATCOM radio returned and is expected to be consistent year to year. FTG is now confirmed as the manufacturer for the licensee and expects to capture additional margin. First shipments manufactured in Chatsworth are expected in Q4 2026, while Edge+ WQAR production in Tianjin is also expected to begin shipping in Q4.
- Recurring Weather Data Revenue OpportunityThe first WVSS-II unit was installed on a WestJet aircraft, with further installations expected through the balance of the year. Each approved and installed unit provides a recurring revenue stream from real-time weather and water-vapor readings supplied to NOAA.
- International Diversification ProgressSales in Canada increased 61% year over year in Q3, while sales to Asia increased 40%, supported by C919 shipments and other activity. FTG qualified new customers in Europe and Australia, and sales outside the U.S. are being expanded to reduce exposure to U.S. tariff risks.
- Hyderabad Facility OpenedFTG opened its aerospace facility in Hyderabad, India, during Q3. The facility is intended to add capacity, support Western customers, and provide access to Indian aerospace and defense markets. FTG expects to complete certification to key aerospace standards by year-end and begin shipping to external customers thereafter.
- Operational Improvements Across SitesStrategic leadership appointments made at several sites contributed to stronger operating performance and throughput. Fredericksburg and Chatsworth achieved 30% to 100% revenue increases without adding headcount, while Minnetonka added approximately 25 to 30 employees, improved retention, and reduced turnover.
- Pricing Premiums for Expedited DeliveryMany Q3 orders included price increases and significant price premiums for quick delivery. The two classified defense programs drove significant expedite fees, and all FTG Circuits plants were able to provide the high-margin quick-turnaround service during the quarter.
- Commercial Aerospace Market TailwindsManagement cited strong market demand, including Airbus targeting 870 aircraft deliveries in 2026, about 10% above the prior year, with a backlog of over 8,000 orders. Boeing had a backlog of about 6,000 planes and plans to increase 737 deliveries from 42 to 47 per month and 787 deliveries from eight to 10 per month. Bell Helicopters reported a 12% increase in deliveries in its latest quarter.
- Defense Market Expansion OpportunitiesFTG is pursuing additional defense programs in Canada, the U.S., NATO countries, and India. Management cited a U.S. budget request for a 45% increase in spending to about $1.45 trillion and new NATO commitments to reach 3.5% of GDP for defense plus another 1.5% for defense infrastructure.
- FLYHT Integration and Tax-Loss PotentialFTG legally amalgamated FLYHT into FTG Aerospace Calgary and renamed the business. The amalgamation may enable FTG to use FLYHT tax losses beyond the Calgary operation, although management stated there is no certainty this will be possible. FTG continues to have substantial U.S. and Canadian tax losses available to offset future income.
- Growth Capacity and Corporate Development OptionsIf Q3 revenue is annualized, FTG's run rate is over $250 million. Management said the company is not capacity constrained overall and can add people at many sites. FTG is evaluating acquisitions and greenfield construction opportunities, including a possible European footprint, increased India Circuits presence, and additional technology.
- Union Agreement RatifiedThe FTG Circuits Toronto union agreement was completed and ratified as a new four-year agreement. Management stated that the wage increases are fair and will not impact the site's profitability.
FTGFF Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Feb 10, 2027 | 2026 (Q4) | 0.21- | 0.1 | ― | ― |
| Oct 07, 2026 | 2026 (Q3) | 0.130.29 | 0.09 | 241.67% (+0.21) | |
| Jul 08, 2026 | 2026 (Q2) | 0.120.14 | 0.1 | 42.14% (+0.04) | |
| Apr 08, 2026 | 2026 (Q1) | 0.070.10 | 0.09 | 6.15% (+0.01) | |
| Feb 18, 2026 | 2025 (Q4) | 0.090.10 | 0.11 | -12.50% (-0.01) | |
| Oct 08, 2025 | 2025 (Q3) | 0.080.09 | 0.08 | 9.09% (+0.01) | |
| Jul 08, 2025 | 2025 (Q2) | 0.080.10 | 0.08 | 27.27% (+0.02) | |
| Apr 09, 2025 | 2025 (Q1) | 0.020.09 | 0.03 | 225.00% (+0.06) | |
| Feb 19, 2025 | 2024 (Q4) | 0.070.11 | 0.07 | 60.00% (+0.04) | |
| Oct 09, 2024 | 2024 (Q3) | 0.060.08 | 0.04 | 83.33% (+0.04) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
