

Want to see FBIO full AI Analyst Report?
Fortress Biotech (FBIO) Q2 2026 Earnings Report
FBIO Q2 2026 EPS Results
- Actual EPS
- -$0.08
- Consensus EPS
- -$0.20
- Beat/Miss
- Beat by +$0.12
- One Year Ago EPS
- $0.45
FBIO Q2 2026 Revenue Results
- Actual Revenue
- $18.72M
- Expected Revenue
- $18.30M
- Beat/Miss
- Beat by +$418.00K
- YoY Revenue Growth
- +14.04%
Earnings Announcement Details
- Quarter
- Q2 2026
- Date
- 05/14/2026
- Time
- After Close
- Conference Call
- Thursday, May 14, 2026
Fortress Biotech's next earnings date is estimated for November 16, 2026, based on past reporting schedules.
Q2 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q2 2026 Earnings Slide Deck
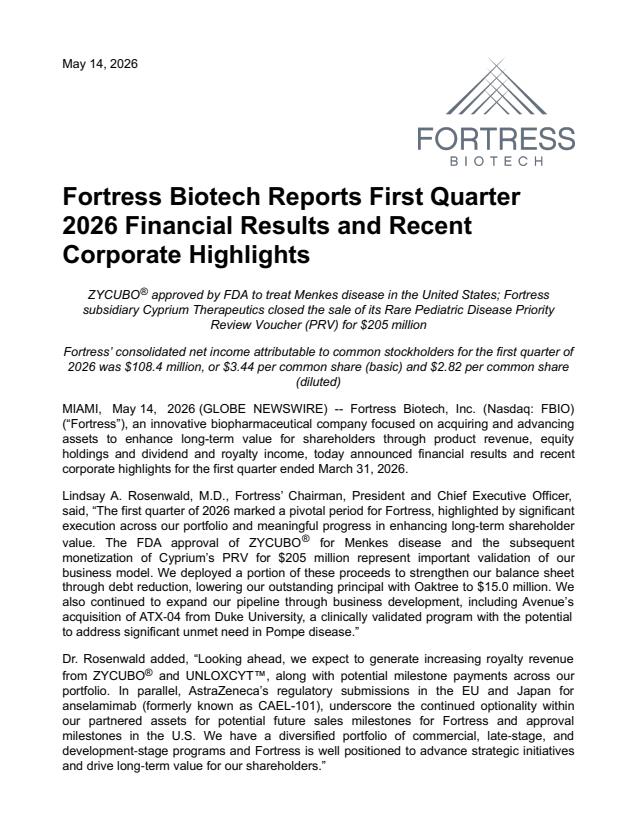
Q2 2026 Earnings Call Summary
The call conveyed clear commercial momentum for Emrosi — strong revenue growth (+23% YoY total revenue), accelerating prescriptions (20% sequential growth to ~36k in Q2), rising prescriber counts (>4,500, >40% increase from end-2025), improving ASP and formulary progress, and a meaningful move to positive EBITDA and adjusted EBITDA. These positives outweigh the remaining challenges: payer friction (only ~38% high-quality coverage), some softness in QBREXZA, refill dynamics still maturing, and the time required to monetize international opportunities. Management signaled measured investment in marketing and added sales capacity to sustain growth. Overall, the trajectory appears constructive with manageable risks.
Management reiterated that 2026 should be a "breakout year" for revenue growth and profitability, expecting continued ASP improvement and expanding payer coverage (quality formulary coverage rose from 34% in Q1 to ~38% currently, and GPO agreements give plan access to ~169M of 192M commercial lives); they reported Q2 total revenue of $18.5M (up 23% YoY from $15M) with Emrosi net revenue of $8.1M, gross margin of 67%, SG&A of $10.9M (down from $11.9M), GAAP net loss narrowed to $0.3M ($0.01/sh), positive EBITDA of $1.4M in Q2 ($1.1M for the six months) and adjusted EBITDA of $2.9M in Q2 ($3.5M YTD), ending the quarter with $25.6M cash, and said they expect to remain EBITDA‑positive for the remainder of the year and to become sustainably earnings‑ and cash‑flow‑positive; operationally they expect continued Emrosi prescription momentum (Q2 ~36,000 scripts vs ~30,000 in Q1, ~20% sequential growth; June ~13K and July ~14K monthly scripts; NRx ~5,300 in June vs a prior 3‑month average of ~4,700; >4,500 unique prescribers vs 3,200 at end‑2025, >40% growth), contributions from five new dermatology reps deployed in late July, and support from the late‑Q2 launch of Eurax cream to drive further ASP, revenue and payer traction through Q3/Q4 and into 2028.
- Total Revenue GrowthTotal revenue for Q2 2026 was $18.5M, up 23% year-over-year from $15.0M in Q2 2025, driven primarily by Emrosi commercial momentum.
- Emrosi Revenue and Prescription MomentumEmrosi generated $8.1M in net revenue in Q2 2026. Emrosi prescriptions totaled ~36,000 in Q2 (vs ~30,000 in Q1), representing ~20% sequential quarterly growth; June saw an all-time monthly high with ~5,300 new prescriptions (vs a prior 3-month average of ~4,700 NRx).
- Prescriber ExpansionUnique dermatology prescribers writing Emrosi surpassed 4,500, an increase of more than 40% from ~3,200 at the end of 2025 and up substantially from ~3,700 at the end of Q1 2026, indicating accelerating adoption among dermatologists.
- Improving ASP and Payer Access ProgressCalculated average selling price (ASP) for Emrosi increased in Q2 vs Q1 (analyst commentary referenced ~10% boost Q2 over Q1); high-quality formulary coverage (single-step or better) improved from 34% in Q1 to ~38% currently. Agreements with the top 3 GPOs provide plan access to over 169M of 192M covered commercial lives (~88%).
- Profitability and MarginsGross margin was 67% in Q2 2026, consistent with prior year. GAAP net loss narrowed to $0.3M ($0.01/share) in Q2 2026 from a $3.8M loss ($0.16/share) in Q2 2025. Company generated positive EBITDA of $1.4M in Q2 and positive adjusted EBITDA of $2.9M for the quarter.
- Expense Discipline and SG&A TrendsOperating expenses increased by less than 1% year-over-year per management; SG&A declined to $10.9M in Q2 2026 from $11.9M in Q2 2025 (approximately an 8.4% decrease year-over-year), demonstrating operating leverage while growing revenues.
- Cash PositionCash balance ended Q2 at $25.6M versus $24.1M at December 31, 2025, an increase of $1.5M (~6.2%), supporting near-term operations.
- Commercial Expansion and New Product LaunchCompany hired and deployed 5 additional dermatology sales professionals in late July to expand field coverage. Launched a niche dermatology product, Eurax Cream (10% crotamiton), in July to augment the portfolio (Emrosi remains the primary focus).
- International / BD OptionalityManagement is pursuing out‑licensing opportunities for Emrosi and other patented brands ex‑U.S.; company retains global patent portfolio and has existing out‑licenses (e.g., QBREXZA in Japan and other Asia markets, AMZEEQ in China), indicating potential future revenue streams outside the U.S.
FBIO Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Nov 16, 2026 | 2026 (Q3) | -0.27- | 0.11 | ― | ― |
| May 14, 2026 | 2026 (Q1) | ―2.82 | -0.48 | 687.50% (+3.30) | |
| May 14, 2026 | 2026 (Q2) | -0.20-0.08 | 0.45 | -117.78% (-0.53) | |
| Mar 31, 2026 | 2025 (Q4) | -0.222.82 | -0.48 | 687.50% (+3.30) | |
| Nov 14, 2025 | 2025 (Q3) | -0.420.11 | -0.76 | 114.47% (+0.87) | |
| Aug 14, 2025 | 2025 (Q2) | -0.360.45 | -0.73 | 161.64% (+1.18) | |
| May 15, 2025 | 2025 (Q1) | ―- | -1.03 | ― | |
| Mar 31, 2025 | 2024 (Q4) | -0.49-0.48 | -1.03 | 53.40% (+0.55) | |
| Nov 14, 2024 | 2024 (Q3) | -0.59-0.76 | -0.94 | 19.15% (+0.18) | |
| Aug 13, 2024 | 2024 (Q2) | -1.22-0.73 | -3.6 | 79.72% (+2.87) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
