


WELL Health Technologies Corp earnings date
WELL Health Technologies Corp (W7V) Q3 2026 Earnings Report
DE:W7V Q3 2026 EPS Results
- Actual EPS
- EUR 0.07
- Consensus EPS
- EUR 0.04
- Beat/Miss
- Beat by +EUR 0.03
- One Year Ago EPS
- EUR 0.10
DE:W7V Q3 2026 Revenue Results
- Actual Revenue
- EUR 259.01M
- Expected Revenue
- EUR 259.69M
- Beat/Miss
- Missed by -EUR 680.90K
- YoY Revenue Growth
- +11.74%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 11/09/2026
- Time
- After Close
- Conference Call
- Monday, November 9, 2026
WELL Health Technologies Corp's next earnings date is estimated for March 25, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q3 2026 Earnings Slide Deck
Q3 2026 Earnings Call Summary
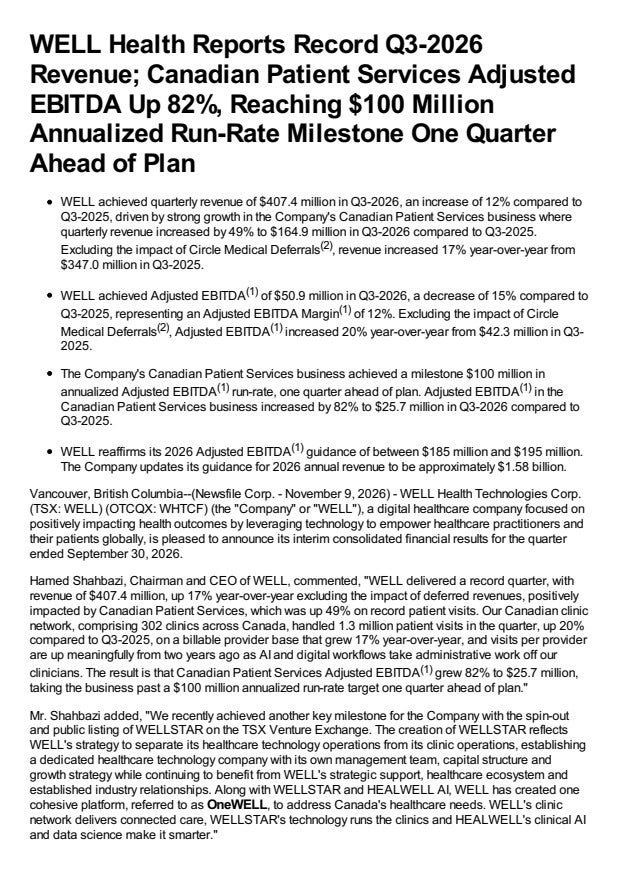
The call was predominantly positive. Strong normalized growth, record Canadian clinic performance, an ahead-of-schedule $100 million EBITDA run-rate milestone, balance-sheet improvements and reaffirmed profitability guidance outweighed the reported earnings declines, lower shareholder free cash flow, impairments and challenges in selected U.S. businesses. Management remained focused on Canadian clinics, higher-margin operations and future public sector opportunities.
WELL updated 2026 guidance to revenue of approximately $1.58 billion, representing 16% normalized growth from 2025, excluding Circle Medical and CRH Medical Corporation related onetime events from both fiscal year 2026 and 2025, and adjusted EBITDA of $185 million to $195 million, representing normalized growth of 13% to 19%; guidance reflects only acquisitions announced to date, and as of September 30, 2026, all of the $17.6 million in Circle Medical deferrals contemplated in that guidance had been recognized. WELL expects to continue its multiyear trend of delivering better than 10% annual growth in adjusted EBITDA, inclusive of acquisitions and organic growth and excluding any divestitures, targets $1 billion in revenue run rate for WELL Canada by the end of 2028, and is pursuing public-sector opportunities representing well over $100 million in contract value, which are pipeline opportunities under active pursuit, not contracted revenue. Management said SMO businesses tend to be in excess of 20% operating margin, can be even higher than that, and its long-term goal for clinics and research altogether is to exceed 20% operating margins for the entire network.
- Normalized EBITDA GrowthQ3 normalized adjusted EBITDA increased 20% year-over-year to $50.9 million, while normalized revenue increased 17% to $407.4 million. Adjusted EBITDA grew faster than revenue, reflecting a continued shift toward higher-margin businesses.
- Canadian Clinics Reached $100 Million EBITDA Run RateWELL's Canadian clinics achieved a $100 million annualized adjusted EBITDA run rate, reaching the target one quarter ahead of schedule.
- Canadian Clinics Delivered Strong Revenue and EBITDA GrowthCanadian clinic revenue increased 49% year-over-year to $164.9 million, including 12% same-clinic sales growth. Adjusted EBITDA increased 82% to $25.7 million, and adjusted EBITDA margin expanded approximately 280 basis points to 15.6%.
- Canadian Clinics Sustained Long-Term GrowthSince 2021, Canadian clinics revenue has grown at a 47% compound annual growth rate and adjusted EBITDA has grown at a 44% compound annual growth rate through acquisitions, organic growth and the clinic transformation program.
- Expanded Canadian Clinic NetworkAs of September 30, WELL operated 302 clinics across 179 physical facilities, compared with 128 clinics at the start of 2022. The network included more than 3,400 providers, including more than 1,500 physicians.
- Higher Canadian Patient Volumes and Provider ProductivityCanadian patient visits reached 1.3 million in Q3, up 20% year-over-year, including 6% organic growth consisting of 1.9% same-clinic growth and 4.1% growth from absorptions. Billable providers increased 17% year-over-year to 2,400, while visits per billable provider increased 3% year-over-year to approximately 534.
- Broad North American Clinical ScaleThe U.S. network included more than 1,500 providers, including more than 500 physicians. U.S. patient services were approximately 665,000, up 1% quarter-over-quarter and 4% organically. Combined across Canada and the U.S., WELL had almost 5,000 providers delivering more than 8 million annual patient visits, excluding asynchronous interactions.
- WELLSTAR Public Listing Strengthened the Balance SheetWELLSTAR began trading on the TSX Venture Exchange on October 1. Approximately $155 million of WELLSTAR redeemable preferred shares converted into WELLSTAR common equity, removing the liability from WELL's consolidated balance sheet. WELLSTAR had approximately $469 million of market capitalization, $93 million of cash and no debt as of September 30.
- WELLSTAR Continued Strong GrowthWELLSTAR revenue increased 33% year-over-year in Q3, and annual recurring revenue reached $83.7 million, up 27% year-over-year.
- Successful Bond Offering and Extended MaturitiesWELL completed its inaugural $150 million senior unsecured notes offering at 6.875%, with the notes maturing in 2031. The proceeds were used to repay $70 million of convertible debentures due at year-end, extending the debt maturity profile and providing fixed-rate, longer-dated financing.
- Canadian Clinic M&A Added ScaleYear-to-date in 2026, WELL completed 7 transactions that added 27 clinics, approximately $102 million in annual revenue and 203 providers. Compared with the same period in 2025, the company added more than 50% more annual revenue through fewer, larger transactions with nearly the same number of providers.
- Substantial Canadian Clinic Acquisition PipelineThe Canadian clinic pipeline represented $390 million in total revenue across more than 20 targets and over 100 clinics. The company said the pipeline includes opportunities under LOI and in the pre-LOI stage, with an emphasis on higher-margin areas such as diagnostics, procedural health, executive health and longevity health.
- Positive Healthcare Impact MetricsWELL clinics achieved a net promoter score of 84 versus an industry average of 34. WELLSTAR processed more than 520,000 e-referrals in Q3, HEALWELL screened more than 62,000 patient records for disease detection, and WELLTRUST surpassed 100,000 consents during Q3 and exceeded 120,000 consents as of October 31.
- OneWELL Public Sector OpportunityWELL is actively engaged with federal and provincial health authorities on opportunities representing well over $100 million in contract value. The company described OneWELL as an integrated offering combining care delivery, technology and clinical AI across more than 300 Canadian clinics, over 1,500 physicians and 5.6 million annualized visits.
- Wisp EBITDA ImprovementWisp generated Q3 revenue of $29 million and adjusted EBITDA of $3.2 million. Adjusted EBITDA increased approximately 146% from $1.3 million a year ago, making Q3 Wisp's strongest quarter of the year and its strongest EBITDA performance in years.
- CRH and Provider Staffing EBITDA GrowthCRH and provider staffing generated combined revenue of $126 million, flat year-over-year, while adjusted EBITDA increased 4.5% to $23.7 million. Growth in anesthesia offset lower provider staffing revenue.
- Competition Bureau Review CompletedOn October 22, the Competition Bureau issued a no-action letter concluding its review of WELL's acquisition of a controlling interest in HEALWELL AI.
- Strategic Focus on Higher-Margin OperationsWELL Research plans to focus more on its higher-margin site management organization and less on lower-margin contract research organization operations. CYBERWELL is focusing on a recurring-revenue data protection platform, and WELL said these transitions are intended to orient the businesses toward more durable, higher-margin operations.
- Updated 2026 Profitability OutlookWELL maintained confidence in delivering adjusted EBITDA firmly within its increased guidance range of $185 million to $195 million. Revenue guidance was approximately $1.58 billion, representing 16% normalized growth from 2025, while adjusted EBITDA guidance represents normalized growth of 13% to 19%.
- Long-Term Growth Targets ReaffirmedWELL reaffirmed its goal for WELL Canada, including WELL clinics and WELLSTAR, to reach a $1 billion revenue run rate by the end of 2028. Management also expects to continue its multiyear trend of delivering better than 10% annual adjusted EBITDA growth, excluding divestitures.
DE:W7V Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Mar 25, 2027 | 2026 (Q4) | 0.05- | 0.13 | ― | ― |
| Nov 09, 2026 | 2026 (Q3) | 0.040.07 | 0.1 | -31.87% (-0.03) | |
| Aug 06, 2026 | 2026 (Q2) | 0.030.03 | 0.06 | -50.00% (-0.03) | |
| May 07, 2026 | 2026 (Q1) | 0.030.04 | 0.02 | 100.00% (+0.02) | |
| Mar 19, 2026 | 2025 (Q4) | 0.070.13 | -0.04 | 385.71% (+0.17) | |
| Nov 06, 2025 | 2025 (Q3) | 0.060.10 | 0.03 | 220.00% (+0.07) | |
| Aug 14, 2025 | 2025 (Q2) | 0.060.06 | 0.03 | 100.00% (+0.03) | |
| May 14, 2025 | 2025 (Q1) | ―- | 0.05 | ― | |
| Apr 15, 2025 | 2024 (Q4) | 0.030.02 | 0.05 | -62.50% (-0.03) | |
| Nov 07, 2024 | 2024 (Q3) | 0.030.03 | 0.03 | 0.00% (+0.00) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
