


TransAlta earnings date
TransAlta (TZ1) Q3 2026 Earnings Report
DE:TZ1 Q3 2026 EPS Results
- Actual EPS
- EUR 0.11
- Consensus EPS
- EUR 0.04
- Beat/Miss
- Beat by +EUR 0.07
- One Year Ago EPS
- -EUR 0.01
DE:TZ1 Q3 2026 Revenue Results
- Actual Revenue
- EUR 340.39M
- Expected Revenue
- ―
- Beat/Miss
- ―
- YoY Revenue Growth
- -12.85%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 11/03/2026
- Time
- Before Open
- Conference Call
- Tuesday, November 3, 2026
TransAlta's next earnings date is estimated for February 25, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
Q3 2026 Earnings Slide Deck
Q3 2026 Earnings Call Summary
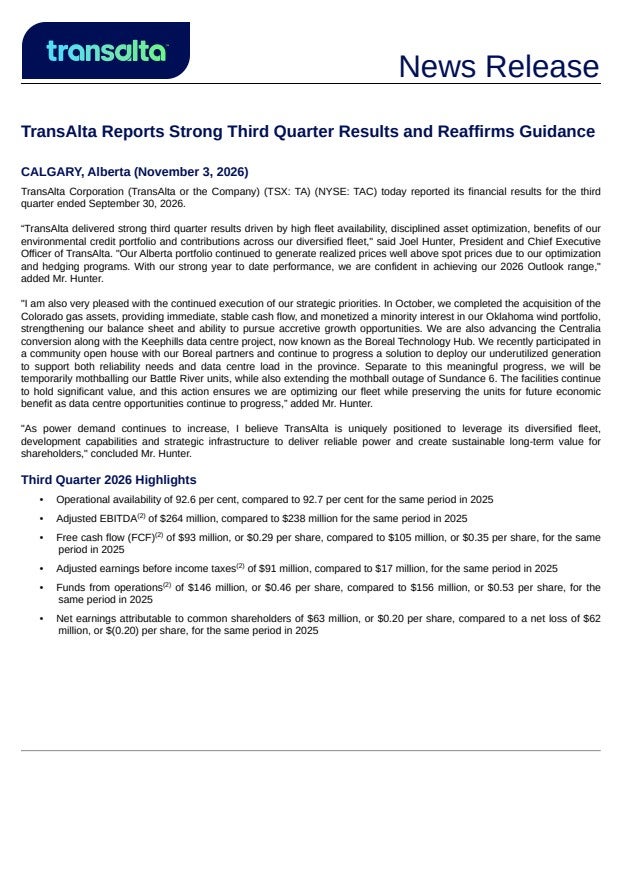
The call was predominantly positive. TransAlta reported strong adjusted EBITDA, free cash flow, fleet availability, hedge performance and segment contributions, reaffirmed 2026 guidance, completed a contracted Colorado acquisition, monetized a noncore Oklahoma wind interest and advanced the Boreal data center and Centralia conversion projects. The principal challenges were lower Alberta spot prices, low utilization of certain thermal units, unresolved ASO terms and a likely delay in Boreal definitive agreements into 2027.
Management said it “remain confident in achieving our 2026 guidance range,” with priorities including delivering adjusted EBITDA and free cash flow within 2026 guidance ranges; higher maintenance capital in the fourth quarter is expected to keep aggregate sustaining capital within the previously guided $140 million to $160 million range. For the balance of the year, approximately 2.1 thousand hours of Alberta generation are hedged at an average price of $67 per MWh, while for 2027 approximately 6.7 thousand GWh are hedged at an average price of $65 per MWh. TransAlta expects to receive Centralia environmental permits by year end and advance towards a final investment decision next year; Boreal is currently anticipated to provide up to 1.6 GW of electrical load from an initial 230 MW grid allocation, and the Colorado acquisition is expected to provide approximately $110 million of low risk high quality adjusted EBITDA per year.
- Strong Third-Quarter Financial and Operational PerformanceTransAlta delivered adjusted EBITDA of $264 million, free cash flow of $93 million or $0.29 per share, and average fleet availability of 92.6% during the third quarter. Management said the company remains confident in achieving its 2026 guidance range.
- Alberta Portfolio and Hedging Strategy Outperformed Spot PricesThe Alberta portfolio, hedging strategy and active asset optimization generated realized prices well above spot prices despite challenging market conditions. Approximately 2.5 thousand GWh of hedges were at an average price of $65 per MWh, a $28 premium to the $36 per MWh average Alberta spot price.
- Strong Realized Pricing Across Gas and Hydro FleetsThe gas fleet realized an average merchant price of $55 per MWh, a 53% premium to the average spot price, largely due to dispatch optimization during high-price hours. The hydro fleet realized $43 per MWh, a 19% premium to spot.
- Gas Segment EBITDA GrowthGas segment adjusted EBITDA was $29 million higher, driven by continued strong optimization of the Alberta fleet, realization of emissions credits, and positive contributions from facilities in Eastern Canada.
- Higher Renewable Generation Supported ResultsThe wind and solar segment reported increased adjusted EBITDA as higher wind resources across all regions provided additional upside.
- Energy Marketing and Corporate Cost PerformanceEnergy marketing increased $13 million year over year, reflecting strong performance from trading desks across U.S. power and natural gas markets. Corporate costs were 20% lower than the prior year.
- Carbon Obligation ReductionRenewable assets provided environmental offsets to the gas fleet's 2026 year-to-date carbon compliance obligation, resulting in a $51 million reduction in the carbon obligation during the quarter.
- Strong Hedge Book for 2026 and 2027For the balance of 2026, approximately 2.1 thousand hours of Alberta generation were hedged at an average price of $67 per MWh, significantly above current forward pricing. For 2027, approximately 6.7 thousand GWh were hedged at an average price of $65 per MWh, also well above current forward levels.
- Colorado Acquisition Added Contracted Cash FlowIn October, TransAlta closed the acquisition of two natural gas-fired peaking facilities in Colorado for US$1 billion. The 318 megawatts of operating assets are fully contracted for 26 years and are expected to provide approximately $110 million of low-risk, high-quality adjusted EBITDA per year.
- Oklahoma Wind Portfolio Sale Strengthened Capital FlexibilityTransAlta closed the sale of a 49% interest in its 502-megawatt Oklahoma wind portfolio to Ares Infrastructure Funds for US$305 million while retaining operational control. Management said the transaction monetizes part of a noncore geography, strengthens the balance sheet and supports accretive growth opportunities.
- Continued Asset-Recycling OpportunitiesManagement said asset recycling remains an important lever for strengthening the balance sheet. The company has more than 90 assets, including smaller assets outside its core areas, and generated $27 million from the sale of a small asset during the quarter while continuing to advance other monetization opportunities.
- Progress on Centralia Gas ConversionTransAlta continues to advance the conversion of Centralia to natural gas, expects to receive environmental permits by year end, and is progressing toward a final investment decision next year.
- Boreal Technology Hub Received AUC ApprovalTransAlta received Alberta Utilities Commission approval for the Keephills project, now known as the Boreal Technology Hub. The project is currently anticipated to provide up to 1.6 GW of electrical load, with power supplied initially from a 230 MW grid allocation and potentially from underutilized gas-fired steam capacity and longer-term redevelopment projects.
- Data Center Project Advanced Through Community EngagementThe Boreal team held a community open house on October 7 with just over 180 attendees over four hours. Management reported that the event was very positive, with no protests, and said the project is pursuing master site development permits ahead of construction.
- Alberta Data Center Demand Outlook Remains PositiveManagement said data center customers have shown a positive tone toward Alberta as an option, citing strong policy support, ASO support and Alberta's position as the only North American jurisdiction described as long power. The company also said demand for power is not abating and that demand exceeds near-term available supply in several markets.
- Long-Term Optionality From Existing Thermal AssetsTransAlta said its underutilized gas-fired steam units can operate at capacity factors greater than 90% and could support new data center load while providing reliability to Alberta's electricity system. The company is also in the queue for a large-frame turbine, with lead times of five or more years, to support longer-term repowering opportunities.
- Colorado Platform Creates Further WECC OpportunitiesManagement said the Colorado acquisition establishes a platform in a core Western U.S. market, creates opportunities as Colorado moves from coal to natural gas, and may support future development and marketing or trading opportunities with its new partner.
- Free Cash Flow and Capital Spending Remained Within GuidanceYear-to-date sustaining capital expenditures were down $22 million. Management expects higher maintenance capital in the fourth quarter but said aggregate sustaining capital is expected to remain within the previously guided $140 million to $160 million range.
DE:TZ1 Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Feb 25, 2027 | 2026 (Q4) | 0.02- | -0.04 | ― | ― |
| Nov 03, 2026 | 2026 (Q3) | 0.040.11 | -0.01 | 1000.00% (+0.13) | |
| Jul 31, 2026 | 2026 (Q2) | 0.100.11 | 0.11 | 0.00% (+0.00) | |
| May 06, 2026 | 2026 (Q1) | -0.010.03 | 0.1 | -73.33% (-0.07) | |
| Feb 27, 2026 | 2025 (Q4) | 0.03-0.04 | -0.14 | 72.73% (+0.10) | |
| Nov 05, 2025 | 2025 (Q3) | 0.03-0.01 | -0.08 | 83.33% (+0.06) | |
| Aug 01, 2025 | 2025 (Q2) | 0.070.11 | 0.11 | 0.00% (+0.00) | |
| May 07, 2025 | 2025 (Q1) | 0.070.10 | 0.46 | -79.17% (-0.36) | |
| Feb 20, 2025 | 2024 (Q4) | 0.04-0.14 | -0.17 | 18.52% (+0.03) | |
| Nov 05, 2024 | 2024 (Q3) | 0.09-0.08 | 0.9 | -108.51% (-0.97) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
