


Spin Master earnings date
Spin Master (SP9) Q3 2026 Earnings Report
DE:SP9 Q3 2026 EPS Results
- Actual EPS
- EUR 0.92
- Consensus EPS
- EUR 0.82
- Beat/Miss
- Beat by +EUR 0.10
- One Year Ago EPS
- EUR 0.99
DE:SP9 Q3 2026 Revenue Results
- Actual Revenue
- EUR 653.32M
- Expected Revenue
- EUR 654.18M
- Beat/Miss
- Missed by -EUR 860.83K
- YoY Revenue Growth
- +1.38%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 10/29/2026
- Time
- Before Open
- Conference Call
- Thursday, October 29, 2026
Spin Master's next earnings date is estimated for March 1, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q3 2026 Earnings Slide Deck
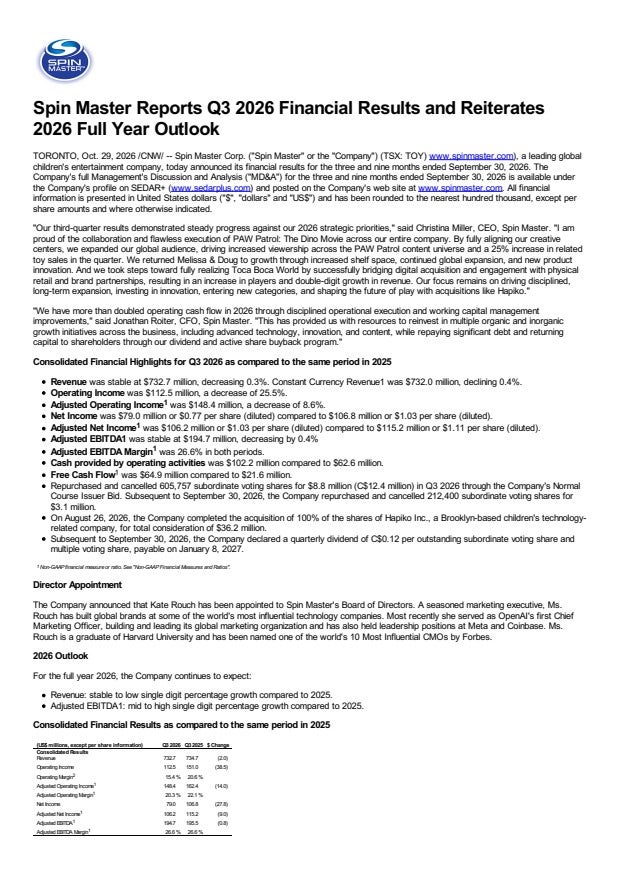
Q3 2026 Earnings Call Summary
The call was broadly constructive. Core brands delivered growth, year-to-date adjusted EBITDA increased 7%, cash flow and leverage improved, strategic initiatives gained traction, and full-year guidance was reiterated. These positives were tempered by stable rather than accelerating consolidated revenue, lower reported margins, impairments, declines in Toy and Digital Games reported results, a roughly $30 million tariff headwind and uncertainty around fourth-quarter replenishment demand and the nonrecurrence of the 2026 movie benefit.
Spin Master reiterated its 2026 guidance for stable to low single-digit growth in revenues and mid- to upper single-digit growth in adjusted EBITDA; for the fourth quarter, it is targeting modest revenue and similar adjusted EBITDA growth, although it said it is too soon to provide specifics on where it expects to land within its full year guidance range, with 50% of POS occurring in the fourth quarter and a healthy majority of fourth-quarter orders being domestic replenishment rather than direct import. Management expects about $25 million of revenue and EBITDA directly associated with the PAW Patrol: The Dino Movie this year and said, for modeling purposes, to assume that doesn't reoccur as it heads into '27; it also said Hapiko distribution will widen in the back half of next year and that it will start to ship wider as it gets deeper into 2027.
- Year-to-Date EBITDA Growth and Reaffirmed GuidanceYear-to-date revenue was stable and adjusted EBITDA increased 7%. Management reiterated full-year 2026 guidance for stable to low single-digit revenue growth and mid- to upper-single-digit adjusted EBITDA growth.
- Stable Third-Quarter Results Supported by Core BrandsThird-quarter revenue and adjusted EBITDA were stable, driven by double-digit growth across core brands including PAW Patrol, Melissa & Doug and Toca Boca World.
- PAW Patrol and Melissa & Doug Brand GrowthOwned-brand growth within Toy was led by a 26% increase in PAW Patrol and 10% growth in Melissa & Doug, along with contributions from new products and existing brands.
- Digital Games Revenue Growth in Core PlatformsToca Boca World revenue increased 13% and Piknik revenue grew 6%, driven by increased player bases resulting from investments in player experience and expanded partnerships with global brands.
- PAW Patrol Movie Boosted Entertainment RevenueEntertainment center revenue increased by $20 million due to distribution revenue received upon delivery of PAW Patrol: The Dino Movie. Management said the movie received the highest critical acclaim of the three movies to date, delighted global audiences and increased the brand's relevance and franchise strength.
- PAW Patrol Franchise Expansion and Retail LeadershipThe PAW Patrol movie supported content viewership, digital app monetization, consumer products, music, social-platform activity and toy sales. Spin Master ranked #1 in infant, toddler and preschool in the quarter.
- Fourth PAW Patrol Movie ApprovedSpin Master announced the green light of a fourth PAW Patrol movie, to be released in association with Nickelodeon Movies and distributed by Paramount in 2029. The first three movies have generated a combined $0.5 billion in box office revenue.
- Melissa & Doug Expansion and Healthy Sales GrowthMelissa & Doug delivered healthy third-quarter sales growth, supported by broader U.S. and international distribution, marketing innovation in core categories and expansion into new areas of play including the Cheery Lane play-set launch.
- Melissa & Doug Expansion Beyond ToysSpin Master is building Melissa & Doug as a broader family brand centered on purposeful play, with partnerships and out-licensing opportunities spanning toy collaborations, retail experiences, publishing, apparel and music. The company launched branded books through a partnership with Penguin Random House.
- Toca Boca Engagement Reached Multiyear HighsToca Boca's digital-to-physical strategy increased reach, social-media activity and fan engagement, driving players and revenue back into Toca Boca World. Investments in content quality and technical stability helped the game achieve multiyear highs in player engagement and sentiment.
- Toca Boca Partnerships Expanded Brand ReachThe Music Month partnership with Olivia Rodrigo and TWICE broadened reach. The MINISO partnership placed exclusive merchandise in more than 400 stores and generated record levels of user-generated content and strong in-game engagement, while Adidas added in-game style packs and in-store activations.
- PAW Patrol Streaming and Ongoing Brand MomentumPAW Patrol: The Dino Movie moved to streaming and was in the top 10 across digital storefronts domestically and globally. Management said the Dino theme continued to resonate with fans and retailers.
- New Strategic Trading Card Game ProgressHellbreak added more studio partners. Spin Master planned to begin selling the first set of cards in the quarter, with the game scheduled to go live to consumers in January.
- Stickerbox Early Traction and Hapiko Platform PotentialFollowing the Hapiko acquisition, Stickerbox was on multiple top-toy lists, nominated for awards, named to TIME Magazine's Best Inventions of 2026 and had sold out more than three times since acquisition. Spin Master plans to expand distribution into wider channels and markets in 2027 and evolve the offering through its IP, licensing partnerships and new creative play experiences.
- Stable Gross Profit and Adjusted EBITDA MarginsGross profit before depreciation and amortization was stable on both a dollar and margin basis, while adjusted EBITDA was also stable on a dollar and margin basis. Flat operating expenses below gross profit reflected higher marketing expenses offset by lower selling royalties and higher product development costs offset by lower administrative costs.
- Improved Cash Flow and Lower LeverageThird-quarter operating cash flow increased by $40 million, and year-to-date operating cash flow more than doubled through operational execution and working-capital improvements. The company continued to return capital through dividends and share buybacks while repaying debt. Net leverage ended the quarter at approximately 0.8 turns, or 0.3 turns excluding leases, both approximately 0.4 turns lower than last year.
- Operating Simplification and Reinvestment in GrowthSpin Master simplified its operating model, organized digital investments across the Toca Boca and Sago Mini studios and three main revenue streams, wound down some entertainment projects, accelerated manufacturing diversification and implemented cost-reduction measures. The savings were reinvested in advanced technology, the Hapiko acquisition, strategic trading cards and collectibles.
- Fourth-Quarter Outlook and Retail PositioningManagement is targeting modest fourth-quarter revenue growth and similar adjusted EBITDA growth. Retail inventory levels were described as healthy, and October was tracking as expected across gross product sales, digital games and point-of-sale activity.
- Digital Games Platform Growth StrategyManagement expects the digital studios to grow at rates higher than the overall business. Toca Boca has approximately 60 million active users and is being expanded beyond digital through partnerships and physical products. Piknik had approximately 0.5 million subscribers, with growth expected from additional content and efforts to retain families longer on the platform.
- Pricing Discipline and Supply-Chain PlanningSpin Master is keeping its pricing strategy steady, with approximately 50% of products priced below $19.99. For 2027, product design, mix and supply-chain initiatives were developed around heightened commodity prices, with management saying it was comfortable with the cost outlook and working to eliminate or reduce costs.
- October Pay-Per-View PerformanceThe PAW Patrol movie performed exceptionally well on pay-per-view, reaching the top three at one point and remaining in the top five among families' pay-per-view choices.
DE:SP9 Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Mar 01, 2027 | 2026 (Q4) | 0.47- | 0.36 | ― | ― |
| Oct 29, 2026 | 2026 (Q3) | 0.820.92 | 0.99 | -7.21% (-0.07) | |
| Jul 30, 2026 | 2026 (Q2) | -0.070.07 | -0.06 | 214.29% (+0.13) | |
| Apr 30, 2026 | 2026 (Q1) | -0.26-0.21 | -0.11 | -100.00% (-0.11) | |
| Mar 05, 2026 | 2025 (Q4) | 0.330.36 | 0.49 | -25.45% (-0.12) | |
| Oct 30, 2025 | 2025 (Q3) | 0.910.99 | 1.42 | -30.63% (-0.44) | |
| Jul 31, 2025 | 2025 (Q2) | 0.07-0.06 | 0.08 | -177.78% (-0.14) | |
| Apr 30, 2025 | 2025 (Q1) | -0.14-0.11 | -0.17 | 36.84% (+0.06) | |
| Feb 24, 2025 | 2024 (Q4) | 0.610.49 | 0.17 | 189.47% (+0.32) | |
| Oct 30, 2024 | 2024 (Q3) | 1.451.42 | 1.19 | 19.40% (+0.23) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
