

PetroTal Corp (SER1) Q2 2026 Earnings Report
DE:SER1 Q2 2026 EPS Results
- Actual EPS
- EUR 0.01
- Consensus EPS
- ―
- Beat/Miss
- ―
- One Year Ago EPS
- EUR 0.02
DE:SER1 Q2 2026 Revenue Results
- Actual Revenue
- EUR 57.49M
- Expected Revenue
- ―
- Beat/Miss
- ―
- YoY Revenue Growth
- -8.53%
Earnings Announcement Details
- Quarter
- Q2 2026
- Date
- 08/06/2026
- Time
- Before Open
- Conference Call
- Thursday, August 6, 2026
PetroTal Corp's next earnings date is estimated for November 9, 2026, based on past reporting schedules.
Q2 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q2 2026 Earnings Slide Deck
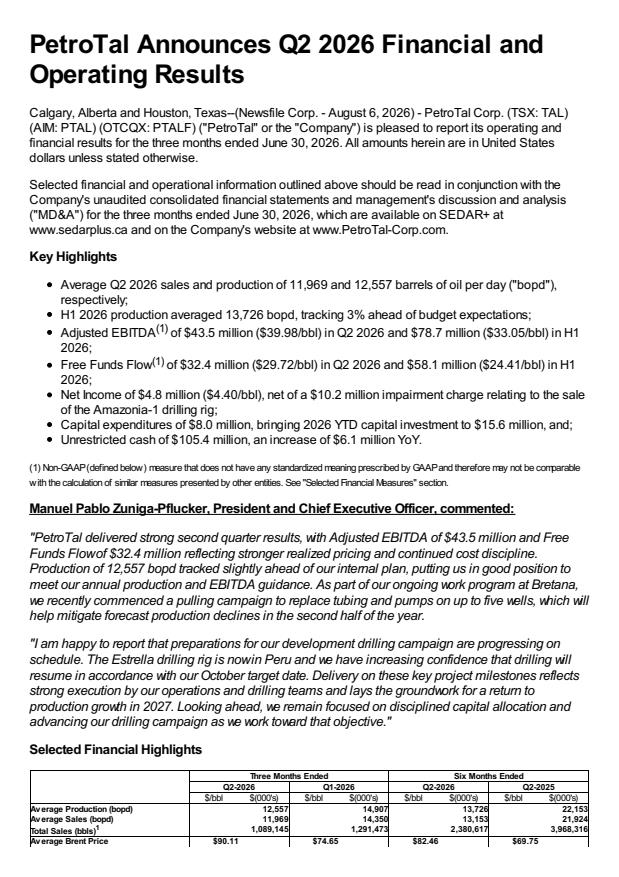
Q2 2026 Earnings Call Summary
The call presented several strong positives: robust cash and low debt, meaningful reserve value, improving realized prices and netbacks, QoQ growth in adjusted EBITDA and free cash flow, and a clearly articulated plan to restart an 8-well drilling campaign to return production toward a 20,000 bpd target. Offsetting these are significant near-term challenges: a substantial YoY production decline (−40%), higher per-barrel costs driven by lower volumes, a noncash impairment that depressed net income, and several execution/timing uncertainties (erosion control, El Niño risks, and undisclosed costs for larger water injection capacity). Overall, management conveyed confidence in growth prospects and financial resilience, but results remain contingent on successful and timely execution of the upcoming drilling and infrastructure programs.
The company reiterated 2026 guidance of ~12,000 bpd average production and an adjusted EBITDA range of $110–$120M (earlier slide assumptions of 12,000 bpd and $83.60/bbl Brent implied ~$180M net operating income and ~ $170M EBITDA), with capital expenditures guided at $80–$90M (Camilo also referenced ~$85M in the guidance summary); first‑half adjusted EBITDA was $78.7M and first‑half CapEx $15.6M. Management expects available cash to rise from about $105M today to ~ $120M by year‑end (total cash $137M; total debt $37.5M), generating roughly $8M of after‑tax free funds flow for the year and no dividends in the baseline plan. Operationally they plan an 8‑well program (Estrella rig) to spud in early October, assuming ~5,000 bpd per new well, ~45–50 days per well, targeting >20,000 bpd monthly average by mid‑2027 (possible daily 20k in Q1 2027); Q2 production was 12,557 bpd (down 16% q/q, 40% y/y), Q2 adjusted EBITDA $43.5M and Q2 free funds flow $32.4M. Remaining 2P reserves were cited at 110 million barrels (NPV10 $1.2B) after 32 million barrels produced to date.
- Strong reserve base and track record110 million barrels of remaining 2P reserves with an NPV10 of $1.2 billion; company has invested $675 million in Peru, generated over $1 billion of EBITDA to date and returned more than $150 million to shareholders; Bretaña field tripled in size since inception.
- Robust cash position and low leverageEnded Q2 with $137 million of total cash and $105 million of available cash versus only $37.5 million of total debt, reflecting a strong net cash position.
- Improving netbacks and pricing benefitBrent realized price increased by $15.46 per barrel QoQ and $24.56 per barrel YoY, driving net operating income per barrel higher by $12.78 QoQ and $22.59 YoY.
- Quarterly profitability and cash generationQ2 adjusted EBITDA of $43.5 million, up 24% quarter-over-quarter; free funds flow of $32.4 million, up 26% QoQ and 19% YoY; first half 2026 adjusted EBITDA of $78.7 million keeps the company on track for full-year guidance of $110–$120 million.
- Clear near-term growth plan: drilling restartContracted Estrella rig for an 8-well campaign with an expected early-October spud; management targets returning to >20,000 barrels per day (monthly average) by mid-2027, using median type curves from 19 proven horizontal wells.
- High-performing offset wells bolster confidenceFirst two planned wells offset well 10H, which produced more than 2.1 million barrels and had a 30-day average of just over 9,000 bpd; new wells conservatively modeled at ~5,000 bpd each.
- Operational improvements on water handling and costsWater processing capacity improved from a planned 170,000 bpd to about 180,000 bpd; operating expenses were flat in total dollars at $11 million for the quarter and management reports operational cost reductions (~18% vs historical levels and ~20% YoY savings mentioned).
- Guidance and year-end cash buildFull-year assumptions (12,000 bpd and $83.60/bbl Brent) imply ~$180 million net operating income and ~ $170 million EBITDA; company expects available cash to rise from ~$105 million to ~$120 million by year-end even with a back-half capex ramp.
- Optionality to extend drilling programCompany notes 13 proved locations and 22 locations on a 2P basis, giving optionality to continue drilling beyond the contracted 8-well program.
DE:SER1 Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Nov 09, 2026 | 2026 (Q3) | ―- | 0 | ― | ― |
| Aug 06, 2026 | 2026 (Q2) | ―0.01 | 0.02 | -50.00% (-0.01) | |
| May 07, 2026 | 2026 (Q1) | ―0.01 | 0.03 | -66.67% (-0.02) | |
| Mar 26, 2026 | 2025 (Q4) | ―-0.01 | 0.02 | -150.00% (-0.03) | |
| Nov 13, 2025 | 2025 (Q3) | ―0.00 | 0.01 | -100.00% (-0.01) | |
| Aug 07, 2025 | 2025 (Q2) | 0.020.02 | 0.04 | -50.00% (-0.02) | |
| May 12, 2025 | 2025 (Q1) | ―0.03 | 0.04 | -40.00% (-0.02) | |
| Mar 20, 2025 | 2024 (Q4) | ―0.02 | 0.02 | 0.00% (+0.00) | |
| Nov 14, 2024 | 2024 (Q3) | ―0.01 | 0.03 | -66.67% (-0.02) | |
| Aug 08, 2024 | 2024 (Q2) | ―0.04 | 0.05 | -21.57% (-0.01) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
