


Keyera Corp. earnings date
Keyera Corp. (K2Y) Q3 2026 Earnings Report
DE:K2Y Q3 2026 EPS Results
- Actual EPS
- -EUR 0.15
- Consensus EPS
- EUR 0.31
- Beat/Miss
- Missed by -EUR 0.46
- One Year Ago EPS
- EUR 0.24
DE:K2Y Q3 2026 Revenue Results
- Actual Revenue
- EUR 1.78B
- Expected Revenue
- EUR 1.78B
- Beat/Miss
- Missed by -EUR 1.58M
- YoY Revenue Growth
- +55.95%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 11/10/2026
- Time
- Before Open
- Conference Call
- Tuesday, November 10, 2026
Keyera Corp.'s next earnings date is estimated for February 17, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q3 2026 Earnings Slide Deck
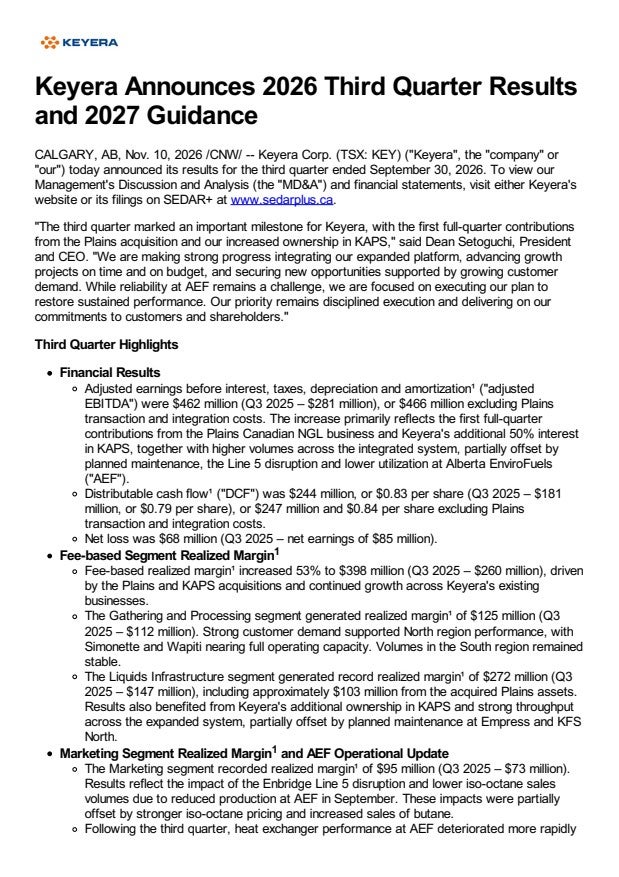
Q3 2026 Earnings Call Summary
The call was predominantly positive. Keyera reported strong fee-based performance, record Liquids Infrastructure margin, Plains synergies ahead of target, favorable project execution and raised 2026 marketing guidance. The main challenges were AEF reliability and associated outages, the quarterly net loss, Line 5 and turnaround disruptions, and leverage remaining above the long-term target range. Management expressed confidence in the AEF remediation plan and expected deleveraging trajectory.
Keyera increased 2026 marketing realized margin guidance to between $400 million and $430 million; maintenance capital expenditures are now expected to range between $260 million and $280 million, an increase of $20 million, and cash taxes are expected to range between $55 million and $75 million. For 2027, targeted fee-based adjusted EBITDA per share CAGR remains 16% to 18% from 2025 through 2027 and 7% to 8% between 2027 and 2029; growth capital is expected to range between $630 million and $670 million, maintenance capital expenditures between $250 million and $280 million, including approximately $20 million for planned equipment replacement and associated work at AEF and $20 million for onetime IT integration-related projects, and cash taxes between $130 million and $150 million. The Plains acquisition synergy target is $120 million to $140 million within 12 months, with $115 million of run rate synergies delivered at the end of September; net debt to adjusted EBITDA was approximately 3.6x, with a return to the target range expected in 2028. AEF is expected to undergo an interim outage of approximately 4 weeks in early January, with permanent replacement equipment planned for May 2027 and a return to full production expected by the end of that month, while the Fort Saskatchewan condensate system debottleneck is expected to increase capacity by approximately 15% and be in service early next year.
- Strong Quarter Across Expanded PlatformManagement described the quarter as strong across Keyera's expanded platform, with the acquired Plains assets performing ahead of expectations. The company is on track to achieve its near-term synergy targets and has identified additional value-creation opportunities beyond its initial expectations.
- Plains Synergies Ahead of TargetKeyera had delivered $115 million of run-rate synergies by the end of September against its $120 million to $140 million target for the first 12 months after closing. Management cited higher-than-modeled volumes, higher liquids yields at Empress, higher frac spreads, avoided capital and hundreds of additional margin and cost opportunities.
- Fee-Based Financial PerformanceExcluding transaction and integration costs related to the Plains acquisition, adjusted EBITDA was $466 million and DCF was $247 million, or $0.84 per share. Gathering and Processing realized margin was $125 million, while Liquids Infrastructure realized record margin of $272 million.
- Record Liquids Infrastructure MarginLiquids Infrastructure delivered another record quarter of realized margin, supported by strong performance from the legacy asset base, first full-quarter contributions from the Plains assets and Keyera's additional 50% interest in KAPS, together with strong throughput across the asset base.
- Strong Gathering and Processing DemandStrong customer demand drove continued growth in the North region, with both the Wapiti and Simonette facilities approaching full operating capacity. Keyera also reported robust gas flows through Pipestone, Wapiti and Simonette, record wells being drilled around its facilities and expectations for additional gas gathering and processing demand from LNG Canada Phase 2 and potentially other LNG projects.
- Condensate System ExpansionKeyera is pursuing a capital-efficient debottleneck of its Fort Saskatchewan condensate system that will increase capacity by approximately 15%, with the additional capacity expected to be in service early next year. The investment is essentially contracted, and management said it has secured contracts over the last 3 to 6 months and is in additional discussions with major oil sands producers.
- Additional Oil Sands Egress CapacityManagement said the company is well positioned to support oil sands growth, including the potential addition of 1 million to 2 million barrels of oil egress capacity. Keyera also has available capacity on its 100%-owned KAPS condensate line and approximately a couple of hundred thousand barrels of capacity remaining on the existing Norlite pipe.
- Capital Projects on Schedule and Below BudgetAll major growth projects remain on schedule and are tracking on or below budget. Management said projects are advancing on time and at or below budget, with Zone 4 approximately $40 million under its original budget and the ACE Terminal also tracking well.
- Improved Project ExecutionManagement attributed project execution improvements to applying lessons from Zones 1 through 3 and establishing stronger relationships and partnerships with service providers. Keyera said it selected the best-performing service providers for Zone 4 and is benefiting from those partnerships and available crews.
- Raised 2026 Marketing GuidanceKeyera increased its 2026 marketing realized margin guidance to between $400 million and $430 million. The revised outlook reflects stronger-than-anticipated iso-octane and butane margin contributions and approximately $50 million of incremental benefits from the revaluation of inventory and related hedges associated with the Plains acquisition.
- 2027 Growth OutlookKeyera remains on track to achieve its targeted fee-based adjusted EBITDA per share CAGR of 16% to 18% from 2025 through 2027 and 7% to 8% between 2027 and 2029. The company expects 2027 growth capital of $630 million to $670 million, primarily for projects already underway.
- Expected Capital Spend Reduction After 2027Management said most spending on announced major projects will be completed by the end of 2027, with capital spending expected to come off materially in 2028. This is expected to support balance-sheet deleveraging while the company begins to receive EBITDA from the projects.
- Strong Marketing PositioningManagement cited strong underlying fundamentals in the marketing business, including favorable crude and RBOB crack pricing, an octane premium, bullish propane expectations, favorable butane spot sales and additional market access from the Plains assets. Keyera has used its risk-management policy to lock in favorable prices into 2027 and started doing so into 2028.
- Flexible Rail and Terminal AssetsKeyera said its rail assets provide flexibility to move hydrocarbons west to east. The company recently completed a deal facilitating crude movement from the ADT terminal, is creating flexibility to move both butane and propane from KJT, and sees opportunities to expand the ACE Terminal in response to demand for Western Canadian hydrocarbons.
- Contracted Investment PhilosophyManagement reiterated that Keyera generally seeks customer contracts before sanctioning capital investments. Existing systems can also be expanded incrementally and in a capital-efficient manner as customer growth materializes.
- AEF Reliability Remediation PlanAlthough AEF reliability has fallen short of expectations, management said it understands the primary cause of the heat-exchanger failure. Keyera plans an interim repair outage of approximately 4 weeks in early January, followed by installation of permanent replacement equipment in May 2027, with full production expected by the end of that month. The permanent replacement will use a design that previously operated reliably for over 25 years.
- AEF Operating and Maintenance ChangesKeyera has shifted AEF operations from maximizing short-term production to operating within defined reliability parameters supported by more frequent planned maintenance. The company plans to pull forward work originally proposed for 2028 into 2027 and expects to avoid another outage in 2028.
DE:K2Y Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Feb 17, 2027 | 2026 (Q4) | 0.65- | 0.25 | ― | ― |
| Nov 10, 2026 | 2026 (Q3) | 0.31-0.15 | 0.24 | -162.16% (-0.38) | |
| Aug 06, 2026 | 2026 (Q2) | 0.130.76 | 0.35 | 116.36% (+0.41) | |
| May 14, 2026 | 2026 (Q1) | 0.06-0.34 | 0.36 | -192.98% (-0.70) | |
| Feb 12, 2026 | 2025 (Q4) | 0.270.25 | 0.25 | 0.00% (+0.00) | |
| Nov 14, 2025 | 2025 (Q3) | 0.330.24 | 0.51 | -54.32% (-0.28) | |
| Aug 07, 2025 | 2025 (Q2) | 0.240.35 | 0.39 | -11.29% (-0.04) | |
| May 15, 2025 | 2025 (Q1) | 0.330.36 | 0.2 | 83.87% (+0.17) | |
| Feb 13, 2025 | 2024 (Q4) | 0.310.25 | 0.13 | 85.71% (+0.11) | |
| Nov 14, 2024 | 2024 (Q3) | 0.360.51 | 0.22 | 138.24% (+0.30) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
