

Designer Brands (D9W) Q2 2026 Earnings Report
DE:D9W Q2 2026 EPS Results
- Actual EPS
- EUR 0.30
- Consensus EPS
- EUR 0.23
- Beat/Miss
- Beat by +EUR 0.07
- One Year Ago EPS
- EUR 0.30
DE:D9W Q2 2026 Revenue Results
- Actual Revenue
- EUR 652.02M
- Expected Revenue
- EUR 664.54M
- Beat/Miss
- Missed by -EUR 12.52M
- YoY Revenue Growth
- -1.23%
Earnings Announcement Details
- Quarter
- Q2 2026
- Date
- 09/10/2026
- Time
- Before Open
- Conference Call
- Thursday, September 10, 2026
Designer Brands's next earnings date is estimated for December 8, 2026, based on past reporting schedules.
Q2 2026 Earnings Call Audio
Q2 2026 Earnings Slide Deck
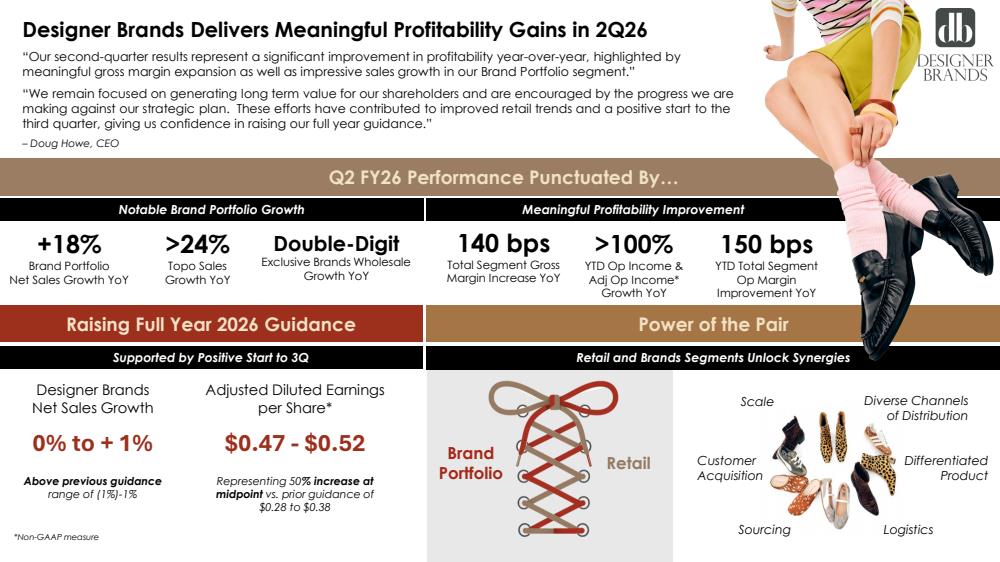
Q2 2026 Earnings Call Summary
The call was predominantly positive. Despite a 1% consolidated sales decline, a 2.4% comparable-store sales decline, seasonal and athletic softness, and anticipated third-quarter profitability pressure, the company reported substantial year-to-date operating income growth, broad gross margin expansion, strong brand portfolio performance, lower debt, improving retail trends, and materially raised full-year sales and EPS guidance.
For fiscal 2026, Designer Brands now anticipates total company sales to be flat to up 1% versus last year, compared to its previous guidance of -1% to +1%; retail sales are expected to be flat to down slightly versus last year, with double-digit sales growth in the brand segment, while Keds is expected to deliver robust double-digit growth for full year 2026. The company now anticipates adjusted diluted EPS between $0.47 and $0.52, compared to its prior guidance of between $0.28 and $0.38 per diluted share, assuming an effective tax rate of approximately 41% and an average diluted share count of 57 million shares for the year. Topo is expected to generate over $100 million in 2027, and the company expects greater year-over-year pressure on profitability in the third quarter.
- Significant Year-to-Date Profitability ImprovementAdjusted operating income was $58.8 million year to date, up $30 million and more than doubling the prior-year period, reflecting progress in strengthening underlying profitability.
- Gross Margin ExpansionAdjusted consolidated gross margin was 47.9%, improving 430 basis points year over year. Tariff refund claims of $20.2 million contributed 280 basis points, while the remaining $7 million, or 150 basis points, of improvement primarily came from stronger segment margins due to improved product assortment and inventory management.
- Improved Quarterly Operating ResultsAdjusted operating income was $39.4 million in the second quarter, with adjusted operating margin improving 140 basis points. Adjusted net income increased to $19.2 million, or $0.34 per diluted share, compared with $16.4 million, or $0.33 per diluted share, last year.
- Brand Portfolio Segment GrowthBrand portfolio sales increased 18% in the second quarter, with growth led by Topo and Jessica Simpson. Wholesale sales of exclusive brands were up double digits year to date, demonstrating growth across multiple distribution channels.
- Topo Momentum and Expansion OpportunityTopo revenue increased more than 24% during the quarter. The company expects Topo to generate over $100 million in 2027, with additional opportunity in existing and new distribution channels; the brand currently has about 1,600 doors and is not sold in DSW.
- Jessica Simpson and Keds PerformanceJessica Simpson sales increased approximately 24% year over year, with growth across all major accounts. Keds performed in line with plan in the second quarter, supported by strong direct-to-consumer performance, and the company continues to expect robust double-digit growth for full-year 2026.
- Retail Margin and Assortment ProductivityRetail merchandise margin expanded 140 basis points, including approximately 40 basis points from initial markup and 100 basis points from lower markdowns. The company narrowed assortment breadth, focused investment on brands, categories, and styles with the strongest customer response, and its top ten brands outperformed the balance of the assortment with meaningfully less promotional activity than last year.
- Strength in Dress, Affordable Luxury, and Adjacent CategoriesWomen's dress sales grew in the high single digits during the quarter. Affordable luxury volume nearly doubled last year's level, while categories adjacent to footwear grew approximately 10%. Dress and boots also showed encouraging quarter-to-date trends.
- Improving Retail TrendsAthletic demand improved sequentially by 400 basis points in August. Retail trends improved during the quarter, stores returned to positive comps quarter to date, and retail sales were slightly positive quarter to date in the third quarter.
- Brand Repositioning and Customer EngagementThe DSW repositioning campaign, including a partnership with Ciara Miller from Bravo's "Summer House," generated 7 billion earned impressions and the brand's all-time highest-performing social content.
- Rewards Program RelaunchDSW is relaunching its rewards program, with nearly 90% of transactions coming from approximately 30 million VIP members. The updated program adds quicker access to rewards, extended redemption timing, greater personalization, enhanced engagement, and special perks.
- Store Expansion and Format InnovationThe company opened five new stores in the second quarter, expects them to be accretive to earnings in their first year, and reported that stores remodeled since 2025 are outperforming the balance of the chain on comparable sales. It will also pilot four The Edit at DSW store-within-a-store locations between 1,000 and 1,500 square feet this fall.
- Stronger Balance Sheet and LiquidityCash increased to $51.6 million from $44.9 million last year. The company had $146.2 million available under its revolving credit facility, resulting in approximately $198 million of total liquidity. Total debt declined to $423.1 million from $516.3 million, a reduction of over $93 million.
- Raised Full-Year Sales and EPS GuidanceFiscal-year sales guidance was raised to flat to up 1% versus last year from the prior range of -1% to +1%. Adjusted diluted EPS guidance increased to $0.47-$0.52 from $0.28-$0.38, supported by stronger sales expectations, continued gross margin expansion, disciplined expense management, and lower debt levels.
DE:D9W Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Dec 08, 2026 | 2026 (Q3) | 0.28- | 0.34 | ― | ― |
| Sep 10, 2026 | 2026 (Q2) | 0.230.30 | 0.3 | 0.00% (+0.00) | |
| Jun 09, 2026 | 2026 (Q1) | 0.030.06 | -0.23 | 126.92% (+0.29) | |
| Mar 26, 2026 | 2025 (Q4) | -0.44-0.28 | -0.39 | 29.55% (+0.12) | |
| Dec 09, 2025 | 2025 (Q3) | 0.160.34 | 0.24 | 40.74% (+0.10) | |
| Sep 09, 2025 | 2025 (Q2) | 0.200.30 | 0.26 | 17.24% (+0.04) | |
| Jun 10, 2025 | 2025 (Q1) | -0.06-0.23 | 0.07 | -425.00% (-0.30) | |
| Mar 20, 2025 | 2024 (Q4) | -0.44-0.39 | -0.39 | 0.00% (+0.00) | |
| Dec 10, 2024 | 2024 (Q3) | 0.310.24 | 0.21 | 12.50% (+0.03) | |
| Sep 11, 2024 | 2024 (Q2) | 0.470.26 | 0.53 | -50.85% (-0.27) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.