

Cineplex (CX0) Q2 2026 Earnings Report
DE:CX0 Q2 2026 EPS Results
- Actual EPS
- EUR 0.08
- Consensus EPS
- EUR 0.13
- Beat/Miss
- Missed by -EUR 0.05
- One Year Ago EPS
- -EUR 0.02
DE:CX0 Q2 2026 Revenue Results
- Actual Revenue
- EUR 245.17M
- Expected Revenue
- EUR 241.93M
- Beat/Miss
- Beat by +EUR 3.24M
- YoY Revenue Growth
- +6.06%
Earnings Announcement Details
- Quarter
- Q2 2026
- Date
- 08/11/2026
- Time
- Before Open
- Conference Call
- Tuesday, August 11, 2026
Cineplex's next earnings date is estimated for November 5, 2026, based on past reporting schedules.
Q2 2026 Earnings Call Audio
Q2 2026 Earnings Slide Deck
Q2 2026 Earnings Call Summary
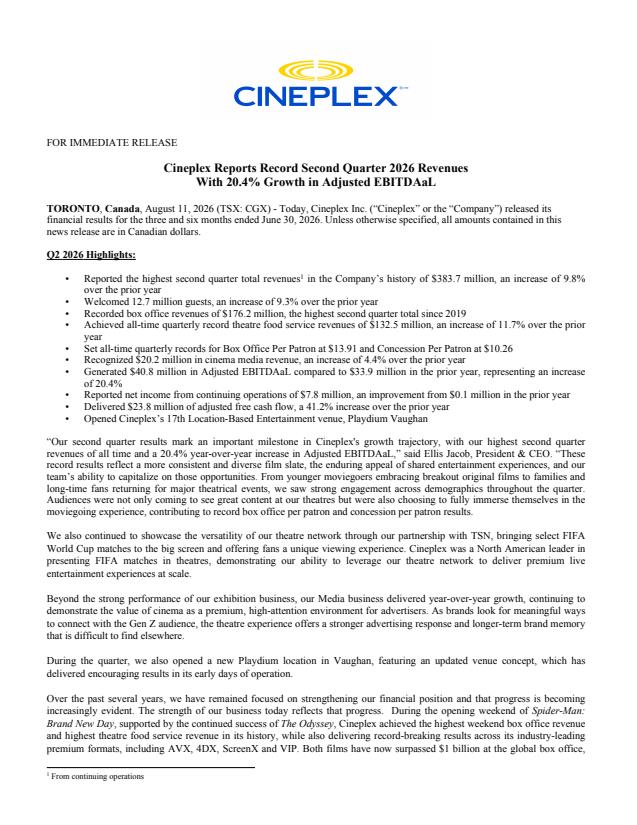
The call emphasized multiple record-breaking operational and financial outcomes: revenue (+9.8%), attendance (+9.3%), adjusted EBITDA (+20.4%), record concession and merchandise performance (merchandise +45%), and strengthening liquidity and deleveraging progress. Management acknowledged near-term softness in the LBE segment, modest media headwinds versus an elevated prior-year comparison, and one-time LTIP and JV marketing expenses. On balance, the positives—broad content-driven demand, strong margin expansion in exhibition, improved cash and leverage trajectory, and strategic loyalty/distribution gains—substantially outweighed the isolated and largely one-time or localized negatives.
Cineplex's forward guidance emphasized disciplined capital allocation and a clear path to deleveraging: net capital expenditures for 2026 are guided to about $50 million (Q2 net capex was $7 million) with preliminary 2027 capex of roughly $60 million; management reiterated its target net leverage range of 2.5–3.0x (leverage has fallen ~1.5 turns over the past 18 months and management expects to reach the target in the near term, potentially by Q4 if the domestic box office tracks toward the ~$10 billion industry forecast); achieving that leverage range would enable opportunistic share repurchases under the NCIB and the potential reintroduction of a dividend. They closed Q2 with $116.8 million of cash, no drawings on the $100 million covenant‑light revolver and about $92.5 million available after letters of credit, flagged a one‑time LTIP expense of ~ $6 million for 2026 (≈$3 million recorded in H1), and said improving adjusted EBITDA and cash‑flow momentum (Q2 adjusted EBITDA $40.8 million, revenue $383.7 million, attendance 12.7 million) underpins the balance‑sheet and capital‑return priorities.
- Record Quarterly RevenueTotal revenue of $383.7 million, a new second-quarter record, up 9.8% year-over-year, driven by stronger attendance and higher revenue-per-patron metrics.
- Robust Attendance GrowthTheater attendance of 12.7 million guests, up 9.3% year-over-year (≈ +1.1 million guests), supporting box office and F&B growth.
- Strong EBITDA and Operating LeverageConsolidated adjusted EBITDA of $40.8 million, up 20.4% versus $33.9 million year-over-year, demonstrating operating leverage on revenue growth.
- Box Office and Per-Patron ImprovementsBox office revenue was $176.2 million, up 11.2% YoY (second-highest quarter since 2019). Box office revenue per patron reached $13.91 (up 1.7% YoY).
- Record Concession and Merchandise PerformanceTheater food service revenue hit an all-time quarterly record of $130 million, up 11.8% YoY. Concession revenue per patron reached an all-time quarterly record of $10.26 (up 2.2%). Merchandise sales grew ~45% YoY, contributing roughly one-third of CPP growth and generating about $4 million in sales for the quarter.
- Film Distribution Momentum (Cineplex Pictures)Michael became the highest grossing film ever distributed by Cineplex Pictures and was the second-highest grossing film at the box office in the quarter, reinforcing growth and scale in the distribution business; other upcoming distributed titles referenced as further growth drivers.
- Premium Formats and Content StrengthCompany noted the highest grossing week in its history (box office >20% ahead of prior record), strong performance from premium event films (Odyssey, Spider-Man) and continued demand for premium formats; Cineplex operates 8 of the world's 41 IMAX 70mm screens.
- Loyalty and Subscription EngagementSCENE+ launched nationwide with over 15 million members, expanding earning/redemption opportunities; CineClub exceeded 270,000 members with visitation ~4x higher than non-members, supporting repeat visitation and revenue.
- Improved Liquidity and Capital Allocation FlexibilityEnded the quarter with $116.8 million cash, no drawings on $100 million revolving facility and ~$92.5 million available after letters of credit; net capex Q2 $7 million with full-year 2026 guidance ~ $50 million and preliminary 2027 guidance ~ $60 million. Management noted leverage down ~1.5 turns over 18 months and target leverage 2.5–3.0x seen as achievable in the near term, enabling opportunistic buybacks or reintroduction of a dividend when metrics are met.
DE:CX0 Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Nov 05, 2026 | 2026 (Q3) | 0.27- | 0.01 | ― | ― |
| Aug 11, 2026 | 2026 (Q2) | 0.130.08 | -0.02 | 500.00% (+0.10) | |
| May 11, 2026 | 2026 (Q1) | -0.19-0.23 | -0.37 | 37.93% (+0.14) | |
| Feb 11, 2026 | 2025 (Q4) | 0.07-0.03 | 0.03 | -200.00% (-0.06) | |
| Nov 06, 2025 | 2025 (Q3) | 0.150.01 | -0.25 | 105.13% (+0.26) | |
| Aug 12, 2025 | 2025 (Q2) | 0.03-0.02 | -0.21 | 90.91% (+0.19) | |
| May 09, 2025 | 2025 (Q1) | -0.29-0.37 | -0.63 | 41.41% (+0.26) | |
| Feb 11, 2025 | 2024 (Q4) | 0.070.03 | -0.12 | 126.32% (+0.15) | |
| Nov 06, 2024 | 2024 (Q3) | 0.13-0.25 | 0.26 | -197.50% (-0.50) | |
| Aug 09, 2024 | 2024 (Q2) | -0.28-0.21 | 1.27 | -116.58% (-1.48) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
