

Agnico Eagle (AE9) Q3 2026 Earnings Report
DE:AE9 Q3 2026 EPS Results
- Actual EPS
- EUR 2.35
- Consensus EPS
- EUR 2.26
- Beat/Miss
- Beat by +EUR 0.09
- One Year Ago EPS
- EUR 1.93
DE:AE9 Q3 2026 Revenue Results
- Actual Revenue
- EUR 3.21B
- Expected Revenue
- EUR 3.20B
- Beat/Miss
- Beat by +EUR 12.77M
- YoY Revenue Growth
- +19.07%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 10/28/2026
- Time
- After Close
- Conference Call
- Wednesday, October 28, 2026
Agnico Eagle's next earnings date is estimated for February 18, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
Q3 2026 Earnings Slide Deck
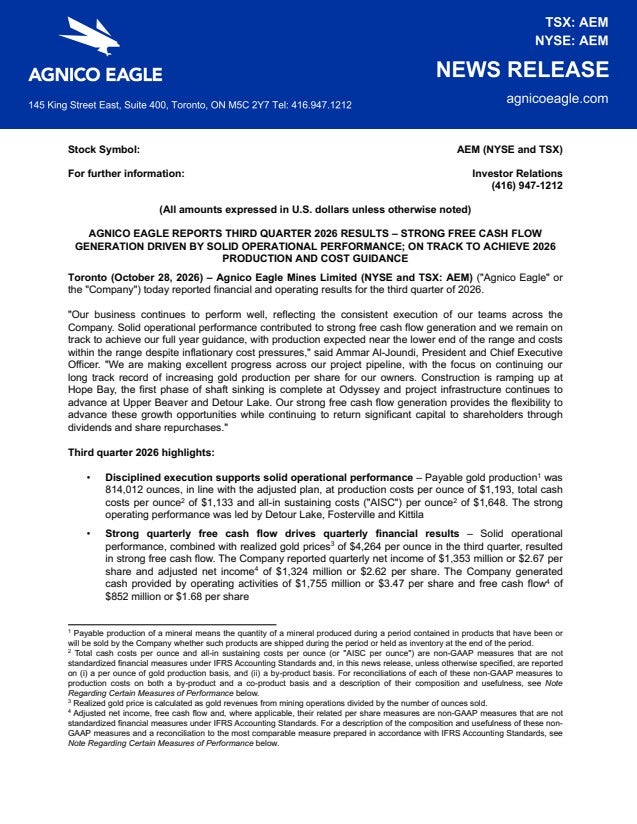
Q3 2026 Earnings Call Summary
The call was strongly positive, with solid production, strong cash flow and earnings, disciplined cost control relative to a difficult operating environment, a strengthened balance sheet, increased shareholder returns, and substantial progress across the growth and exploration pipeline. The main negatives were higher diesel, tariff, and consumable costs, Meadowbank grade and throughput issues, labor availability and housing challenges, and the lack of concrete near-term production replacement for Barnat ounces. Management nevertheless reaffirmed its full-year production and cost guidance and emphasized continued execution across its projects.
Agnico Eagle said it remains on track to deliver its full year 2026 production and cost guidance, albeit at the lower end and the upper end of production and costs, respectively, with year-to-date production of approximately 2.5 million ounces; it expects production growth of 20%-30% over the next decade and to above 4 million ounces per year, starting in the early to mid-2030s, while four projects are forecast to contribute an additional 1.3 million to 1.5 million ounces per year by the mid-2030s. The company expects project returns of approximately 25%-50% at current spot prices, now expects to return more than 50% of free cash flow to shareholders for the full year 2026, and said 50% is a reasonable threshold looking ahead to 2027, subject to the gold price and the needs of the business. Malartic remains on target for first production via the shaft in Q2 2027; the Detour bulk sample is expected to be completed by the first half of 2027, potentially enabling underground production as early as 2028, with a project outlook expected in 2027; and cost inflation guidance was not finalized, although $50-$60 an ounce of diesel impact was expected in Q4, as much as $80 an ounce for full year 2026, about a 7% increase, potentially year-over-year, and 5% or 6% was described as a reasonable assumption.
- Solid Third-Quarter Production and Guidance ExecutionGold production was 814,000 ounces, in line with the quarterly forecast and at the midpoint of adjusted production guidance. Year-to-date production was approximately 2.5 million ounces, positioning the company to achieve the lower end of its full-year production guidance.
- Strong Financial Results and Free Cash FlowThe company generated $852 million of free cash flow, approximately $1.3 billion of adjusted net income, or $2.62 per share, and approximately $2.5 billion of adjusted EBITDA in the third quarter. Gold prices averaged about $4,300 per ounce.
- Cost Discipline Despite Inflationary PressuresThird-quarter total cash costs were $1,133 per ounce and all-in sustaining costs were $1,648 per ounce. Year-to-date costs remained within the full-year guidance range, and the company continued to expect full-year costs to finish within the upper end of guidance despite industry-wide inflationary pressures.
- Strong Balance Sheet and Capital FlexibilityNet cash was approximately $3.4 billion at September 30. Management said the balance sheet provides flexibility to advance the growth pipeline while continuing to return capital to shareholders, and that the company can fund capital spending from operating cash flow while maintaining a defensively positioned balance sheet.
- Increased Shareholder Returns and Dividend Track RecordThe company returned approximately $478 million through dividends and share repurchases during the quarter, representing about 56% of free cash flow. Year-to-date shareholder returns represented 51% of free cash flow, above the initial 40% target, and full-year 2026 returns are now expected to exceed 50% of free cash flow at current spot gold prices. Agnico Eagle has paid a dividend for 43 consecutive years and has returned over $7 billion to shareholders since 1983.
- Large Long-Term Production Growth PipelineManagement is targeting production growth of 20%-30% over the next decade and production above 4 million ounces per year beginning in the early to mid-2030s. Detour Underground, the Malartic mill expansion, Hope Bay, and Upper Beaver are forecast to contribute an additional 1.3 million to 1.5 million ounces per year of long-life, high-margin production by the mid-2030s.
- High-Return Growth InvestmentsApproximately $1.6 billion of development capital had been invested year-to-date in Detour Lake, Odyssey, Hope Bay, and Upper Beaver. At current spot prices, management expects these projects to generate returns of approximately 25%-50% while supporting anticipated production growth of 20%-30% beginning in the early 2030s.
- Malartic Shaft and Infrastructure ProgressMalartic remained on target for first production via the shaft in Q2 2027, with more than 70% of construction completed. The first phase of shaft sinking reached 1.5 kilometers and was completed four months ahead of schedule. The operation complex and paste plant were completed, and the production hoist is now the focus as the project transitions from shaft sinking to production infrastructure.
- Hope Bay Construction and Logistics ProgressHope Bay detail engineering was 75% complete and construction reached 13% at the end of September. The new 37-megawatt power plant was under construction, with 25% of its structural steel completed by the time of the call. The sealift delivered 220,000 cubic meters of materials, equivalent to approximately 2,000-3,000 truckloads, on target and safely. A 4.2-megawatt wind turbine is expected to be ready in early 2028.
- Hope Bay Partnership and Permitting FrameworkThe company renewed its Inuit Impact and Benefit Agreement with the Kitikmeot Inuit Association, covering the entire 80-kilometer belt through 2056.
- Strong Performance at Detour, Macassa, and FostervilleThe Ontario, Australia, and Mexico regions exceeded their plans for the quarter. Detour benefited from improved productivity, mining in a high-grade portion of the deposit, and positive grade reconciliation. Macassa was in a higher-grade sequence and achieved mill optimization improvements, while Fosterville benefited from improved mine productivity and positive grade reconciliation at the Robbins Hill and Phoenix deposits.
- Detour Underground Development RecordDetour fully internalized development of the exploration ramp with support from Macassa, achieving a quarterly record in development performance. The exploration ramp and cross-cut toward the first mineralized zone are advancing from two active headings. The bulk sample is expected to be completed by the first half of 2027, supporting potential underground production from Domain 54 as early as 2028.
- Detour Expansion PotentialSince 2020, Detour has doubled mineral reserves and resources and increased mill throughput from 22 million tons per year to 28 million tons per year. The company is evaluating additional potential that could include higher milling capacity, a larger open pit, and a larger underground mine, with a project outlook expected in 2027.
- Upper Beaver Development ProgressThe Upper Beaver exploration ramp advanced more than 600 meters during the quarter, reached a depth of 210 meters, and achieved a fifth consecutive quarterly record in development performance. Shaft sinking reached just over 730 meters, with the 760 level and shaft station excavation expected to commence during the quarter.
- Robust Exploration Program and Reserve ReplacementThe company safely completed more than 330 kilometers of diamond drilling during the quarter, with more than 1.1 million meters completed year-to-date toward a 1.4 million-meter budget. Management said it was in a strong position to replace and grow global mineral reserves and resources, with anticipated additions at Malartic, Detour, and Hope Bay and positive replacement at Meliadine, Kittilä, and Macassa.
- Promising Exploration Results Across the PortfolioReported results included 2.8 grams per tonne over 34 meters at East Gouldie, 3.8 grams over 36 meters at Eclipse, and 9.5 grams over 18.9 meters at Artemis at Malartic; 11.9 grams over 5.4 meters and 19 grams over 26 meters at Detour; up to 8.5 grams over 8.6 meters and 37 grams over 2.8 meters at Hope Bay; and 11 grams over 12 meters and 17 grams over 4.5 meters at Boston.
- Early Ikkari and Helmi Exploration SuccessAt the recently acquired Finland project, drilling was ramping up from three rigs toward five or six rigs. At Helmi, an initial hole returned an uncapped average grade of 15 grams over 10 meters, or 3.2 grams capped, including a one-meter sample grading 185 grams. Management said Helmi remains wide open at depth and plans an aggressive drill program over the next three to five years.
- Operational Resilience at Barnat and KittiläAfter a rock movement at Barnat Pit on July 1, the team established a safe path forward within 24 hours, completed the plan on September 27 slightly ahead of schedule, and safely restarted mining. At Kittilä, the mill team achieved its highest monthly recovery in the last five years in September.
- Workforce Development and Recruitment InitiativesManagement reported low workforce turnover and no material labor-cost increases to date. The company has established a centralized recruitment hub, is accessing labor pools across Canada, using targeted immigration for difficult-to-fill trades, and developing skills programs that guarantee participants a job. Macassa also supported Detour by sending development miners and sharing skills.
DE:AE9 Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Feb 18, 2027 | 2026 (Q4) | 2.29- | 2.35 | ― | ― |
| Oct 28, 2026 | 2026 (Q3) | 2.262.35 | 1.93 | 21.26% (+0.41) | |
| Jul 29, 2026 | 2026 (Q2) | 2.622.74 | 1.72 | 59.40% (+1.02) | |
| Apr 30, 2026 | 2026 (Q1) | 2.842.96 | 1.36 | 117.59% (+1.60) | |
| Feb 12, 2026 | 2025 (Q4) | 2.342.35 | 1.14 | 105.43% (+1.21) | |
| Oct 29, 2025 | 2025 (Q3) | 1.791.93 | 1.02 | 90.06% (+0.92) | |
| Jul 30, 2025 | 2025 (Q2) | 1.561.72 | 0.95 | 81.09% (+0.77) | |
| Apr 24, 2025 | 2025 (Q1) | 1.231.36 | 0.67 | 103.94% (+0.69) | |
| Feb 13, 2025 | 2024 (Q4) | 1.081.14 | 0.49 | 132.12% (+0.65) | |
| Oct 30, 2024 | 2024 (Q3) | 0.911.02 | 0.39 | 161.35% (+0.63) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
