


Superior Plus earnings date
Superior Plus (8SP) Q3 2026 Earnings Report
DE:8SP Q3 2026 EPS Results
- Actual EPS
- -EUR 0.22
- Consensus EPS
- -EUR 0.24
- Beat/Miss
- Beat by +EUR 0.02
- One Year Ago EPS
- -EUR 0.37
DE:8SP Q3 2026 Revenue Results
- Actual Revenue
- EUR 337.45M
- Expected Revenue
- EUR 334.89M
- Beat/Miss
- Beat by +EUR 2.57M
- YoY Revenue Growth
- +14.32%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 11/10/2026
- Time
- After Close
- Conference Call
- Tuesday, November 10, 2026
Superior Plus's next earnings date is estimated for February 18, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q3 2026 Earnings Slide Deck
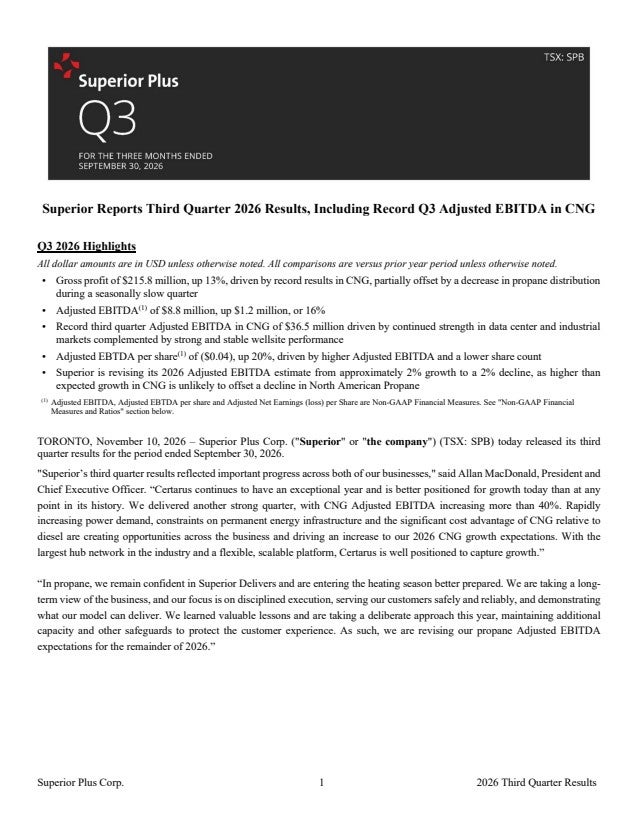
Q3 2026 Earnings Call Summary
The call was broadly positive, driven by record Certarus performance, strong CNG volume growth, expanding industrial and data center opportunities, operational improvements in propane and continued expected EBITDA growth in 2027. These positives were tempered by the revision of 2026 adjusted EBITDA guidance to approximately 2% contraction, weaker propane results, elevated customer attrition, negative free cash flow and temporarily higher leverage during the CNG investment period.
For 2026, Superior revised its adjusted EBITDA outlook from 2% growth to a 2% contraction, or a decline of approximately 2%; Certarus is expected to grow approximately 5%, versus the prior expectation that Certarus EBITDA would be down between 4% and 9%, while propane guidance was about down 5% this year. The company continues to expect adjusted EBITDA growth of 5% in 2027, and Grier said EBITDA is expected to grow by approximately 5% in 2027 off a lower 2026 EBITDA base. Superior expects full-year Superior Delivers contribution of approximately $30 million, remains confident in $75 million, expects 2026 capital expenditures of $230 million, and expects 2027 capital expenditures to remain at levels similar to 2026; it expects to exit 2026 with leverage of approximately 3.9x, with leverage in the zone, high 3s or 4-ish for probably the next 4 quarters, maybe 5 quarters.
- Consolidated EBITDA GrowthQ3 adjusted EBITDA increased 16% year over year to $8.8 million from $7.6 million. Adjusted EBITDA per share improved to a loss of $0.04 from a loss of $0.05, while adjusted net loss per share improved to $0.37 from $0.41.
- Certarus Delivered Record Q3 ResultsCertarus generated record third-quarter EBITDA of $36.5 million, up 42% from $25.7 million in the prior-year quarter. Volumes increased 23% to 8.7 million MMBtus, driven by growth across wellsite, industrial and data center segments.
- Strong Wellsite Performance and SafetyQ3 wellsite volumes reached 6.8 million MMBtus, up 21% year over year. Pricing remained stable for a fifth consecutive quarter, while margins and returns remained robust. The year-to-date recordable incident rate was lower than in each of the previous three years.
- Industrial Volume ExpansionCertarus industrial volumes increased 62% year over year, driven by new projects coming online, increased activity from existing customers and project extensions. The company said its industrial business base is becoming more stable and predictable, with a larger base of contracted revenue and greater visibility.
- Expected CNG Mix ShiftCertarus expects industrial and data center applications to represent approximately 60% of its CNG business within the next 24 months.
- Data Center Growth OpportunityManagement cited forecasts that nearly 30 gigawatts of behind-the-meter natural gas generation will be deployed by 2030, primarily supporting high-return AI data center projects. Certarus reported a healthy and growing data center opportunity pipeline and a good outlook into the fourth quarter and 2027.
- Expanded Certarus Hub NetworkWith new hubs in Florida, Utah, Houston and Bakersfield, California, Certarus is now within approximately 250 miles of 50% of the North American population and expects to reach approximately 80% by the end of 2028. The Bakersfield hub is expected to begin flowing gas in Q1 2027.
- Fleet Fueling ExpansionCertarus' first mobile CNG fleet-fueling location in Houston is operational and serves approximately 100 Class 8 natural gas trucks. The company also signed an MOU with Gazelle Transportation, California's largest crude hauler, to deploy mobile CNG fleet fueling at its facility.
- CNG Economic AdvantageManagement said diesel prices are more than $6 in many markets, while Certarus' delivered CNG price on a diesel-equivalent basis is often less than half that, citing lower fuel costs, greater price stability and practical refueling as key elements of the CNG proposition.
- Propane Operational ImprovementsSuperior strengthened forecasting and delivery planning, improved workforce readiness, enhanced coordination among field operations, supply and customer service, and launched a delivery tracker. Management reported improved route adherence and deliveries per room over the summer, along with a strong supply position entering the heating season.
- Superior Delivers ContributionSuperior Delivers contributed approximately $3 million of incremental adjusted EBITDA in Q3 and $20 million year to date. The quarterly contribution was primarily generated by margin optimization and more sophisticated supply management.
- Improved Canadian Customer Retention EffortsManagement said retention efforts in Canada had taken hold and produced encouraging results. The company also said it had learned more about the importance of customer experience, brand strength, lead generation and lead conversion in acquiring and retaining propane customers.
- Positive Certarus OutlookCertarus is now expected to grow adjusted EBITDA approximately 5% in 2026, compared with the previous expectation of a 4% to 9% decline. Management said the improved outlook reflects broad-based and durable growth across data centers, industrial markets and wellsite operations.
- 2027 EBITDA Growth ExpectedSuperior continues to expect adjusted EBITDA growth of approximately 5% in 2027, with slightly more of the expected growth coming from CNG and some growth from propane.
- Contracted CNG Investment ProgramThe company is continuing to invest in CNG growth, including mobile storage units and equipment supporting signed contracts. Management emphasized that the investments are primarily tied to contracted opportunities and are funded entirely from cash generated by the business.
- Leverage Improved Year Over YearLeverage at the end of Q3 was 3.8x, down one-tenth of a turn from a year ago, driven by lower net debt levels and higher adjusted EBITDA.
DE:8SP Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Feb 18, 2027 | 2026 (Q4) | 0.20- | 0.24 | ― | ― |
| Nov 10, 2026 | 2026 (Q3) | -0.24-0.22 | -0.37 | 40.00% (+0.15) | |
| Aug 06, 2026 | 2026 (Q2) | -0.17-0.23 | -0.23 | 0.00% (+0.00) | |
| Feb 19, 2026 | 2025 (Q4) | 0.170.24 | 0 | ― | |
| Feb 19, 2026 | 2026 (Q1) | 0.470.45 | 0.49 | -7.41% (-0.04) | |
| Nov 13, 2025 | 2025 (Q3) | -0.21-0.37 | -0.24 | -51.85% (-0.13) | |
| Aug 12, 2025 | 2025 (Q2) | -0.12-0.23 | -0.18 | -25.00% (-0.05) | |
| May 13, 2025 | 2025 (Q1) | 0.380.49 | 0.27 | 80.00% (+0.22) | |
| Feb 26, 2025 | 2024 (Q4) | 0.160.00 | 0.18 | -100.00% (-0.18) | |
| Nov 06, 2024 | 2024 (Q3) | -0.17-0.24 | -0.3 | 18.92% (+0.06) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
