

Superior Plus (8SP) Q2 2026 Earnings Report
DE:8SP Q2 2026 EPS Results
- Actual EPS
- -EUR 0.22
- Consensus EPS
- -EUR 0.17
- Beat/Miss
- Missed by -EUR 0.05
- One Year Ago EPS
- -EUR 0.22
DE:8SP Q2 2026 Revenue Results
- Actual Revenue
- EUR 386.19M
- Expected Revenue
- EUR 384.84M
- Beat/Miss
- Beat by +EUR 1.35M
- YoY Revenue Growth
- +2.86%
Earnings Announcement Details
- Quarter
- Q2 2026
- Date
- 08/06/2026
- Time
- After Close
- Conference Call
- Thursday, August 6, 2026
Superior Plus's next earnings date is estimated for November 10, 2026, based on past reporting schedules.
Q2 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q2 2026 Earnings Slide Deck
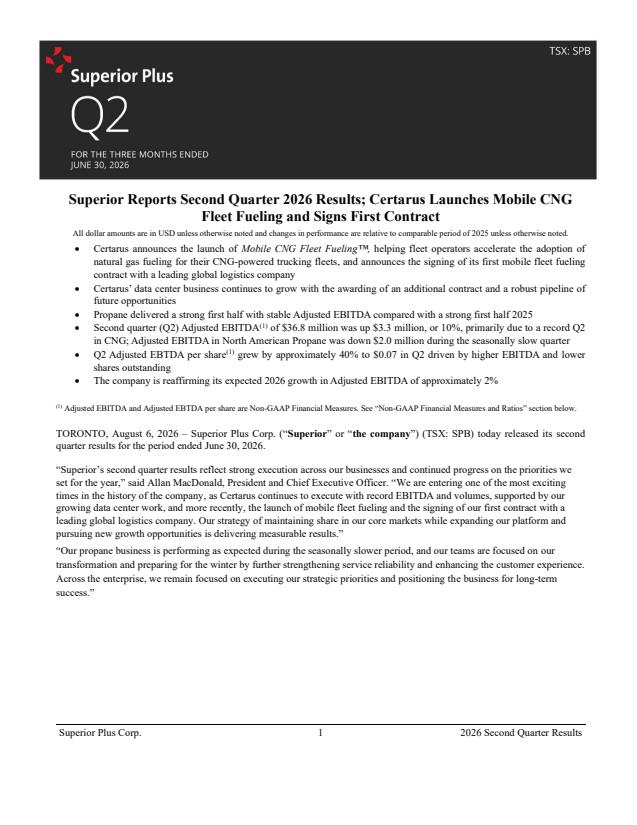
Q2 2026 Earnings Call Summary
The call conveyed a largely positive operational and strategic momentum driven by Certarus/CNG: record volumes, strong CNG EBITDA (+23%), industrial volumes up ~50%, expansion of the hub network to 23 hubs, launch of a new mobile fleet fueling vertical with an initial contract, and reaffirmed guidance for 2026 with expected stronger contributions in 2027. Offsetting risks include a weak U.S. propane quarter (U.S. propane EBITDA -$5.1M), negative free cash flow in Q2 (-$35M) due to growth CapEx, a planned increase in leverage to ~4.0x by year-end, and corporate cost pressures. Overall, the positive growth trajectory and high-return CNG opportunities appear to outweigh the near-term propane and cash flow headwinds, though execution and timing of data center conversions and elevated CapEx remain key risks.
Management reaffirmed 2026 guidance calling for ~2% EBITDA growth, maintained a $230 million consolidated CapEx plan for 2026 (Q2 CapEx was $37 million, up 23% YoY), and said CNG equipment spend will ramp in Q3–Q4 to service a large data‑center contract expected to commence in 2027; Certarus is expected to grow over the remaining six months of 2026 and Superior Delivers should meaningfully support propane results in Q4 2026; leverage was 3.6x at quarter end and is expected to rise to about 4.0x by year‑end (with a slight increase into Q3 as working capital builds); free cash flow was negative $35 million in Q2, and management expects approximately 5% YoY EBITDA growth in 2027 with 2027 CapEx to remain elevated at similar levels (update to the 2027 CapEx budget in February).
- Consolidated Adjusted EBITDA GrowthAdjusted EBITDA of $36.8 million in Q2, up approximately 10% year-over-year, driven by CNG/Certarus strength and Canadian propane performance.
- Adjusted EBITDA Per Share and Share Count ReductionAdjusted EBITDA per share grew ~40% year-over-year to $0.07, driven by higher EBITDA and fewer shares outstanding following prior buybacks (34 million shares repurchased since Nov 2024). Outstanding shares were 214.6 million at June 30, 2026 (down 4.5% YoY).
- Certarus / CNG Record Quarter and Strong GrowthCertarus delivered a record second quarter and first half volumes; CNG adjusted EBITDA was $33.6 million, up ~23% YoY, with industrial volumes up ~50% in Q2 and robust data center momentum driving growth.
- Data Center Opportunity Expansion and Contract WinsPipeline of prospective data center opportunities is substantially larger than a year ago; won an additional data center contract in the quarter and finalized agreements to secure additional MSUs to serve contracted demand through 2030.
- New Mobile Fleet CNG Fueling Vertical and First ContractLaunched mobile fleet CNG fueling business, opened new Houston CNG supply hub, and signed a 2-year contract to fuel ~100 Class 8 trucks (Houston flows expected to commence in Q3 2026) — providing a new, potentially permanent revenue vertical.
- Hub Network ExpansionExpanded North American hub network to 23 hubs (Utah went live in May; Houston opening this quarter; California planned later in 2026), increasing addressable market and enabling scale for mobile fleet and data center work.
- Canadian Propane OutperformanceCanadian propane adjusted EBITDA of $15.7 million in Q2, up ~25% YoY, driven by favorable carbon credit pricing, strong market differentials and improved procurement strategy.
- Capital Allocation and Growth Investment DisciplineCompany is funding growth CapEx (not maintenance) from cash flow to deploy mobile storage units and equipment for contracted CNG work; consolidated Q2 CapEx was $37 million (+23% YoY) and 2026 CapEx guidance reaffirmed at $230 million to support data center contracts.
- Improved Safety and Operational ReadinessCertarus reported its best safety record in recent history and the company highlighted operational improvements and strengthened forecasting, inventory and delivery planning across propane operations.
- Guidance Reaffirmed and 2027 OutlookReaffirmed 2026 EBITDA growth expectation of ~2% and expects ~5% year-over-year EBITDA growth in 2027 as new data center work begins contributing; CapEx expected to remain elevated into 2027 to facilitate CNG growth.
DE:8SP Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Nov 10, 2026 | 2026 (Q3) | -0.24- | -0.37 | ― | ― |
| Aug 06, 2026 | 2026 (Q2) | -0.17-0.22 | -0.22 | 0.00% (+0.00) | |
| Feb 19, 2026 | 2025 (Q4) | 0.170.24 | 0 | ― | |
| Feb 19, 2026 | 2026 (Q1) | 0.470.45 | 0.48 | -7.41% (-0.04) | |
| Nov 13, 2025 | 2025 (Q3) | -0.21-0.37 | -0.24 | -51.85% (-0.13) | |
| Aug 12, 2025 | 2025 (Q2) | -0.12-0.22 | -0.18 | -25.00% (-0.04) | |
| May 13, 2025 | 2025 (Q1) | 0.380.48 | 0.27 | 80.00% (+0.21) | |
| Feb 26, 2025 | 2024 (Q4) | 0.160.00 | 0.18 | -100.00% (-0.18) | |
| Nov 06, 2024 | 2024 (Q3) | -0.17-0.24 | -0.3 | 18.92% (+0.06) | |
| Aug 13, 2024 | 2024 (Q2) | -0.11-0.18 | -0.14 | -27.39% (-0.04) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
