

Swiss Water Decaffeinated Coffee Inc (7RD) Q3 2026 Earnings Report
DE:7RD Q3 2026 EPS Results
- Actual EPS
- EUR 0.06
- Consensus EPS
- EUR 0.08
- Beat/Miss
- Missed by -EUR 0.01
- One Year Ago EPS
- EUR 0.01
DE:7RD Q3 2026 Revenue Results
- Actual Revenue
- EUR 41.91M
- Expected Revenue
- EUR 40.31M
- Beat/Miss
- Beat by +EUR 1.60M
- YoY Revenue Growth
- +5.00%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 11/03/2026
- Time
- After Close
- Conference Call
- Tuesday, November 3, 2026
Swiss Water Decaffeinated Coffee Inc's next earnings date is estimated for March 18, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q3 2026 Earnings Slide Deck
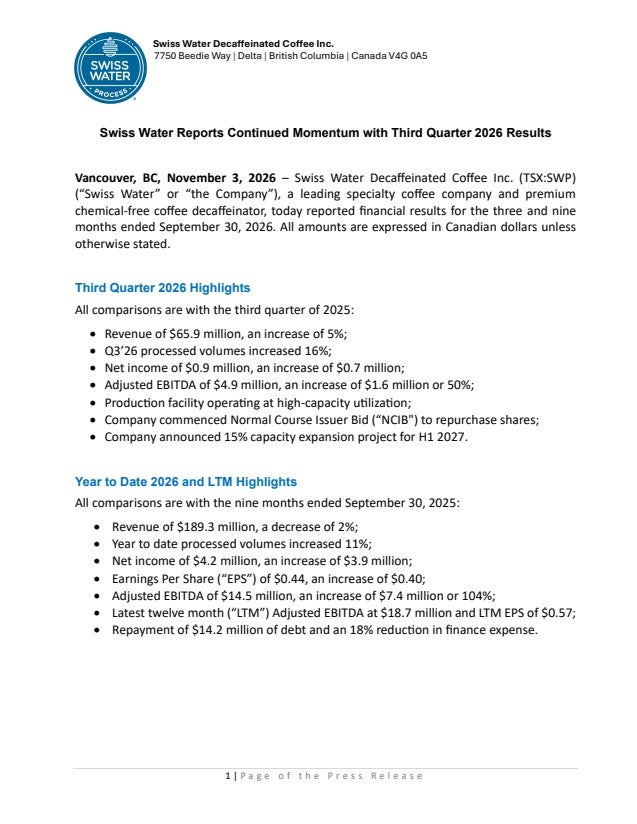
Q3 2026 Earnings Call Summary
The call was strongly positive overall. Volume growth, gross profit expansion, record trailing adjusted EBITDA, improved net income, operating cash generation, debt repayment, high utilization, extended order visibility, and planned capacity expansion significantly outweighed the lower nine-month revenue caused by lower coffee prices, higher operating expenses, quarterly risk management losses, lower quarter-end cash, and continued market volatility.
Swiss Water plans to invest approximately $6.2 million within its existing building to expand capacity by approximately 15%, expects to fund it primarily from internally generated cash flow, and expects to have capacity online in mid-2027; the expansion will increase capacity by roughly 15% for about 5% of what Delta originally cost, with one line expected to have about a 2-week shutdown within a normal maintenance window. Customers are booking into the first half of 2027, inventory volumes are expected to remain at or close to current levels in the near term, and the company is not forecasting kind of an additional pipeline fill or expecting a lot of additional coverage; as it looks into 2027, it is pricing as if and for a continued inversion.
- Processing Volume GrowthThird-quarter processing volumes increased 16% year-over-year and were up 11% for the first nine months of 2026. Growth was supported by established customers, healthy spot orders, and incremental volume from new customers.
- Strong Customer and Channel PerformanceThird-quarter shipments to importers increased 34% and shipments to roasters increased 3%. Specialty volumes rose 8%, while commercial volumes increased 24%.
- Third-Quarter Revenue GrowthQ3 revenue was $65.9 million, up 5% from $62.7 million in Q3 2025, driven by higher volumes and improved inversion expense recovery, partially offset by lower NY'C' Coffee futures prices.
- Significant Gross Profit ImprovementQ3 gross profit increased $3.6 million, or 55%, to $10.0 million from $6.4 million. The first-nine-month gross profit increased $9.1 million, or 48%, to $28.1 million, driven by higher volumes, improved inversion expense recovery, higher green coffee differential margins, operating efficiencies, lower utility usage and rates, and favorable foreign exchange.
- Record Adjusted EBITDAQ3 adjusted EBITDA was $4.9 million, up $1.6 million, or 50%, from $3.3 million in Q3 2025. First-nine-month adjusted EBITDA was $14.5 million, up $7.4 million, or 104%, and trailing 12-month adjusted EBITDA reached $18.7 million, the highest level in the company's history.
- Improved Net Income and Financing CostsQ3 net income increased to $900,000 from $200,000 in Q3 2025, while first-nine-month net income rose to $4.2 million from $400,000. Net finance expense decreased 21% in Q3 to $1.0 million and 24% year-to-date to $3.0 million, primarily because of lower average loan balances and more favorable variable interest rates.
- Debt Reduction and Balance Sheet ProgressDuring the first nine months, the company repaid $9.0 million on its operating credit facility, $4.2 million of construction debt, and $1.0 million on the EDC credit facility. The operating credit facility balance declined to $31.0 million at September 30 from $38.4 million at December 31, 2025, and the company was in compliance with all financial covenants.
- Strong Operating Cash GenerationNet cash generated from operating activities was $12.6 million for the first nine months, compared with $3.1 million in the first nine months of 2025. Management said cash generated by the business is funding both growth and debt reduction.
- Planned Capacity ExpansionThe company plans to invest approximately $6.2 million within its existing building to expand capacity by approximately 15%, with capacity expected to come online in mid-2027. The investment is expected to be funded primarily from internally generated cash flow and represents roughly 5% of what Delta originally cost.
- High Utilization and Extended Order VisibilityCapacity utilization was very high during the quarter, and customers are booking into the first half of 2027, providing visibility for production planning. Management said the order visibility is longer than it has historically been, primarily because existing customers are securing production capacity slots.
- Demand for Chemical-Free DecaffeinationManagement said the shift toward chemical-free decaffeination continues to gain ground, with U.S. regulators reviewing solvent-based processes, consumers increasingly reading labels, and large roasters asking about Swiss Water's capacity. The company said tight capacity in the chemical-free market is encouraging roasters to secure production slots.
- Customer Acquisition and Service ExecutionNewer customers added volume, smaller customers continued to provide additional new business, and management said the company is winning business competitively through strong service and logistics execution.
- Improved Coffee Market ConditionsThe NY'C' averaged USD 3.09 per pound in Q3, about 8% below the same period last year, while the first-nine-month average was USD 3.01 per pound, down 16% from USD 3.57 per pound. Management said lower prices and a narrowing inversion have given customers confidence to rebuild coverage, and the ordering environment is much stronger than it was throughout 2025.
- Operating Efficiency ImprovementsQ3 cost of sales declined slightly to $55.9 million from $56.3 million despite higher volumes. The decrease reflected lower NY'C' coffee futures prices, elimination of U.S. tariff expense, direct labor efficiencies, and lower utility usage and rates.
- Reduced Risk Management Losses Year-to-DateRisk management losses were $3.2 million for the first nine months, compared with $4.7 million in the prior-year period. Management said the market was substantially less inverted in 2026, particularly compared with the first half of 2025.
- Inventory and Carry-Cost StrategyInventory decreased $5.6 million, or 12%, from December 31, 2025, primarily because of the lower NY'C' value, while pounds held increased slightly. The company plans to maintain sufficient spot inventory for immediate customer needs and continue charging for the carry costs of holding and hedging that inventory.
- Brand and Marketplace ExpansionSwiss Water relaunched its U.S. online marketplace featuring brands that use its process, allowing consumers searching for the Swiss Water name to find customer products.
- Capacity Expansion Expected to Limit DisruptionManagement expects the expansion to require approximately a two-week shutdown on one line, which it said falls within a normal maintenance window and should allow the company to continue its ongoing capacity delivery.
- Foreign Exchange ManagementMost revenue is earned in U.S. dollars while a meaningful portion of costs is incurred in Canadian dollars. The company uses hedging tools to manage its underlying currency exposure.
- Lease Extension and Share RepurchaseThe company exercised an option to extend the lease on its Delta warehousing facility, adding $8 million to both right-of-use assets and lease liabilities as a noncash item. It also repurchased and canceled 3,000 common shares under its normal course issuer bid.
DE:7RD Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Mar 18, 2027 | 2026 (Q4) | 0.08- | 0.08 | ― | ― |
| Nov 03, 2026 | 2026 (Q3) | 0.080.06 | 0.01 | 400.00% (+0.05) | |
| Aug 05, 2026 | 2026 (Q2) | 0.030.13 | -0.06 | 300.00% (+0.19) | |
| May 06, 2026 | 2026 (Q1) | 0.030.09 | -0.04 | 333.33% (+0.13) | |
| Mar 12, 2026 | 2025 (Q4) | 0.020.08 | 0.13 | -38.10% (-0.05) | |
| Nov 06, 2025 | 2025 (Q3) | -0.040.01 | -0.05 | 125.00% (+0.06) | |
| Aug 06, 2025 | 2025 (Q2) | 0.01-0.06 | 0.04 | -242.86% (-0.11) | |
| May 07, 2025 | 2025 (Q1) | 0.02-0.04 | -0.06 | 38.78% (+0.02) | |
| Mar 12, 2025 | 2024 (Q4) | 0.030.13 | 0.07 | 101.92% (+0.07) | |
| Nov 05, 2024 | 2024 (Q3) | -0.02-0.05 | -0.03 | -77.78% (-0.02) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
