


Ag Growth International earnings date
Ag Growth International (7AG) Q3 2026 Earnings Report
DE:7AG Q3 2026 EPS Results
- Actual EPS
- EUR 0.11
- Consensus EPS
- EUR 0.39
- Beat/Miss
- Missed by -EUR 0.28
- One Year Ago EPS
- EUR 0.83
DE:7AG Q3 2026 Revenue Results
- Actual Revenue
- EUR 216.43M
- Expected Revenue
- EUR 216.04M
- Beat/Miss
- Beat by +EUR 391.54K
- YoY Revenue Growth
- -13.97%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 11/11/2026
- Time
- After Close
- Conference Call
- Wednesday, November 11, 2026
Ag Growth International's next earnings date is estimated for March 10, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q3 2026 Earnings Slide Deck
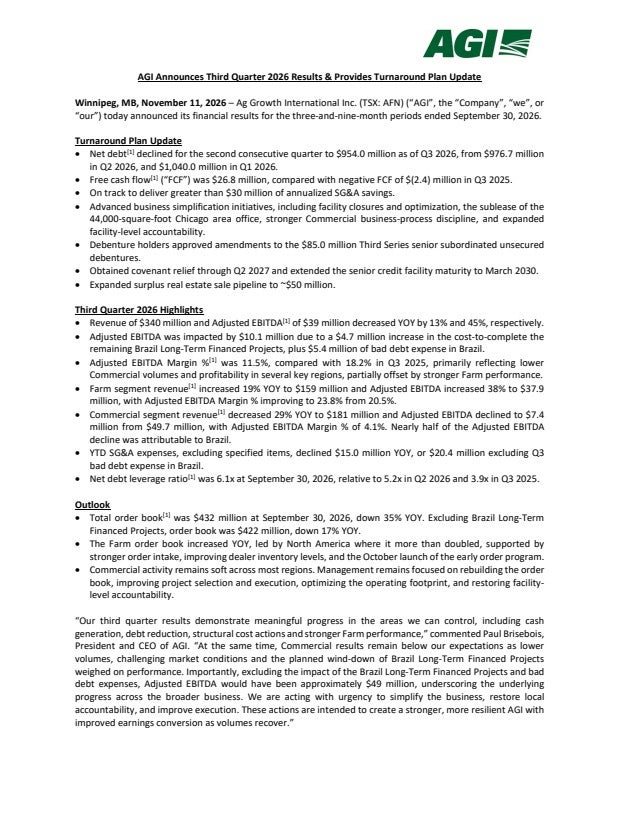
Q3 2026 Earnings Call Summary
The call was mixed. Farm performance showed strong growth, improving orders, better margins and positive cycle indicators, while cash generation, cost reduction, debt reduction and the nearest maturity extension represented measurable progress. However, Commercial results declined sharply, consolidated margins compressed, Brazil remains exposed to credit and revenue headwinds, leverage remains elevated and refinancing the 2027 debentures is unresolved. The positive Farm and restructuring developments were substantial but broadly offset by the continuing Commercial and balance-sheet challenges.
AGI expects the Commercial segment to remain under pressure due to geopolitical turmoil, the roll-off of the Brazil long-term finance projects and the final work through of lower-margin North America projects, while the Farm business will continue to show improvement, with further progress in the early order program primarily populating production schedules for the first half of 2027; the company remains on track to deliver more than $30 million of annualized structural cost savings, expects the Clay Center bin line to launch in the first quarter of 2027, anticipates the $50 million asset monetization to be finalized with the $50 million in hand by H1 of 2027, and expects Brazil to remain a headwind in 2027, with about $180 million of revenue to fill from a year-over-year gap.
- Strong Farm Segment GrowthFarm revenue increased 19% year-over-year to $159 million, driven by 23% growth in North America. Farm adjusted EBITDA rose 38% to $38 million, while margin expanded by more than 300 basis points to 23.8%, supported by higher volumes, disciplined pricing and a leaner cost base.
- Improving North American Farm Order BookThe North American Farm order book more than doubled year-over-year, with strength in both portable handling and permanent handling and storage products. The consolidated Farm order book was up roughly 65%, led by North America.
- Positive Farm Cycle IndicatorsDealer inventories continued to normalize, order intake stepped up meaningfully, and participation in the early order program launched in October was described as solid. Management said the evidence increasingly points to 2025 as the bottom for the Farm business, although recovery will depend on farmer sentiment.
- Farm Pricing Actions to Offset Steel CostsAGI implemented price increases across portable and permanent Farm products. Pricing on galvanized bin lines increased by approximately 10% to 15%, while portable line pricing increased by around 3% to 5%.
- Positive Free Cash Flow GenerationAGI generated $27 million, or approximately $26.8 million, of free cash flow in the third quarter versus a use of $2 million in the prior-year period. This was the company's second consecutive quarter of generating free cash flow, driven primarily by disciplined working capital management and strong North American collections.
- Cost Reduction ProgressYear-to-date SG&A declined by $15 million, or $20.4 million excluding the Brazil bad debt expense. AGI remains on pace to deliver more than $30 million of annualized structural cost savings.
- North American Commercial Quoting ImprovementSince July, approximately 60% of decided North American Commercial customer projects were won, above the company's 55% target. Compared with the first half of the year, average deal size increased by more than 20% and quoting activity increased by nearly 20%.
- Commercial Footprint SimplificationAGI closed or began closing several commercial facilities that were not economically viable at current volumes, consolidated activity into other plants, closed several subscale North American facilities and began subleasing its 44,000-square-foot Chicago-area office. Management said these actions remove current EBITDA drag and improve absorption and scale across fewer facilities.
- Clay Center Expansion On TrackThe new bin line at Clay Center remains on track to launch in the first quarter of 2027. Management described the project as a critical investment in a strategically important market and said it supports the effort to recapture U.S. storage volumes.
- Reduced Brazil Long-Term Finance ExposureAGI is completing its final Brazil long-term finance project, which is expected to end at the end of November, and does not plan to undertake additional projects of this type. Revenue from these projects declined 50% year-over-year, from the prior level discussed by management, while the related order book fell to under $10 million from $159 million a year ago.
- Lower Cash Investment in Brazil ReceivablesIncremental investment in non-current receivables was $17 million in the quarter versus $42 million a year ago. Management also referenced collecting more than $100 million from legacy project receivables in the prior quarter and said further cash investments should decline to nominal amounts.
- Debt Reduction and Maturity ExtensionNet debt declined for the second consecutive quarter to $954 million from $977 million in Q2 and just over $1 billion in Q1. AGI also extended the maturity of its $85 million third-series debentures from December 2026 to December 2030, addressing its nearest maturity.
- Covenant Relief and Liquidity PositionThe company obtained covenant relief and an extension of its senior credit facilities. At September 30, liquidity was approximately $78 million, consisting of $45 million of cash and $33 million of availability under senior credit facilities. Management said it was confident this was sufficient to manage cash needs and the normal Q1 working-capital buildup.
- Lower Maintenance Capital SpendingMaintenance capital expenditures were 0.5% of revenue, below AGI's historical range of 1% to 1.5%. Investment in intangibles also declined versus historical levels, while limited growth capital was concentrated primarily at the Clay Center bin line.
- Potential Additional Asset MonetizationAGI is progressing with a plan to monetize $50 million of assets, with small wins anticipated before year-end and additional wins before the end of Q1. Management's goal is to have the full $50 million in hand by the first half of 2027, and it also said other initiatives involving potential business-line sales were in progress.
DE:7AG Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Mar 10, 2027 | 2026 (Q4) | 0.18- | 0.06 | ― | ― |
| Nov 11, 2026 | 2026 (Q3) | 0.390.11 | 0.83 | -87.10% (-0.73) | |
| Jul 29, 2026 | 2026 (Q2) | 0.150.13 | 0.16 | -21.57% (-0.03) | |
| May 06, 2026 | 2026 (Q1) | -0.44-0.18 | -0.17 | -11.54% (-0.02) | |
| Mar 25, 2026 | 2025 (Q4) | 1.290.66 | 0.93 | -29.25% (-0.27) | |
| Jan 09, 2026 | 2025 (Q3) | 0.680.06 | 0.93 | -93.88% (-0.88) | |
| Jul 31, 2025 | 2025 (Q2) | 0.410.16 | 0.9 | -82.04% (-0.74) | |
| May 05, 2025 | 2025 (Q1) | -0.11-0.17 | 0.25 | -166.67% (-0.41) | |
| Mar 05, 2025 | 2024 (Q4) | 0.880.93 | 1.08 | -13.53% (-0.15) | |
| Nov 05, 2024 | 2024 (Q3) | 1.130.80 | 1.03 | -22.22% (-0.23) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
