


Extendicare earnings date
Extendicare (5XE) Q3 2026 Earnings Report
DE:5XE Q3 2026 EPS Results
- Actual EPS
- EUR 0.22
- Consensus EPS
- EUR 0.22
- Beat/Miss
- Missed by -EUR 0.00
- One Year Ago EPS
- EUR 0.18
DE:5XE Q3 2026 Revenue Results
- Actual Revenue
- EUR 396.18M
- Expected Revenue
- EUR 401.25M
- Beat/Miss
- Missed by -EUR 5.07M
- YoY Revenue Growth
- +42.60%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 11/05/2026
- Time
- After Close
- Conference Call
- Thursday, November 5, 2026
Extendicare's next earnings date is estimated for March 4, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q3 2026 Earnings Slide Deck
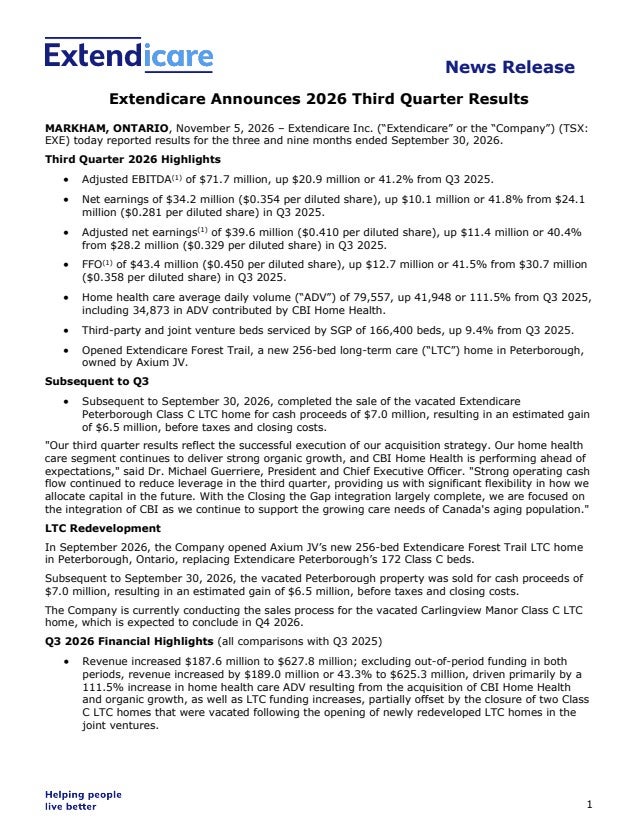
Q3 2026 Earnings Call Summary
The call was strongly positive overall. Extendicare reported substantial year-over-year growth in adjusted EBITDA, revenue, earnings, home health volumes, managed services, liquidity, and deleveraging, while its CBI acquisition and redevelopment program continued to advance. The main challenges were year-over-year Home Health margin pressure, expected moderation in market growth, uncertain Ontario rate timing, redevelopment delays, construction-cost and interest-rate uncertainty, and seasonal volatility. Management nevertheless characterized the company as financially flexible and maintained confidence in long-term demand and its growth opportunities.
Management expects underlying Home Health market growth to moderate over time to approximately 6% to 8% on an annualized basis, with funding increases substantially keeping pace with inflation and supporting NOI margins; it continues to expect annualized Managed Services margins of 50% to 55%. CBI finance and enterprise IT systems integration is expected to be completed by January 1, '27, with annualized synergies expected to total approximately $7.4 million by the time CBI is fully integrated in 2028, and synergies more reflective in '28 than in '27. Home Health is viewed as a 13% margin business with an opportunity to grow over time, 50 to another 100 basis points, over the next couple of years, not a 2027 thing. The company plans to open 4 new homes in 2027, bringing a further 832 beds online in the JV, with the next construction start targeted for spring 2027, and expects to review the dividend again early in the first quarter with year-end results.
- Strong Q3 Financial PerformanceAdjusted EBITDA was $71.7 million, up 41% year-over-year and ahead of consensus. Net earnings of $0.354 per diluted share increased 26% from the prior-year period.
- Revenue and Adjusted Earnings GrowthExcluding out-of-period impacts, consolidated Q3 revenue increased 43.3% to $625.3 million. Adjusted EBITDA increased 47.7% to $69.2 million, net earnings rose 41.8% to $34.2 million, and adjusted net earnings increased 40.4% to $39.6 million, or $0.41 per diluted share, up $0.08 year-over-year.
- Improved Funds From Operations and Payout RatioDiluted FFO per share, excluding out-of-period items, increased 35% year-over-year to $0.43, reducing the trailing 12-month payout ratio to 34%. Diluted FFO and AFFO were both approximately $0.45 per share in Q3; FFO increased nearly 26% and AFFO increased approximately 30% year-over-year.
- Debt Reduction and Strong LiquidityExtendicare paid down $53.7 million on its unsecured revolving credit facility during the quarter. Pro forma net debt to EBITDA improved to 2.3x, and the company ended Q3 with $246 million of liquidity, including $75 million of cash and $171 million available on its unsecured revolving facility.
- Home Health Volume GrowthHome health volumes increased 111.5% year-over-year including acquisitions. Excluding CBI, average daily volume increased 18.8%, driven by strong underlying market growth. Management said the company is accepting the vast majority of government referrals and that the growth reflects expansion of the overall home care sector rather than market-share gains.
- Home Health Margin Improvement and Long-Term OpportunityHome Health NOI margin was 13.1% in Q3 after removing out-of-period revenue, up 20 basis points from Q2. Management described the business as a 13% margin business with an opportunity to grow by another 50 to 100 basis points over the next couple of years, subject to volume growth, rate increases keeping pace with wage inflation, and CBI integration synergies.
- CBI Acquisition Outperforming UnderwritingCBI contributed $153.3 million of revenue and $20.3 million of NOI in Q3. During its first six months after closing, CBI was tracking approximately 23% ahead of original adjusted EBITDA underwriting and 25% ahead on volumes. CBI contributed $19.6 million to adjusted EBITDA excluding out-of-period items.
- Integration Progress and Expected SynergiesExtendicare is on track to substantially complete the Closing the Gap integration in 2026 and complete CBI finance and enterprise IT systems integration by January 1, 2027. Frontline CBI care-team integration is planned through 2027 using a phased approach, with expected annualized synergies of approximately $7.4 million when CBI is fully integrated in 2028.
- Long-Term Care PerformanceLong-term care occupancy remained strong, with Q3 NOI margins of 11.8% after removing out-of-period funding. Excluding out-of-period amounts, long-term care revenue increased by $1.7 million and NOI increased by $200,000, driven primarily by funding increases and improved occupancy.
- Managed Services Growth and High MarginsThe Managed Services segment delivered 9.4% year-over-year growth in the SGP customer base and NOI margins of 55.6%. Revenue increased by $1 million to $16.6 million and NOI improved by $300,000 to $9.2 million. Management continues to expect annualized margins of 50% to 55%.
- Redevelopment Program ExpansionExtendicare opened the 256-bed Extendicare Forest Trail home in Peterborough during the quarter. It subsequently sold the vacated Peterborough Class C home for $7 million in cash proceeds. Five projects are currently under construction, with plans to open four new homes in 2027 and bring 832 additional beds online in the joint venture.
- Additional Long-Term Care Development PipelineThe company continues to advance 17 additional projects at varying stages of planning and development under Ontario's Long-Term Care Home Capital development program. The next construction start is targeted for spring 2027, with additional starts planned later next year if conditions are favorable.
- Retroactive Alberta Funding IncreasesExtendicare received retroactive rate increases in Alberta for both long-term care and home health care. The Alberta home health increase was 3%, generating approximately $500,000 of out-of-period revenue and NOI impact in Q3, while the long-term care increase generated $2 million of out-of-period funding.
- New Adjusted Net Earnings DisclosureThe company introduced adjusted net earnings and adjusted earnings per share to remove nonrecurring and difficult-to-predict items, including legacy C-bed disposition gains and losses, gains on sales of redevelopment projects into Axium joint ventures, acquisition integration costs, and amortization of acquired intangibles.
- Capital Allocation FlexibilityManagement said its liquidity, low payout ratio, and conservative leverage provide flexibility for further acquisitions, dividend policy actions, and, where appropriate, share buybacks. Home health M&A remains a significant opportunity because the market is fragmented, and the company expects to review its dividend again early in the first quarter with year-end results.
- Broad Home Care Acquisition PipelineManagement is seeking growth platforms in new geographic markets and service lines rather than simply adding volume in existing districts. Potential targets may add personal support, nursing, therapy, allied services, new geographies, or specialized community services. Management noted that regional players similar to Closing the Gap and dozens of smaller niche businesses could fit the platform.
- Demographic and Unmet-Care Demand Supports GrowthManagement expects underlying home health market growth to moderate over time to approximately 6% to 8% annually, reflecting a 4% demographic growth trend and unmet care needs associated with a persistent shortfall in long-term care beds. Management also said the company remains the lowest-cost option for meeting the needs of the aging population.
- Operational Responsiveness and InnovationManagement said the company has cleared home care waiting lists across Ontario and is keeping up with demand from hospitals and doctors' offices. Governments and hospitals have responded positively to innovative service approaches, including CBI's specialized community services, and Extendicare is using its technology platforms to improve coordination with hospitals and physicians.
- Smooth Closing the Gap IntegrationManagement said the Closing the Gap integration proceeded without service interruptions or an increase in staff turnover and described the process as extremely smooth. The company plans to use the same integration playbook for CBI.
DE:5XE Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Mar 04, 2027 | 2026 (Q4) | 0.23- | 0.18 | ― | ― |
| Nov 05, 2026 | 2026 (Q3) | 0.220.22 | 0.18 | 25.98% (+0.05) | |
| Aug 06, 2026 | 2026 (Q2) | 0.250.20 | 0.24 | -14.48% (-0.03) | |
| May 07, 2026 | 2026 (Q1) | 0.130.27 | 0.11 | 139.77% (+0.16) | |
| Feb 26, 2026 | 2025 (Q4) | 0.170.18 | 0.15 | 24.35% (+0.04) | |
| Nov 11, 2025 | 2025 (Q3) | 0.120.18 | 0.12 | 47.89% (+0.06) | |
| Aug 06, 2025 | 2025 (Q2) | 0.110.24 | 0.18 | 28.62% (+0.05) | |
| May 06, 2025 | 2025 (Q1) | 0.100.11 | 0.09 | 17.33% (+0.02) | |
| Feb 27, 2025 | 2024 (Q4) | 0.110.15 | 0.06 | 130.00% (+0.08) | |
| Nov 12, 2024 | 2024 (Q3) | ―0.12 | 0.09 | 35.71% (+0.03) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
