


AutoCanada earnings date
AutoCanada (31K) Q3 2026 Earnings Report
DE:31K Q3 2026 EPS Results
- Actual EPS
- EUR 1.04
- Consensus EPS
- EUR 0.31
- Beat/Miss
- Beat by +EUR 0.73
- One Year Ago EPS
- -EUR 0.09
DE:31K Q3 2026 Revenue Results
- Actual Revenue
- EUR 787.55M
- Expected Revenue
- EUR 798.14M
- Beat/Miss
- Missed by -EUR 10.59M
- YoY Revenue Growth
- +3.14%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 11/12/2026
- Time
- After Close
- Conference Call
- Thursday, November 12, 2026
AutoCanada's next earnings date is estimated for March 4, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q3 2026 Earnings Slide Deck
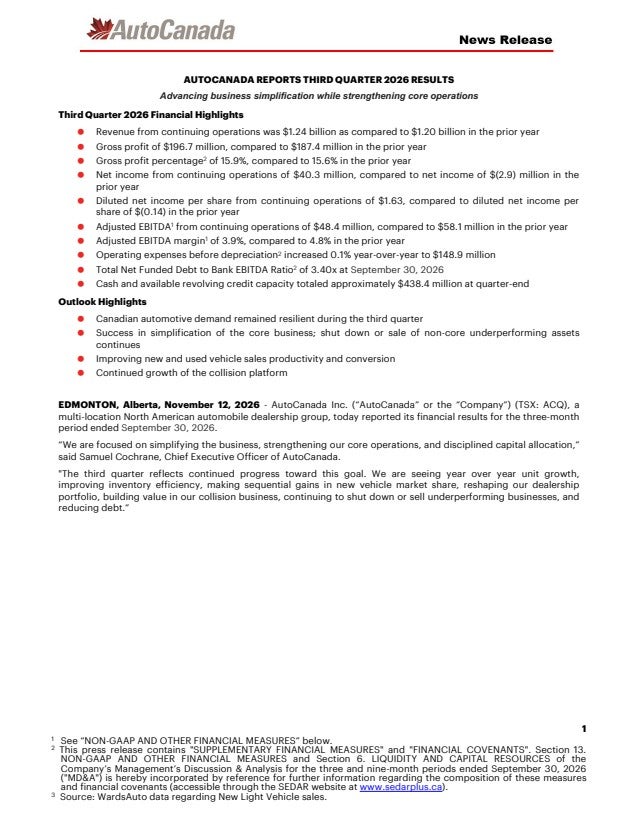
Q3 2026 Earnings Call Summary
The call was predominantly positive, with strong revenue and gross profit growth, a return to positive net income, 58.7% growth in ACX adjusted EBITDA, continued collision expansion, significant debt reduction, cleaner inventory, and ongoing operational simplification. These gains were tempered by margin pressure from affordability and tariffs, lower new vehicle GPUs, parts and service challenges, dealership profitability below expectations, leverage remaining above the 2 to 3x target range, and an ongoing strategic review of the collision business.
Management expects margins to begin to stabilize and then improve starting in the spring of 27, with used GPUs rebuilding as they head into 2027 and new GPUs improving as the Canadian backdrop improves and the new sales training programs launch; used margins should go up in 2027, although that increase could be impacted by the macro. The company remains focused on reducing leverage toward its target leverage range of 2 to 3x total net funded debt to bank EBITDA, directing proceeds from the remaining U. S. Divestitures toward debt reduction, and expects used inventory to creep up a little over winter ahead of March while remaining cautiously optimistic. In collision, the 10 shops added since Q3 25 are expected at maturity to add an additional $7.1 million of annual post rent EBITDA, acquisitions historically bought at 6 to 8x on a post rent EBITDA multiple are earned down to 3 to 4x, this has taken up to 3 years to mature, another 1 may close before the end of this year, and more are expected in the New Year.
- Revenue and Gross Profit GrowthRevenue from continuing operations increased 3.1% year over year to $1.2 billion in Q3 2026, while gross profit increased 4.9% to $197 million. Gross profit percentage increased 30 basis points to 15.9%, primarily reflecting strength in collision and used vehicle sales.
- Return to Positive Net IncomeNet income from continuing operations was $40.3 million, or $1.63 per diluted share, compared with a loss of $2.9 million, or negative $0.14 per diluted share, in the prior year.
- Improved Finance and Insurance PerformanceFinance and insurance gross profit increased 5.5%, and average gross profit per retail unit increased to $3.38 thousand from $3.35 thousand in the prior year, reflecting stronger dealership execution and improved product penetration.
- Used Vehicle Revenue and Unit GrowthUsed vehicle revenue increased 6.9%, supported by a 7.4% increase in retail units, while average selling price decreased 0.4%.
- Used Inventory CleanupUsed inventory aged over 90 days was reduced from 34% to 22% at the end of Q3. Management said used inventory is in a much cleaner position, with the company selling 50% of its used inventory every month and turning inventory faster.
- Market Share Gains by Owned BrandsManagement stated that the dealership business gained market share for four consecutive months when adjusted for the brands AutoCanada owns and operates.
- Collision EBITDA Growth and ExpansionACX adjusted EBITDA increased 58.7% year over year. Since Q3 2025, AutoCanada has added 10 collision shops that are expected at maturity to contribute an additional $7.1 million of annual post-rent EBITDA.
- Collision Organic and Inorganic GrowthManagement said the collision business continues to win market share, grow organically, and complete acquisitions and integrations at pace. The business has a national platform, a full acquisition pipeline, and may close another acquisition before the end of 2026.
- Debt Reduction and Lower LeverageNet debt declined 25% from $427 million in Q4 2025 to $322 million at the end of Q3 2026. Total net funded debt was $362 million at quarter-end, down from $412 million in Q2, and the total net funded debt-to-bank EBITDA ratio decreased to 3.4x from 3.6x in Q2 and 4.0x at the end of Q1.
- Improved Cash PositionCash at the end of Q3 was $171 million, compared with $142 million at the end of Q2, supported by proceeds from divestitures and sequential improvements in net working capital.
- Simplification of the BusinessAutoCanada unwound the Used Digital Limited partnership, which management said will save approximately $6 million annually and free management time to focus on core operations.
- Portfolio OptimizationAutoCanada sold three dealerships in British Columbia that had collectively lost $1.1 million in adjusted EBITDA year to date. Management said the company is reshaping the portfolio by moving capital from dealerships that do not meet required returns into dealerships that meet its long-term investment criteria.
- Inventory and Operating EfficiencyManagement said new and used inventory levels are well below historical company levels and are turning faster. Used inventory is expected to increase somewhat over the winter ahead of the March selling season, while the company intends to maintain cautious inventory levels.
- Technology and Sales Training InvestmentsAutoCanada is investing in in-house technology, including AI-based performance management tools, as well as standardized OEM-specific sales training. Management expects these initiatives to help maintain volumes, improve sales consistency, and rebuild margins.
- Parts and Service Hiring InitiativesThe company appointed Gary McDonald to lead its fixed operations strategy and added dedicated recruiters focused on hiring dealership technicians. Management said demand is present and that improved technician recruiting and BDC effectiveness should support future performance.
- Capital Allocation FrameworkCapital allocation priorities are to protect liquidity and financial flexibility, invest in high-return operational initiatives, pursue selective accretive acquisitions when returns and balance sheet capacity support them, and consider share repurchases where appropriate.
- Remaining U.S. Divestiture ValueManagement said the remaining U.S. divestitures are progressing well and include approximately $15 million to $16 million of land value in Canadian dollars, in addition to value from the remaining auto malls and franchises. Proceeds are intended to support debt reduction.
- Talent Development and RetentionManagement highlighted the recruitment and retention of talent, including Ethan Almeida, who won gold in body repair at Skills Canada and represented Canada at World Skills in Shanghai, and Casey Foy, who won gold in refinish repair at Skills Canada.
DE:31K Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Mar 04, 2027 | 2026 (Q4) | 0.20- | -0.04 | ― | ― |
| Nov 12, 2026 | 2026 (Q3) | 0.311.04 | -0.09 | 1264.29% (+1.12) | |
| Aug 12, 2026 | 2026 (Q2) | 0.420.29 | 0.46 | -36.11% (-0.17) | |
| May 13, 2026 | 2026 (Q1) | -0.14-0.10 | 0.24 | -140.54% (-0.33) | |
| Mar 18, 2026 | 2025 (Q4) | 0.30-0.04 | 0.2 | -119.54% (-0.23) | |
| Nov 13, 2025 | 2025 (Q3) | 0.54-0.09 | 0.16 | -156.00% (-0.25) | |
| Aug 13, 2025 | 2025 (Q2) | 0.350.46 | -0.93 | 148.98% (+1.39) | |
| May 14, 2025 | 2025 (Q1) | 0.040.24 | -0.06 | 470.00% (+0.30) | |
| Mar 19, 2025 | 2024 (Q4) | 0.040.20 | -0.51 | 137.90% (+0.71) | |
| Nov 13, 2024 | 2024 (Q3) | -0.010.16 | 0.51 | -69.14% (-0.36) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
