


Doman Building Materials Group earnings date
Doman Building Materials Group (2CW) Q3 2026 Earnings Report
DE:2CW Q3 2026 EPS Results
- Actual EPS
- EUR 0.14
- Consensus EPS
- EUR 0.11
- Beat/Miss
- Beat by +EUR 0.03
- One Year Ago EPS
- EUR 0.13
DE:2CW Q3 2026 Revenue Results
- Actual Revenue
- EUR 532.29M
- Expected Revenue
- EUR 530.57M
- Beat/Miss
- Beat by +EUR 1.71M
- YoY Revenue Growth
- +5.86%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 11/06/2026
- Time
- After Close
- Conference Call
- Friday, November 6, 2026
Doman Building Materials Group's next earnings date is estimated for March 11, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q3 2026 Earnings Slide Deck
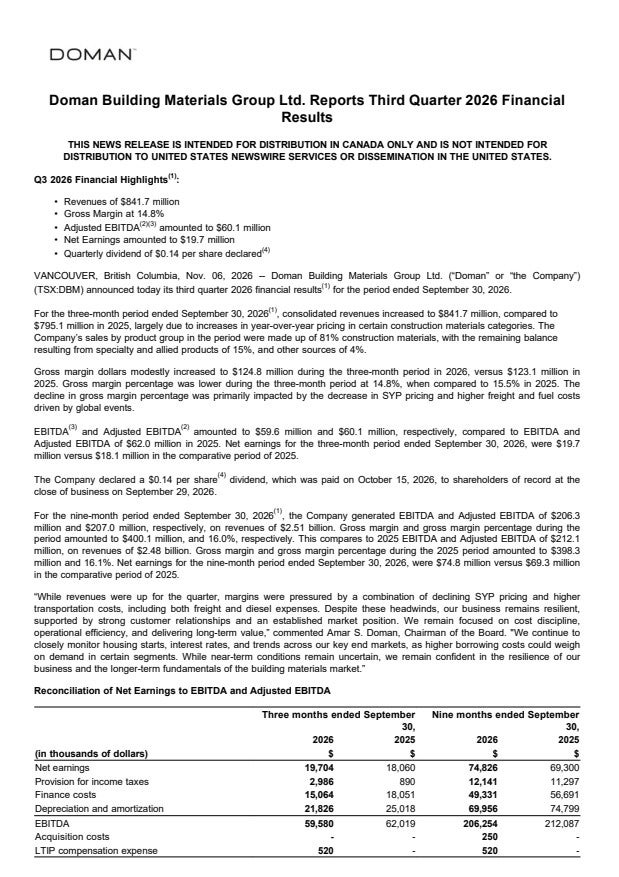
Q3 2026 Earnings Call Summary
The call reflected a resilient but challenging quarter. Sales and net earnings increased, gross margin dollars remained stable, Canada improved, shareholder returns continued and management maintained its acquisition and operational investment plans. However, adjusted EBITDA, gross margin percentage and operating cash flow declined, while weak lumber pricing, higher freight and fuel costs, soft U.S. demand, higher interest rates and incomplete cost pass-through remained significant challenges. Overall, the positive operating achievements and strategic initiatives were balanced by notable near-term market and profitability pressures.
The company will not provide guidance regarding future earnings; capital expenditures are generally expected to remain below 1% of annual revenues, with no changes anticipated in the near term to the current dividend level. Management expects fencing expansion to be more apparent next spring and said it will be a 2027 story, is looking at 1 to 2 upgrades in the U.S. at its sawmills, and is hoping to achieve better fuel-cost recoveries by the end of Q4 or even a bit sooner in December.
- Sales GrowthThird-quarter sales were $841.7 million versus $795.1 million in 2025, an increase of $46.6 million or 5.9%, largely due to higher year-over-year commodity pricing in certain U.S. construction material categories.
- Improved Net EarningsNet earnings increased to $19.7 million from $18.1 million, an increase of $1.6 million. Results benefited from lower finance costs and depreciation and amortization, partially offset by higher income tax expense.
- Stable Gross Margin DollarsGross margin dollars increased modestly to $124.8 million from $123.1 million in the prior-year quarter despite lower lumber pricing and higher freight and fuel costs.
- Lower Finance and Depreciation CostsFinance costs declined to $15.1 million from $18.1 million, a decrease of $3.0 million or 16.6%, primarily due to lower interest rates on loans and borrowings. Depreciation and amortization declined to $21.8 million from $25.0 million, a decrease of $3.2 million or 12.8%, mainly due to asset dispositions and assets becoming fully amortized.
- Lower Operating Expenses as a Percentage of SalesExpenses after gross margin increased 1.2% to $87.1 million from $86.1 million, but declined to 10.3% of sales from 10.8% in the prior-year quarter.
- Improved Canadian PerformanceManagement said Canada picked up significantly in the second half of the quarter and was tracking closer to, or slightly ahead of, plan.
- Diversified Business FoundationManagement highlighted the company's broad product offering, diversified product mix, broad geographic footprint, established customer relationships, distribution network and experienced management team as supporting its ability to navigate uneven demand.
- Shareholder Returns MaintainedThe company returned $36.9 million to shareholders through its established dividend program during the first nine months. Management said the current dividend level remains aligned with capital allocation objectives, with no changes anticipated in the near term.
- CEO Share Purchase PlanEffective December 2026, the CEO established an automatic securities purchase plan under which 100% of his net after-tax base salary will be used to purchase Doman common shares in the open market.
- Employee Equity IncentivesThe company's RSU, PSU and DSU plan was approved at the annual general meeting, and awards were issued to employees during the quarter. Management said the plan is intended to keep key employees motivated and aligned with the business.
- Strategic Acquisition ActivityManagement said debt ratios are improving and that the company continues to have regular conversations regarding acquisition opportunities. It stated that Doman is not stopping its growth trajectory and remains in growth mode.
- Fencing Expansion ProgressProduction at the new Estelle sawmill is ramping up very well, with good customer reception and additional demand. Management said the benefits of the fencing expansion should be more apparent in spring 2027, while upgrades at other mills will continue.
- Operational Efficiency InvestmentsThe company is considering one to two upgrades at U.S. sawmills in Arkansas and potentially Texas. Management said prior upgrades have progressed well after initial start-up issues and that production is now coming out very nicely.
- Capital Investment and Covenant ComplianceThe company invested $25.6 million in property, plant and equipment during the first nine months, versus $14.7 million in 2025, primarily due to a strategic land acquisition. Excluding that investment, capital expenditures remained modest and are generally expected to remain below 1% of annual revenues. The company was not in breach of any lending covenants during the period.
- Procurement and Integration ProgressManagement said further integration of previous acquisitions and greater scale in ancillary products and supplies are producing some progress, although nothing expected to move results materially; it described the benefit as picking up a few points.
- U.S.-Made Supply Chain PositioningManagement said strong tariffs on South American material are encouraging suppliers to seek a more orderly American-made supply chain, which it said should benefit Doman's U.S. strategy.
DE:2CW Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Mar 11, 2027 | 2026 (Q4) | 0.01- | 0.08 | ― | ― |
| Nov 06, 2026 | 2026 (Q3) | 0.110.14 | 0.13 | 4.76% (+0.01) | |
| Aug 05, 2026 | 2026 (Q2) | 0.200.23 | 0.2 | 12.50% (+0.03) | |
| May 08, 2026 | 2026 (Q1) | 0.090.17 | 0.17 | 0.00% (+0.00) | |
| Mar 05, 2026 | 2025 (Q4) | 0.040.08 | 0.06 | 30.00% (+0.02) | |
| Nov 06, 2025 | 2025 (Q3) | 0.090.13 | 0.11 | 16.67% (+0.02) | |
| Aug 06, 2025 | 2025 (Q2) | 0.140.20 | 0.12 | 68.42% (+0.08) | |
| May 08, 2025 | 2025 (Q1) | 0.060.17 | 0.1 | 68.75% (+0.07) | |
| Feb 27, 2025 | 2024 (Q4) | 0.060.06 | 0.08 | -16.67% (-0.01) | |
| Nov 07, 2024 | 2024 (Q3) | 0.080.11 | 0.15 | -25.00% (-0.04) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
