


Chorus Aviation earnings date
Chorus Aviation (CHRRF) Q3 2026 Earnings Report
CHRRF Q3 2026 EPS Results
- Actual EPS
- $0.48
- Consensus EPS
- $0.40
- Beat/Miss
- Beat by +$0.07
- One Year Ago EPS
- $0.42
CHRRF Q3 2026 Revenue Results
- Actual Revenue
- $242.83M
- Expected Revenue
- $233.72M
- Beat/Miss
- Beat by +$9.12M
- YoY Revenue Growth
- +6.97%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 11/09/2026
- Time
- After Close
- Conference Call
- Monday, November 9, 2026
Chorus Aviation's next earnings date is estimated for February 17, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q3 2026 Earnings Slide Deck
Q3 2026 Earnings Call Summary
The call was predominantly positive, with increased 2026 guidance, strong non-CPA growth expectations, successful acquisitions, improved leverage, substantial liquidity, shareholder returns, and progress across the operating businesses. These positives outweighed the year-over-year declines in adjusted EBITDA and free cash flow, contractual CPA step-downs, the need to refinance the Series C debentures, and uncertainty around the timing of defense contract wins.
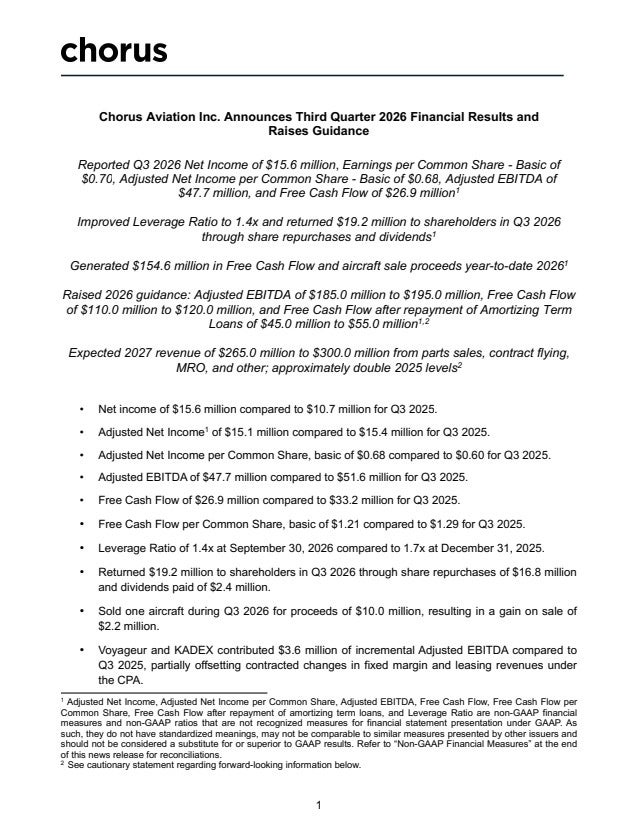
For 2026, Chorus expects adjusted EBITDA of $185 million to $195 million, free cash flow of $110 million to $120 million, and, after $65 million of scheduled amortizing term loan repayments, between $45 million and $55 million of free cash flow after debt repayments; non-CPA revenue is expected to be from $200 million to $220 million, growing to $265 million to $300 million in 2027, with a combined EBITDA margin of approximately 20%, while non-CPA business is seeing 5% to 10% growth annually. Between 2026 and 2029, Chorus expects to generate $500 million to $550 million of free cash flow and proceeds from aircraft sales, with a mid-teen unlevered return target on investments; its capital allocation plan includes up to $100 million in share buybacks, $40 million in dividends, $190 million of amortizing term loan repayments, and $170 million to $220 million of flexible capital allocation. The 2027 outlook includes no major contract win forecasted, reflects current run rate plus some reasonable growth and continued execution, and Chorus is hopeful and optimistic that it will win a contract or 2; SkyCare is expected to require nothing other than ordinary maintenance CapEx.
- Strong Non-CPA Revenue Growth OutlookNon-CPA revenue from parts sales, contract flying, MRO, and other activities is expected to increase from $135 million in 2025 to $265 million to $300 million in 2027, representing more than a doubling in 2 years. For 2026, non-CPA revenue is expected to be $200 million to $220 million, with a combined EBITDA margin of approximately 20%.
- SkyCare Air Ambulance Acquisition CompletedChorus closed the SkyCare Air Ambulance acquisition on November 1 for a purchase price of approximately $40 million, representing a purchase multiple of 4.5x SkyCare's unaudited 2025 EBITDA. SkyCare adds 22 aircraft, air ambulance capabilities, a northern-based operating platform, and potential cross-revenue opportunities with Voyageur, Ellison, CDx, and Signet.
- Updated 2026 Guidance IncreasedChorus increased its 2026 outlook to adjusted EBITDA of $185 million to $195 million and free cash flow of $110 million to $120 million. After $65 million of scheduled amortizing term loan repayments, expected free cash flow after debt repayments is between $45 million and $55 million. The increase reflects the SkyCare acquisition, stronger earnings, and the higher U.S. dollar exchange rate reflected in year-to-date results.
- Quarterly Earnings Per Share GrowthAdjusted net income per common share was $0.68, up 13% from $0.60 in Q3 2025. Adjusted net income was $15.1 million, flat year-over-year, as a $2.2 million aircraft sale gain and lower depreciation and interest offset lower adjusted EBITDA.
- Improved Leverage and Strong LiquidityThe leverage ratio improved to 1.4x from 1.7x at year-end and 1.5x in the prior quarter, remaining within the target range of 1 to 2x. Liquidity was $217.7 million as of September 30, including $27.2 million of cash and $190.5 million of available credit.
- Significant Shareholder ReturnsChorus returned $19.2 million to shareholders during the quarter through dividends and share repurchases, including a quarterly dividend of $0.11 per share and $16.8 million of NCIB repurchases. Year-to-date shareholder returns totaled $44.3 million, while approximately $120 million has been returned through the SIB and NCIB programs over the past 2.5 years.
- Continued Share RepurchasesDuring the quarter, Chorus repurchased and canceled approximately 615,000 common shares for $16.8 million. Year-to-date NCIB repurchases totaled approximately 1.46 million shares for $36.8 million, reducing weighted average shares by about 13% quarter-over-quarter.
- Aircraft Monetization ProgressChorus sold one additional Dash 8-400 aircraft during the quarter for proceeds of $10 million, generating a $2.2 million gain on sale. Eight of nine aircraft under the previously announced sales agreement have now been sold, including seven in 2026 for total year-to-date proceeds of $68.4 million. The remaining aircraft is expected to close by year-end, bringing expected cumulative net proceeds of the nine aircraft to slightly above the previously communicated USD 62 million.
- Long-Term Free Cash Flow and Capital Allocation FlexibilityBetween 2026 and 2029, Chorus expects to generate $500 million to $550 million of free cash flow and proceeds from aircraft sales. The capital allocation plan includes up to $100 million in share buybacks, $40 million in dividends, $190 million of amortizing term loan repayments, and $170 million to $220 million of flexible capital allocation. Chorus continues to target a mid-teen unlevered return on investments.
- CDx Delivering Above-Platform DiversificationCDx contributed approximately $17.7 million of revenue and $0.8 million of net income in the third quarter, including $0.5 million of amortization of acquisition-related intangible assets. Since its April 1 acquisition, CDx has contributed $34.1 million of revenue and $2 million of net income, with earnings described as being in line with the acquisition plan.
- Voyageur Parts Sales and Operational ProgressVoyageur and CDx produced $3.6 million more in the quarter on higher parts sales. Voyageur had a strong year in parts sales and continued progress across aerial firefighting, defense, and aircraft parts sales. Voyageur also completed the sale of two Dash 8-100 aircraft.
- Firefighting and Defense Programs AdvancingVoyageur's first Fire Swift aircraft is operational and has completed demonstration flights and static displays for provincial and federal stakeholders across Canada. A second Fire Swift aircraft is expected to be delivered in the fourth quarter. The Flex rotor uncrewed aircraft system continues to advance through business development, regulatory approvals, and training, with an operational launch planned for spring 2027.
- Jazz Safety and Labor MilestonesJazz successfully renewed its IOSA certification in September. New collective agreements were ratified with flight dispatchers, crew schedulers, and flight attendants, representing nearly 1,000 employees and providing greater certainty for employees and the business.
- Signet Training Platform ExpansionSignet's new North Bay base is open and training is underway, increasing training capacity and establishing a new presence in Northern Ontario. Its 12th cohort began training, four first officers have been delivered to Jazz, and Signet graduated its first free agent candidate in September.
- Ellison Contract Progress and Broader CapabilitiesEllison is progressing on its contract with the government of Quebec involving air ambulance modifications to a Challenger 600 series aircraft, with completion expected in the fourth quarter. Voyageur and Ellison are expanding their combined engineering, systems integration, and aircraft modification capabilities.
- Strong M&A Pipeline and Organic Growth OpportunitiesManagement said the pipeline of acquisition opportunities remains strong and includes businesses that fit its return metrics and strategic criteria. In the non-CPA business, management is seeing 5% to 10% annual growth, with additional potential from defense, aerial firefighting, and other opportunities not included in the current outlook.
CHRRF Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Feb 17, 2027 | 2026 (Q4) | 0.48- | 0.4 | ― | ― |
| Nov 09, 2026 | 2026 (Q3) | 0.400.48 | 0.42 | 13.33% (+0.06) | |
| Aug 04, 2026 | 2026 (Q2) | 0.370.58 | 0.46 | 25.76% (+0.12) | |
| May 07, 2026 | 2026 (Q1) | 0.320.38 | 0.4 | -5.26% (-0.02) | |
| Feb 12, 2026 | 2025 (Q4) | 0.440.40 | 0.27 | 46.15% (+0.13) | |
| Nov 06, 2025 | 2025 (Q3) | 0.390.42 | 0.29 | 42.86% (+0.13) | |
| Aug 05, 2025 | 2025 (Q2) | 0.410.46 | 0.05 | 842.86% (+0.41) | |
| May 06, 2025 | 2025 (Q1) | 0.380.40 | 0.29 | 35.71% (+0.11) | |
| Feb 20, 2025 | 2024 (Q4) | 0.350.27 | 0.25 | 11.43% (+0.03) | |
| Nov 06, 2024 | 2024 (Q3) | 0.080.29 | 0.29 | 0.00% (+0.00) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
