


Leonteq AG earnings date
Want to see CH:LEON full AI Analyst Report?
Leonteq AG (LEON) Q2 2026 Earnings Report
CH:LEON Q2 2026 EPS Results
- Actual EPS
- CHF 0.71
- Consensus EPS
- CHF 0.60
- Beat/Miss
- Beat by +CHF 0.11
- One Year Ago EPS
- CHF 0.53
CH:LEON Q2 2026 Revenue Results
- Actual Revenue
- CHF 113.66M
- Expected Revenue
- CHF 111.85M
- Beat/Miss
- Beat by +CHF 1.81M
- YoY Revenue Growth
- -13.16%
Earnings Announcement Details
- Quarter
- Q2 2026
- Date
- 07/23/2026
- Time
- Before Open
- Conference Call
- Thursday, July 23, 2026
Leonteq AG's next earnings date is estimated for February 11, 2027, based on past reporting schedules.
Q2 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q2 2026 Earnings Slide Deck
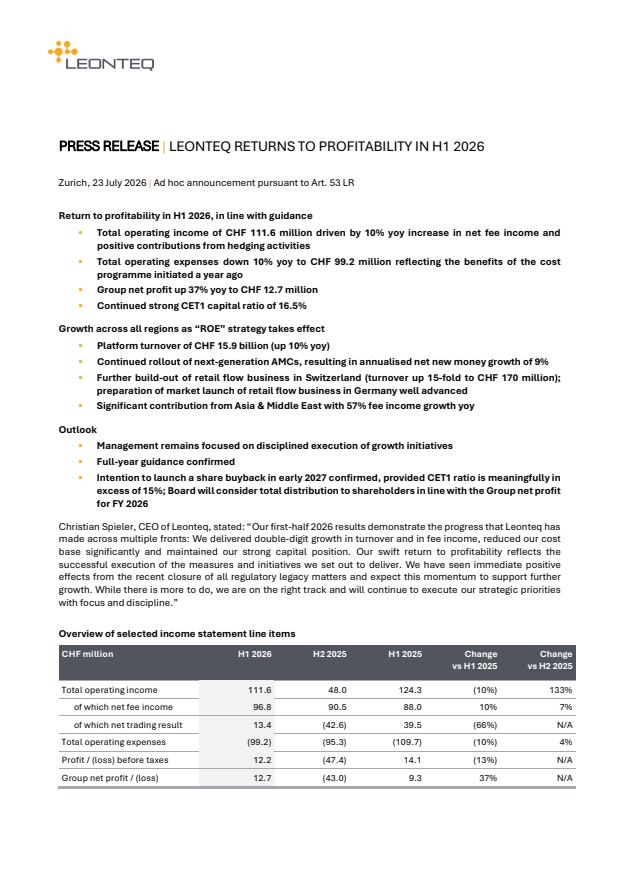
Q2 2026 Earnings Call Summary
The call communicated a clear and measurable recovery: return to profitability, double‑digit growth in fee income and turnover, significant cost reductions, strengthened recurring and capital‑efficient businesses (AMCs, QIS, LYNQS), and a solid capital base with a Board‑level intent to return capital to shareholders. Offsetting concerns include a 10% year‑on‑year decline in total operating income (driven by weaker trading), a negative treasury carry component, higher RWAs and slightly lower CET1 ratio, a reduction in Tier 1 partner turnover, and continued pressure in the pension/long‑term savings segment. Overall, the positives — particularly the profitability turnaround, revenue and fee growth, cost discipline, regional momentum (Asia), and strategic progress — materially outweigh the negatives.
Leonteq reiterated full‑year 2026 guidance to deliver a positive pretax result and reconfirmed operating expense guidance of approximately CHF 200 million, while signalling a shareholder distribution framework of an unchanged dividend policy (30%) and the Board's intention to launch a share buyback in early 2027 (Hans referenced a potential buyback at ~70% of net profit), conditional on maintaining a CET1 ratio meaningfully and sustainably above 15% (CET1 was 16.5% at end‑June; eligible capital CHF 655m; RWAs CHF 3.97bn). Management said the outlook is supported by H1 performance—pretax profit CHF 12.2m, net profit CHF 12.7m, EPS CHF 0.71, RoTE 4%—and improving underlying metrics including net fee income CHF 96.8m (+10% YoY), total operating income CHF 111.6m, platform turnover CHF 15.9bn (+10% YoY), H1 operating expenses CHF 99.2m, own‑issued products CHF 5.6bn, assets CHF 12.4bn, shareholders’ equity CHF 710m, and growth areas they expect to drive further results (AMC outstanding ~CHF 2.4bn with ~9% annualized net new money, QIS ~700 indices, balance‑sheet‑light turnover CHF 3.6bn, LYNQS product initiations +42% with 36% click‑and‑trade).
- Return to ProfitabilityReported profit before taxes of CHF 12.2 million and group net profit of CHF 12.7 million (up 37% year‑on‑year). Earnings per share increased 34% to CHF 0.71 and return on tangible equity improved to 4% (progress towards 2028 10% target).
- Net Fee Income and Turnover GrowthNet fee income grew 10% year‑on‑year to CHF 96.8 million and rose 7% versus H2 2025. Platform turnover increased 10% to CHF 15.9 billion, supported by a 21% year‑on‑year increase in Leonteq own‑issued products.
- Regional Revenue Strength — Asia & Middle EastNet fee income in Asia and the Middle East grew 57% year‑on‑year to CHF 16.0 million, driven by pickup in private banking demand and expansion into institutional transactions.
- Cost Reductions and Resizing ProgressOperating expenses decreased 10% year‑on‑year to CHF 99.2 million. Personnel expenses fell CHF 7.8 million (‑13%) to CHF 51.6 million and full‑time equivalents declined 6% to 531 FTEs, reflecting effects of the resizing program.
- Capital Position and Shareholder Return IntentEligible capital increased to CHF 655 million; CET1 ratio at 16.5% (vs 16.9% end‑2025). Board confirmed intention to launch a share buyback in early 2027 (subject to CET1 sustainably meaningfully >15%) and signaled distribution potential (dividend + buyback) in line with 2026 net profit.
- Growing Recurring and Capital‑Efficient BusinessesAMCs outstanding volumes increased to CHF 2.4 billion with annualized net new money growth of 9%. Balance‑sheet‑light turnover rose 28% to CHF 3.6 billion (23% of total turnover). QIS offering expanded to over 700 indices (more than doubled) and LYNQS product initiations increased 42% with click‑and‑trade ratio improving to 36%.
- Retail Flow Momentum in SwitzerlandEntered listed leverage products market in April 2025; by June 30, 2026 had >20,000 products listed and increased SIX Swiss Exchange turnover 15‑fold year‑on‑year to CHF 170 million. Achieved ~7% market share by turnover and ~10% by number of trades in the relevant segment.
- Improved Funding and Interest ExpenseNet interest expense improved to CHF 0.6 million from CHF 4.9 million year‑on‑year, attributed to balance sheet optimizations; treasury/hedging activity delivered positive hedging contribution of CHF 21.6 million (treasury carry within trading line was negative CHF 8.2 million).
CH:LEON Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Feb 11, 2027 | 2026 (Q4) | 0.70- | -2.43 | ― | ― |
| Jul 23, 2026 | 2026 (Q2) | 0.600.71 | 0.53 | 33.96% (+0.18) | |
| Feb 12, 2026 | 2025 (Q4) | -1.80-2.43 | 0.18 | -1411.35% (-2.61) | |
| Jul 24, 2025 | 2025 (Q2) | 0.530.53 | 0.89 | -40.58% (-0.36) | |
| Feb 06, 2025 | 2024 (Q4) | 0.180.18 | -0.43 | 142.63% (+0.62) | |
| Jul 25, 2024 | 2024 (Q2) | 0.980.89 | 1.41 | -36.83% (-0.52) | |
| Feb 08, 2024 | 2023 (Q4) | 0.85-0.43 | 2.21 | -119.59% (-2.65) | |
| Jul 20, 2023 | 2023 (Q2) | 1.481.41 | 2.99 | -52.79% (-1.58) | |
| Feb 09, 2023 | 2022 (Q4) | 2.212.21 | 4.06 | -45.47% (-1.85) | |
| Jul 21, 2022 | 2022 (Q2) | 3.202.99 | 4.25 | -29.56% (-1.25) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
