


A & W Food Services of Canada Inc. earnings date
A & W Food Services of Canada Inc. (AWFDF) Q3 2026 Earnings Report
AWFDF Q3 2026 EPS Results
- Actual EPS
- $0.57
- Consensus EPS
- $0.47
- Beat/Miss
- Beat by +$0.10
- One Year Ago EPS
- $0.51
AWFDF Q3 2026 Revenue Results
- Actual Revenue
- $56.60M
- Expected Revenue
- $53.91M
- Beat/Miss
- Beat by +$2.68M
- YoY Revenue Growth
- +11.31%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 10/16/2026
- Time
- Before Open
- Conference Call
- Friday, October 16, 2026
A & W Food Services of Canada Inc.'s next earnings date is estimated for March 10, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q3 2026 Earnings Slide Deck
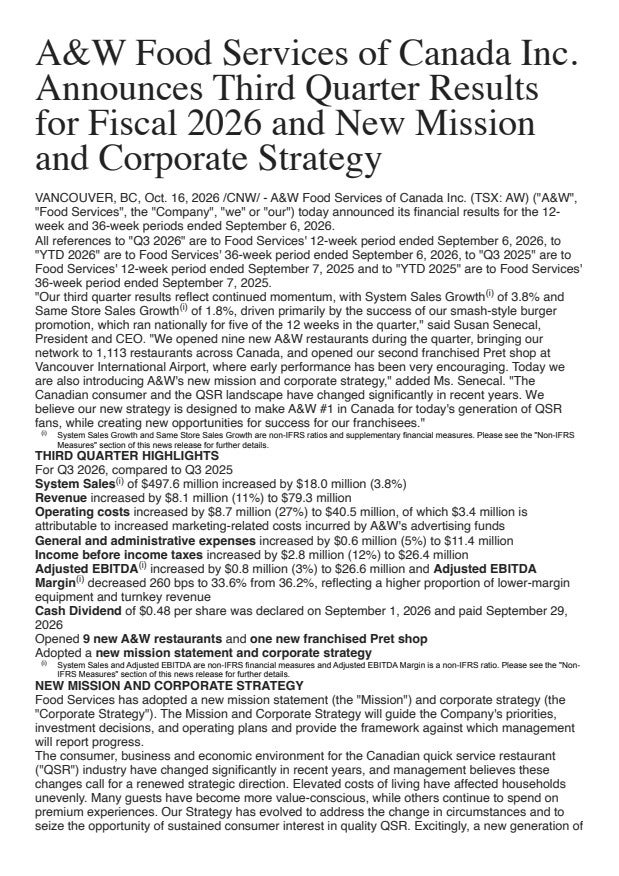
Q3 2026 Earnings Call Summary
The call was broadly positive, with higher same-store sales, system sales, revenue, net income, adjusted EBITDA and free cash flow, continued restaurant and Pret expansion, deleveraging, maintained fiscal 2026 guidance and a new growth-oriented strategy. These strengths were partially offset by higher operating and general and administrative costs, adjusted EBITDA margin compression and ongoing consumer affordability and fuel-cost pressures.
For fiscal 2026, the outlook remains unchanged and includes achieving adjusted EBITDA within the range of $103 million to $105 million, up from the $100 million achieved in 2025; ending fiscal 2026 within the range of 1,112 to 1,120 A&W restaurants, up from 1,094 at the end of 2025; system sales growth in the range of 2.5% to 5% compared to 2.8% achieved in 2025; and same-store sales growth in the range of 0.5% to 3% compared to 1.2% achieved in 2025. A&W also continues to expect 3 to 4 franchise Pret shops to be opened by the end of fiscal 2026, in addition to the 2 corporate locations operated in Toronto, and remains committed to maintaining the current level of quarterly dividends for the foreseeable future.
- Positive Same-Store Sales and Smash Burger MomentumQ3 2026 same-store sales growth was 1.8%, up from 1.4% in Q3 2025, marking positive same-store sales growth in 6 of the last 7 quarters. The A&W Smashed burger limited-time offer was the primary driver of Q3 same-store sales growth and generated 15% same-store sales growth at its peak in a single week.
- System Sales GrowthSystem sales increased 3.8% to $497.6 million, reflecting same-store sales growth of 1.8% and growth in the restaurant network.
- Continued A&W Restaurant ExpansionA&W opened 9 restaurants in Q3 2026, bringing year-to-date openings to 21, including 7 opened in partnership with Suncor. The company ended the quarter with 1,113 A&W restaurants and 26 additional restaurants under construction, with continued focus on Quebec and Ontario.
- Lower-Cost Restaurant Design ProgressThe company reported encouraging progress with its new lower-cost freestanding restaurant design, with additional locations either newly opened or under construction.
- Pret A Manger GrowthA&W opened its second franchised Pret shop at Vancouver International Airport during the quarter, bringing the Canadian total to 4 Pret shops. The company reported strong early performance and consumer demand for premium grab-and-go options, secured leases for additional locations, and expects 3 to 4 franchise Pret shops to open by the end of fiscal 2026 in addition to 2 corporate Toronto locations.
- Revenue GrowthTotal revenue was $79.3 million, an increase of 11%, or $8.1 million, compared with Q3 2025. The increase was driven by higher equipment and turnkey revenue from additional restaurant openings, as well as higher service fees, distribution revenue and advertising fund contributions driven by system sales.
- Improved Pre-Tax Income, Net Income and EPSIncome before income taxes increased $2.8 million, or 12%, to $26.4 million. Net income increased to $19.5 million from $17.6 million, while diluted earnings per share increased to $0.80 from $0.71.
- Lower Finance Expense and Interest Rate Swap GainNet finance expense decreased by $0.5 million due to a lower average debt balance and a reduced interest rate on the operating loan. The company recorded a $2.1 million unrealized gain on its interest rate swap in Q3 2026 compared with a $1.4 million unrealized loss in Q3 2025.
- Adjusted EBITDA GrowthAdjusted EBITDA increased 3% to $26.6 million from $25.8 million in Q3 2025, supported by the increase in revenue.
- Fiscal 2026 Guidance MaintainedThe company maintained its fiscal 2026 guidance, including adjusted EBITDA of $103 million to $105 million versus $100 million achieved in 2025; 1,112 to 1,120 A&W restaurants versus 1,094 at the end of 2025; system sales growth of 2.5% to 5% versus 2.8% in 2025; and same-store sales growth of 0.5% to 3% versus 1.2% in 2025.
- Continued DeleveragingThe net debt to adjusted EBITDA ratio declined to 2.2 at the end of Q3 2026 from 2.3 at the end of 2025 and 2.4 at the end of Q3 2025.
- Higher Free Cash FlowFree cash flow was $19.5 million, an increase of $2.5 million from Q3 2025, primarily due to timing differences that resulted in lower use of working capital.
- Dividend Commitment and Share RepurchasesA&W declared a cash dividend of $0.48 per share and remains committed to maintaining the current quarterly dividend level for the foreseeable future. Under its normal course issuer bid, the company had repurchased and canceled 61,000 common shares year-to-date, with 23.9 million common shares outstanding; the authorization permits purchases of up to 600,000 shares through March 19, 2027.
- New Strategy Focused on Growth and Guest RelevanceA&W introduced a mission to become #1 in Canada for today's generation of QSR fans, supported by three strategic directions: expanding its leading burger brand and market share through menu innovation and guest experience; supporting new restaurant growth through new formats and business models; and growing Pret and evaluating other complementary brands.
- Menu, Digital and Loyalty InitiativesThe strategy includes distinctive innovation across premium beef burgers, chicken, plant-based and globally inspired offerings, while building on gains from the 5-star operating system, the A&W mobile app and the A&W Rewards loyalty program.
- Premium Value and Beverage OpportunitiesManagement said it is addressing both value-conscious consumers and guests seeking premium experiences through affordable prices paired with A&W quality, new beverage innovation and continued focus on Root Beer as a core beverage offering.
- Franchisor and Sustainability PrioritiesThe company reaffirmed its franchisor capital-light business model, its commitment to keeping the cost of becoming an A&W franchisee affordable, and its Climate Goals. Progress will continue to be measured through same-store sales growth, system sales growth, adjusted EBITDA and total A&W and Pret locations.
- Performance Relative to the MarketManagement said A&W was performing at or slightly ahead of the market based on its tracking, with domestic travel providing some uplift during Q3.
AWFDF Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Mar 10, 2027 | 2026 (Q4) | 0.57- | 0.51 | ― | ― |
| Oct 16, 2026 | 2026 (Q3) | 0.470.57 | 0.51 | 12.68% (+0.06) | |
| Jul 23, 2026 | 2026 (Q2) | 0.390.33 | 0.36 | -8.00% (-0.03) | |
| May 07, 2026 | 2026 (Q1) | 0.300.29 | 0.26 | 8.11% (+0.02) | |
| Mar 05, 2026 | 2025 (Q4) | 0.450.51 | 0.09 | 446.15% (+0.41) | |
| Oct 17, 2025 | 2025 (Q3) | 0.420.51 | 0.18 | 178.43% (+0.32) | |
| Jul 24, 2025 | 2025 (Q2) | 0.410.36 | 0.25 | 42.05% (+0.11) | |
| May 02, 2025 | 2025 (Q1) | 0.380.26 | 0.22 | 22.11% (+0.05) | |
| Mar 05, 2025 | 2024 (Q4) | ―0.09 | 0.29 | -67.74% (-0.19) | |
| May 09, 2024 | 2024 (Q1) | ―0.22 | 0.22 | -1.94% (-0.00) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
