


Albany International earnings date
Want to see AIN full AI Analyst Report?
Albany International (AIN) Q3 2026 Earnings Report
AIN Q3 2026 EPS Results
- Actual EPS
- $1.68
- Consensus EPS
- $1.48
- Beat/Miss
- Beat by +$0.20
- One Year Ago EPS
- $0.71
AIN Q3 2026 Revenue Results
- Actual Revenue
- $349.54M
- Expected Revenue
- $326.12M
- Beat/Miss
- Beat by +$23.41M
- YoY Revenue Growth
- +33.70%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 10/28/2026
- Time
- After Close
- Conference Call
- Wednesday, October 28, 2026
Albany International's next earnings date is estimated for March 2, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
Q3 2026 Earnings Slide Deck
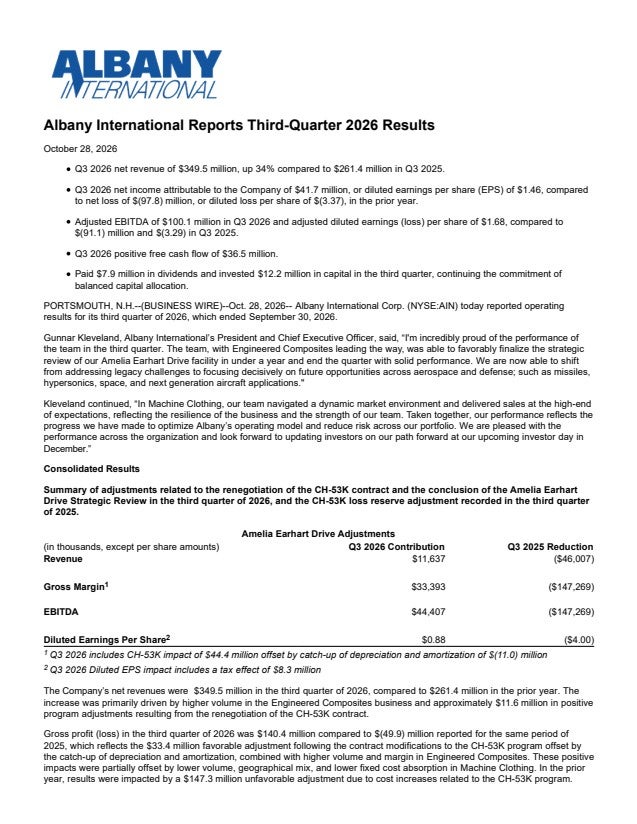
Q3 2026 Earnings Call Summary
The call was strongly positive overall. The company reported record revenue, a significant recovery in profitability, improved cash generation, reduced program risk following the CH-53K agreement, strong Engineered Composites growth, and expanding aerospace, defense, missile, and hypersonics opportunities. Lowlights were concentrated in the declining Machine Clothing business, regional demand softness, limited China visibility, and the presence of significant contract-related and other discrete items in quarterly results.
Management expects full year machine clothing revenue to be slightly down compared to 2025 and engineered composites to deliver continued year over year growth; fourth-quarter 2026 consolidated revenue is expected in the range of $325 million to $335 million, adjusted EPS in the range of $0.65 to $0.75 per diluted share, and an effective tax rate of approximately 29.5%. In engineered composites, 12.5% should be a reasonable approximation through the fourth quarter and the beginning of 2027, with the goal of being in the mid teens in this business as we exit 2027, while additional margin expansion is expected beginning in the second half of 27. Machine Clothing volume is expected to be caught up by year end, missile opportunities are expected to impact 2027 and 2028, and fourth-quarter cash flow may be consistent with what we have seen in Q3 or near that.
- Record Quarterly RevenueThird-quarter consolidated revenue increased 34% year over year to $349.5 million, a record high quarterly revenue for the company. Growth was primarily driven by higher activity in Engineered Composites, production-rate increases across key aerospace and defense programs, and approximately $12 million related to the renegotiated CH-53K contract.
- Strong Adjusted EBITDA and EPSAdjusted EBITDA was $100.1 million and adjusted diluted EPS was $1.68, above the high end of the revised output range provided after the strategic review.
- Strategic Review and CH-53K Agreement CompletedThe company completed its strategic review and reached an agreement with Sikorsky that improves the economics of the CH-53K program, provides a more stable foundation for the Salt Lake City manufacturing site, removes uncertainty, and improves the program's long-term economics.
- Engineered Composites Delivered Record RevenueEngineered Composites generated record quarterly revenue of $179.7 million, driven by higher production rates across LEAP, Boeing platforms, CH-53K, and missile programs. The segment's performance was above estimates due in part to the pull forward of tooling for a next-generation defense-prime contract.
- Engineered Composites Margin ImprovementEngineered Composites adjusted EBITDA was $65.6 million, or 36.5% of sales, compared with a loss of $134.6 million in the prior-year quarter. Excluding the stated contract adjustments and other impacts, management indicated an underlying third-quarter EBITDA margin of approximately 12.5%, with reasonable growth expected from that base and a goal of reaching the mid-teens by the end of 2027.
- CH-53K Contract Amendment Improved ResultsThe CH-53K renegotiation contributed approximately $12 million to revenue and $44 million to adjusted EBITDA in the quarter. Gross profit benefited by $33.4 million from the amended contract, and management expects additional margin expansion beginning in the second half of 2027 as contract modifications begin to have an impact.
- Broad Aerospace, Defense, and Missile Program GrowthGrowth was reported across LEAP, Boeing 787 and other Boeing wide-body platforms, missile programs, and the engine section of the business. Management said demand across core commercial aerospace and defense programs remains strong and production rates continue to build across multiple platforms.
- IBAS Award Supports Ceramics Matrix Composite CapabilityThe company received a $21.2 million Industrial Base Analysis and Sustainment award to complement its investments in ceramics matrix composites. The funding will support in-house machining, quality inspection, and an additional densification process, broadening the scope of the company's capabilities.
- Hypersonics and Missile Opportunities AdvancingThe company said it is working with multiple missile OEMs and expects an accelerated schedule for qualifying and ramping new opportunities. Existing programs including JASSM and LRASM are already seeing significant demand, with impacts expected in 2027 and definitely in 2028.
- Technology Expansion and Lockheed Martin TeamingThe company cited a teaming agreement with Lockheed Martin on hypersonic missile development and its inclusion in the Wing of Tomorrow program. Albany's 3D woven braiding, automation, and resin transfer molding solutions are intended to support lighter-weight, more durable, and more efficient composite aerostructures.
- Machine Clothing Maintained Market Share and Strong MarginsMachine Clothing revenue was approximately $169.8 million to $170 million, at the high end of expectations. Adjusted EBITDA was $46.3 million; the CFO reported a 27.2% margin, while the CEO described the margin as approximately 20%. The business maintained strong market share in the Americas, and management cited disciplined cost management, operational execution, integration, and efficiency initiatives.
- Improving Regional and Grade Trends in Machine ClothingNorth American end-market conditions and order rates materially improved, Europe remained favorable, and China was stable for the fourth consecutive quarter with signs of stabilization at current levels. Tissue and packaging demand remained favorable, particularly in Asia, as demand stabilized compared with the prior year.
- Improved Profitability and Cash FlowGross profit was $140.4 million with a 40.2% margin, compared with a prior-year loss of $49.9 million. Operating income was $59.4 million with a 17% margin, compared with a prior-year loss of $116.5 million. Free cash flow increased to $36.5 million from $25.7 million.
- Debt Reduction and LiquidityInterest expense declined to $5.3 million from $5.9 million as the company paid down debt. The company ended the quarter with $79.1 million in cash and $422.1 million in total debt, resulting in approximately $343 million of net debt. Including revolver availability, approximately $457 million of capital was available to support investments and return capital to shareholders.
- Lower Capital Expenditures with Continued Growth InvestmentCapital expenditures declined to $12.2 million from $18.3 million in the prior year as facility optimization lowered expenditures. Management said it expects to continue investing in significant Engineered Composites growth, including growth capital for new programs.
- Machine Clothing Equipment Recovery ProgressThe existing machine continued to operate without additional downtime, the new machine was being assembled at the site and was expected to be running by year end, and management said the plan to catch up on volumes by year end remained absolutely possible.
- Disciplined Capital Deployment and Potential AcquisitionsManagement said capital deployment will remain disciplined while it evaluates inbound acquisition opportunities more seriously now that structural issues are behind the company. It also cited substantial organic opportunities and continued discipline regarding dividends.
- Fourth-Quarter Revenue and EPS GuidanceThe company maintained fourth-quarter 2026 consolidated revenue guidance of $325 million to $335 million, adjusted EPS guidance of $0.65 to $0.75 per diluted share, and an expected effective tax rate of approximately 29.5%.
AIN Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Mar 02, 2027 | 2026 (Q4) | 0.69- | 0.65 | ― | ― |
| Oct 28, 2026 | 2026 (Q3) | 1.481.68 | 0.71 | 136.62% (+0.97) | |
| Aug 04, 2026 | 2026 (Q2) | 0.740.82 | 0.57 | 43.86% (+0.25) | |
| Apr 30, 2026 | 2026 (Q1) | 0.530.60 | 0.73 | -17.81% (-0.13) | |
| Feb 24, 2026 | 2025 (Q4) | 0.610.65 | 0.58 | 12.07% (+0.07) | |
| Nov 05, 2025 | 2025 (Q3) | 0.730.71 | 0.8 | -11.25% (-0.09) | |
| Jul 30, 2025 | 2025 (Q2) | 0.730.57 | 0.89 | -35.96% (-0.32) | |
| Apr 30, 2025 | 2025 (Q1) | 0.680.73 | 0.9 | -18.89% (-0.17) | |
| Feb 26, 2025 | 2024 (Q4) | 0.660.58 | 1.22 | -52.46% (-0.64) | |
| Oct 30, 2024 | 2024 (Q3) | 0.570.80 | 1.02 | -21.57% (-0.22) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
