


Airboss of America earnings date
Airboss of America (ABSSF) Q3 2026 Earnings Report
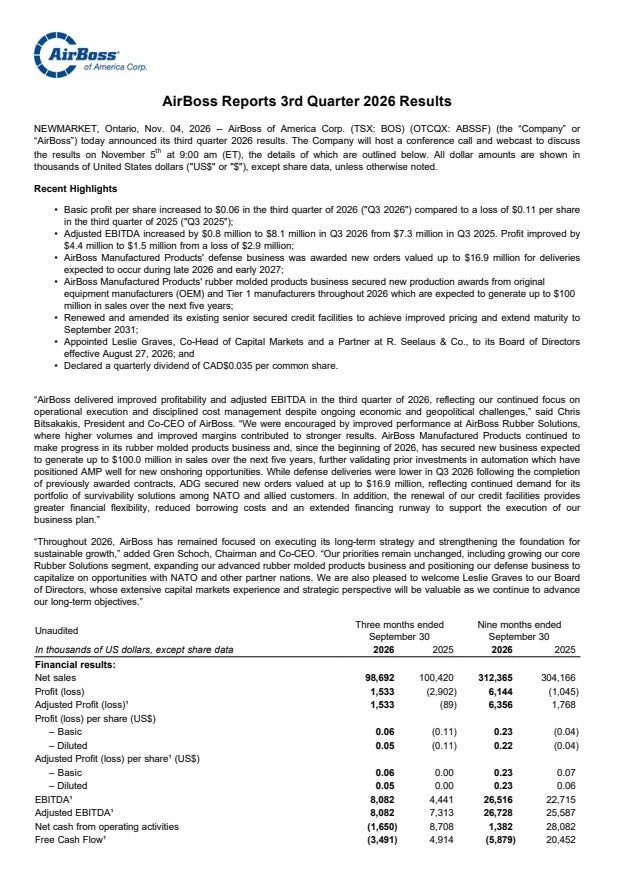
ABSSF Q3 2026 EPS Results
- Actual EPS
- $0.05
- Consensus EPS
- $0.06
- Beat/Miss
- Missed by -$0.01
- One Year Ago EPS
- $0.00
ABSSF Q3 2026 Revenue Results
- Actual Revenue
- $97.37M
- Expected Revenue
- $104.13M
- Beat/Miss
- Missed by -$6.76M
- YoY Revenue Growth
- -0.09%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 11/04/2026
- Time
- After Close
- Conference Call
- Wednesday, November 4, 2026
Airboss of America's next earnings date is estimated for March 10, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q3 2026 Earnings Slide Deck
Q3 2026 Earnings Call Summary
The call was broadly constructive. The company returned to profitability, expanded gross margins, grew AirBoss Rubber Solutions, secured up to $100 million of rubber-molded product awards and up to $16.9 million of defense orders, and maintained a pipeline of new customers and products. These positives were partly offset by lower consolidated and AMP sales, reduced defense deliveries, operating cash use, higher net debt, expected Q4 cash burn, and continued market, tariff, geopolitical, and program-timing uncertainty.
Management expects ARS volume increases to continue, with several new customers coming on board in Q4 and Q1 of next year and volume ramp-up in the next couple of quarters, barring any sort of crazy geopolitical or economic surprises. New rubber-molded product awards are expected to generate up to $100 million in sales over the next five years, while non-automotive products are expected to come to market in late 2027, early 2028. For the $16.9 million of defense orders, deliveries commence in November and continue through November, December, and early Q1 of next year; most revenue will be recognized in Q4, with the tail end in Q1 of next year, with a guess of maybe 75/25, and more than half expected to be delivered by the end of Q4. The company anticipates a little bit of cash burn in Q4, with operations returning to a sort of a positive cash position towards the end of the quarter and into Q1 and Q2 of 2027, while margins will stay pretty consistent.
- Return to Profitability and Improved EarningsAirBoss returned to profitability in Q3 2026, including a 17% swing in earnings per share compared with Q3 2025. Management attributed the improvement to cost management, better execution, and pursuing new business.
- Higher Consolidated Gross Profit and MarginConsolidated gross profit increased by $0.6 million to $17.0 million. Gross margin improved to 17.3% from 16.4% in Q3 2025, driven primarily by higher volumes and favorable mix at AirBoss Rubber Solutions, improved margins in both AirBoss Manufactured Products businesses, controllable overhead management, and continuous improvement initiatives.
- AirBoss Rubber Solutions RecoveryAirBoss Rubber Solutions sales increased 6.2% to $54.7 million from $51.5 million, while gross profit increased to $7.1 million from $6.3 million. Segment volume increased 9.3%, non-tolling volume increased 10.1%, and gross margin improved to 13% from 12.2%.
- ARS Customer and Volume PipelineManagement said several new customers are coming on board in Q4 and Q1, with volume ramp-up expected over the next couple of quarters. Several customers have approved products that are expected to launch in the next couple of quarters, and management expects the year-over-year volume increase to continue, barring major geopolitical or economic surprises.
- Continued Investment in ARS CapabilitiesAirBoss Rubber Solutions continues to invest in specialty compounding capabilities, research and development, silicone products, new compounds, customer collaboration, and processing ideas intended to improve its competitive position over the next couple of years.
- New Rubber-Molded Products AwardsSince the beginning of 2026, AirBoss Manufactured Products' rubber-molded products business has secured new production awards expected to generate up to $100 million in sales over the next five years.
- Rubber-Molded Products Progress and Onshoring OpportunitiesThe rubber-molded products business reported improved volumes in automotive and non-automotive applications. Management said prior investments in automation and efficiency have supported a higher volume of quoting opportunities and positioned the business to pursue onshoring and reshoring opportunities.
- Defense Orders from NATO and Allied CustomersAirBoss Defense Group secured new orders valued at up to $16.9 million, reflecting continuing demand for its survivability solutions among NATO and allied customers. Deliveries are commencing in November and are expected to continue through December and early Q1 2027, with most revenue expected to be recognized in Q4 and the balance in early Q1.
- Improved AMP Margins Despite Lower Defense VolumesGross margin percentage improved in both AirBoss Manufactured Products businesses compared with the prior-year quarter despite lower defense deliveries. Management said cost reductions taken in previous quarters remain in place and continue to support the base business across the segments.
- Product Innovation Across SegmentsManagement described an active product innovation program involving new ARS compounds, expanding silicone products, non-automotive molded products expected to reach the market in late 2027 or early 2028, and defense products that are gaining new traction with NATO partners.
- Expanded Financing FlexibilityThe renewal of the company's credit facilities extended its financing runway, reduced borrowing costs, and provided additional flexibility to execute the business plan and evaluate opportunities over a longer-term horizon.
- Available Revolving Credit CapacityAs of September 30, 2026, AirBoss had $72.8 million of available borrowing capacity under its asset-based revolving credit facility, which provides for maximum borrowing of up to $125 million plus a $25 million accordion. Drawn borrowings were $35.7 million.
- Expected Working Capital NormalizationManagement said inventory purchases made in response to price escalations were a defensive position that it anticipates consuming and delevering over the coming couple of quarters. The company expects to return to a positive cash position related to operations toward the end of Q1 and into Q2 2027.
ABSSF Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Mar 10, 2027 | 2026 (Q4) | 0.07- | 0.01 | ― | ― |
| Nov 04, 2026 | 2026 (Q3) | 0.060.05 | 0 | ― | |
| Aug 05, 2026 | 2026 (Q2) | 0.070.09 | 0.08 | 12.50% (+0.01) | |
| May 06, 2026 | 2026 (Q1) | 0.070.08 | -0.02 | 500.00% (+0.10) | |
| Mar 04, 2026 | 2025 (Q4) | 0.030.01 | -0.06 | 116.67% (+0.07) | |
| Nov 05, 2025 | 2025 (Q3) | -0.010.00 | -0.12 | 100.00% (+0.12) | |
| Aug 07, 2025 | 2025 (Q2) | 0.010.08 | -0.1 | 180.00% (+0.18) | |
| May 07, 2025 | 2025 (Q1) | -0.03-0.02 | -0.18 | 88.89% (+0.16) | |
| Mar 05, 2025 | 2024 (Q4) | -0.02-0.06 | -0.1 | 40.00% (+0.04) | |
| Nov 06, 2024 | 2024 (Q3) | -0.04-0.12 | -0.1 | -20.00% (-0.02) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
