


Premium Brands earnings date
Premium Brands (PBHN) Q3 2026 Earnings Report
MX:PBHN Q3 2026 EPS Results
- Actual EPS
- MXN 18.08
- Consensus EPS
- MXN 19.75
- Beat/Miss
- Missed by -MXN 1.66
- One Year Ago EPS
- MXN 16.64
MX:PBHN Q3 2026 Revenue Results
- Actual Revenue
- MXN 31.17B
- Expected Revenue
- MXN 31.38B
- Beat/Miss
- Missed by -MXN 204.67M
- YoY Revenue Growth
- +19.78%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 11/05/2026
- Time
- After Close
- Conference Call
- Thursday, November 5, 2026
Premium Brands's next earnings date is estimated for March 11, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q3 2026 Earnings Slide Deck
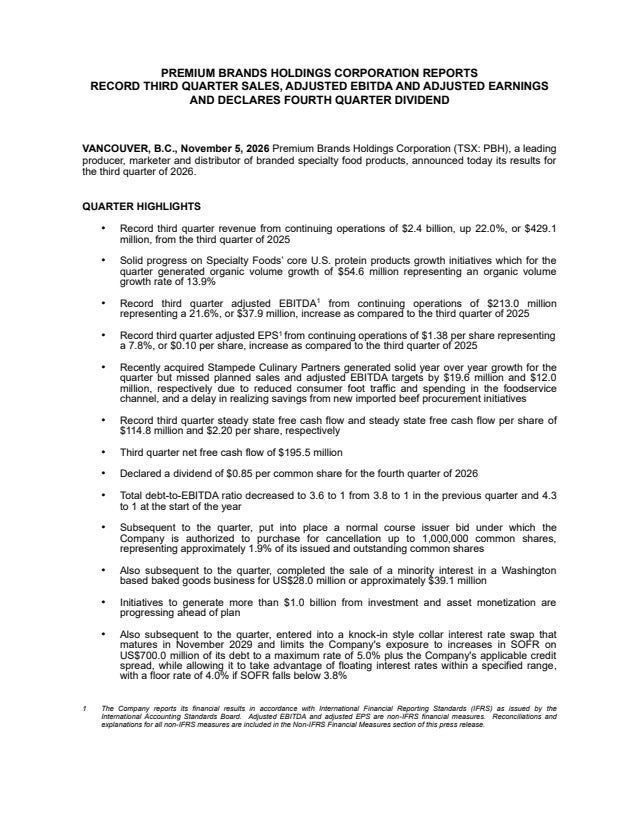
Q3 2026 Earnings Call Summary
The call was positive overall. Management maintained guidance, highlighted strong confirmed business and a substantial sales pipeline, reported strong year-over-year growth at Stampede despite a quarterly miss, and cited meaningful asset monetization, commodity benefits, deleveraging, and share repurchase opportunities. The main challenges were foodservice and consumer weakness, a flat EBITDA margin, Stampede's misses versus plan, delayed procurement savings, and timing uncertainty around new initiatives.
Management maintained its 2026 guidance and expects 2027 EBITDA of CAD 1 billion on a path to CAD 10 billion of sales, with organic volume growth expected to “reaccelerate to double digits next year”; sales initiatives carry contribution margins from minimal 20% to as high as 40%, but sort of in that high 20s, low 30s overall, and the CAD 800 million-CAD 900 million from next year is expected to be about 30/70, 30% run rate and 70% new initiatives, with 30%-40%, in that range for the run rate initiatives. Q4 is expected to benefit from organic volume growth, protein commodity deflation, and a 10%-10.5% EBITDA margin implied by the guidance ranges; Q4 OVGR is expected to be much better than this quarter, but it will not be as good as Q3 and is not going to be far off from that. The Stampede procurement initiative is expected to be operational in Q1 2027, with potential savings of CAD 25 million-CAD 30 million a year, immediately beneficial, and with no ramp-up associated with it; leverage is expected to reach the 3x or better target next year, with potentially mid to third quarter next year a realistic possibility, while the company remains comfortable getting to CAD 1 billion and even exceeding it in asset monetizations after realizing about CAD 250 million.
- Confirmed New Business and 2027 Sales PipelineThe company has approximately CAD 170 million of confirmed customer business launching through Q4 and into 2027. Including that amount, it is actively working on more than CAD 900 million of sales initiatives expected to launch through 2027, supporting management's stated path toward its CAD 10 billion sales target.
- Attractive Margins on Growth InitiativesThe Specialty Foods initiatives are expected to generate contribution margins ranging from a minimum of 20% to as high as 40%, with the overall mix expected to be in the high 20s to low 30s.
- Stampede Delivered Strong Year-over-Year GrowthAlthough Stampede was below plan, its sales increased almost 15% year-over-year, with half of that growth coming organically. Stampede also delivered year-over-year EBITDA growth, which management expects to continue in Q4.
- Large Stampede Procurement OpportunityStampede's imported beef procurement initiative is expected to generate potential savings of CAD 25 million to CAD 30 million annually. The initiative is scheduled to be operational in Q1 2027 and is expected to be immediately beneficial once operational, although some savings will be shared with customers and suppliers.
- Asset Monetization Progress Ahead of PlanThe company has already monetized approximately CAD 250 million of non-core assets and investments by selling two bakery investments. Both transactions were completed at mid-teen multiples, and proceeds exceeded the company's budget. Management said it remains comfortable reaching or exceeding the CAD 1 billion monetization target based on the current pipeline.
- Free Cash Flow and Working Capital MomentumThe call highlighted strong free cash flow momentum and a significant working capital release, including an increase in payables primarily driven by the Stampede acquisition and payment timing.
- Expected Q4 Benefit from Protein DeflationManagement maintained its guidance partly because it is beginning to see deflation across the protein complex in Q4. The company did not materially benefit from the deflation that began in Q3 because of inventory positions and transfer timing, but expects to benefit in Q4, particularly from beef and chicken.
- Strong Retail and Club ChannelsWhile foodservice exposure showed weakness, management said its retail and club numbers remained strong. Growth is being driven by new distribution points, new customers, and new geographic areas, including relationships with Costco, Trader Joe's, Aldi, and other customers described as winning in the current market.
- Premium Private Label OpportunityPremium private label has increased from approximately 10% of the U.S. market to about 20% over the last five years. Management believes it could reach 40% of the market if it follows European trends. Premium private label has been a fast-growing area for the company, growing in the mid-teens overall, with contribution margins in line with the relevant operating platform.
- Capacity and Product Positioning Support GrowthThe company said its investments in premiumization, convenience, and protein capacity position it to serve large customers launching premium private label products. Management also said many initiatives have progressed from early-stage status to either highly likely or confirmed.
- Maintained Guidance and Deleveraging OutlookThe company maintained its current guidance. Management expects debt to decline quickly through operating free cash flow and continues to expect leverage to reach 3x or better in 2027, with mid- to third-quarter timing described as a realistic possibility. After debt reduction, the main capital allocation priority is share repurchases.
- Organic Growth Expected to ReaccelerateManagement expects organic volume growth to reaccelerate to double digits in 2027. It attributed confidence to the absence of another LTO comparable to the CAD 100 million SKU that benefited from unusually strong demand in 2025 and to the increasing number of initiatives that are now highly likely or confirmed.
- Major Initiatives Already LaunchedThe company launched six major initiatives around the end of Q3. They did not contribute to Q3 because they were launched late in the quarter, but management said most of the requirements to achieve the current-year EBITDA guidance are already in place.
- Share Repurchases Favored over AcquisitionsManagement said it is not currently prioritizing acquisitions and finds it difficult to justify acquisitions instead of buying back the company's stock at current levels. The stated priorities are debt reduction followed by share repurchases.
MX:PBHN Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Mar 11, 2027 | 2026 (Q4) | 20.90- | 16.91 | ― | ― |
| Nov 05, 2026 | 2026 (Q3) | 19.7518.08 | 16.64 | 8.66% (+1.44) | |
| Aug 06, 2026 | 2026 (Q2) | 20.2120.05 | 17.43 | 15.04% (+2.62) | |
| May 07, 2026 | 2026 (Q1) | 9.5410.88 | 8.91 | 22.06% (+1.97) | |
| Mar 19, 2026 | 2025 (Q4) | 16.8116.91 | 13.76 | 22.86% (+3.15) | |
| Nov 10, 2025 | 2025 (Q3) | 18.3116.64 | 14.55 | 14.41% (+2.10) | |
| Aug 06, 2025 | 2025 (Q2) | 17.0017.43 | 16.77 | 3.91% (+0.66) | |
| May 07, 2025 | 2025 (Q1) | 8.788.91 | 7.08 | 25.93% (+1.83) | |
| Mar 21, 2025 | 2024 (Q4) | 12.4813.76 | 11.14 | 23.53% (+2.62) | |
| Nov 06, 2024 | 2024 (Q3) | 18.0614.55 | 16.64 | -12.60% (-2.10) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
