

Ivanhoe Mines (IVNN) Q3 2026 Earnings Report
MX:IVNN Q3 2026 EPS Results
- Actual EPS
- MXN 0.74
- Consensus EPS
- MXN 1.30
- Beat/Miss
- Missed by -MXN 0.56
- One Year Ago EPS
- MXN 0.37
MX:IVNN Q3 2026 Revenue Results
- Actual Revenue
- MXN 4.91B
- Expected Revenue
- MXN 5.08B
- Beat/Miss
- Missed by -MXN 172.26M
- YoY Revenue Growth
- +107.27%
Earnings Announcement Details
- Quarter
- Q3 2026
- Date
- 11/03/2026
- Time
- After Close
- Conference Call
- Tuesday, November 3, 2026
Ivanhoe Mines's next earnings date is estimated for March 9, 2027, based on past reporting schedules.
Q3 2026 Earnings Call Audio
Q3 2026 Earnings Slide Deck
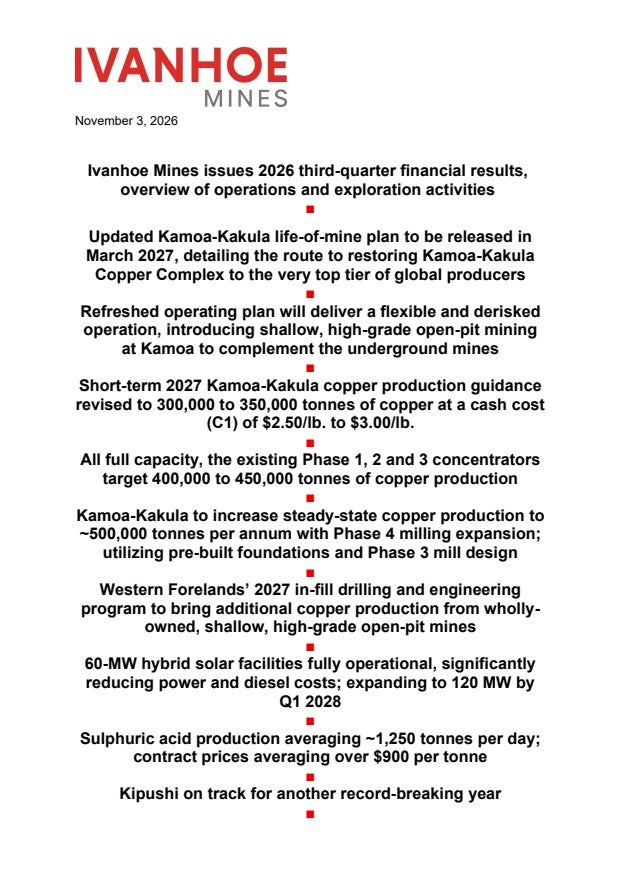
Q3 2026 Earnings Call Summary
The call was predominantly positive, led by record Kipushi results, strong Kamoa-Kakula revenue and EBITDA growth, meaningful smelter and solar benefits, resource growth, and progress at Platreef and Western Forelands. These positives were partially offset by the reset to Kamoa-Kakula's 2027 guidance, delayed Kakula development, lower feed grades, elevated quarterly cash costs, underutilized processing capacity, higher capital expenditure, and increased net debt.
Kamoa-Kakula’s 2026 guidance was maintained, with production expected to be at the low end at 290,000 tonnes, while 2027 copper production guidance is 300,000 to 350,000 tonnes and 2027 C1 costs are guided at $2.50 to $3 per pound; production is expected to reach 400,000 to 450,000 tonnes in 2028 and the Phase 4 expansion is expected to add 5 million and 6.5 million tonnes per annum process capacity, returning the complex to steady-state production of 500,000 tonnes. Kamoa-Kakula’s open-pit CapEx is estimated at between $100 million and $200 million, solar capacity is planned to increase to 120 megawatts by late 2027 and then to 150 megawatts by mid-2028, and Kipushi guidance was narrowed to between 270,000 and 290,000 tonnes of zinc, with Q4 sales expected to exceed production probably by around 10,000 tonnes. Platreef Phase 1 is expected to reach commercial production either late this year or very, very early next year, Phase 2 completion is targeted for Q4 2027, with milling capacity of 3.3 million tonnes per annum, and Phase 2 is expected to be a nice substantial contributor to EBITDA from 2028 onwards.
- Record Kipushi Operating PerformanceKipushi achieved multiple quarterly records, including feed grade in excess of 41%, zinc recovery in excess of 96%, payable zinc produced in excess of 77,000 tonnes, payable zinc sold in excess of 69,000 tonnes, and EBITDA in excess of $108 million. The full plant is operated by DRC nationals.
- Kipushi Revenue and EBITDA GrowthKipushi revenue increased to $255 million from $146 million in Q2, while payable zinc sold rose to almost 70,000 tonnes from 43,000 tonnes. EBITDA more than doubled to $108 million from $51 million, and the EBITDA margin expanded to 43% from 35%.
- Kipushi Guidance Raised Toward Upper EndKipushi narrowed its 2026 production guidance toward the upper end to between 270,000 and 290,000 tonnes of zinc. Year-to-date C1 costs remained at $0.89 per pound of payable zinc, around the midpoint of the guidance range.
- Strong Kamoa-Kakula Quarterly Production and RevenueKamoa-Kakula sold just over 67,000 tonnes of payable copper in Q3, up from 61,000 tonnes in Q2. Quarterly revenue exceeded $1 billion for the first time, increasing more than 17% quarter-on-quarter due to higher tonnes sold, a higher copper price, and increased sulfuric acid revenue.
- Kamoa-Kakula EBITDA and Margin ImprovementKamoa-Kakula EBITDA rose to $478 million from $385 million in Q2, an almost 25% increase. The EBITDA margin increased to 46% from 44%, supported by higher copper prices, stronger sulfuric acid sales, and higher payable copper sales.
- Significant Smelter BenefitsThe smelter delivered approximately $0.86 per pound of gross benefits in 2026 to date compared with the second half of 2025. Benefits included approximately $0.46 per pound from sulfuric acid byproduct credits, approximately $0.30 per pound from logistics savings, and approximately $0.10 per pound from avoided treatment, refining, and tolling charges. After approximately $0.39 per pound of smelter operating costs, the net benefit was approximately $0.47 per payable pound.
- Sulfuric Acid Sales and Pricing StrengthKamoa-Kakula sold in excess of 109,000 tonnes of sulfuric acid at an average price of $915 per tonne, with year-to-date pricing up more than 100%. Q3 sulfuric acid revenue exceeded $100 million, compared with $56 million in Q2, and October sales averaged over $950 per tonne.
- Solar Facility Commissioned at Kamoa-KakulaThe 60-megawatt solar facility was fully commissioned and handed over to the mine, providing more than 95% reliability at an approximately $0.17 per kilowatt-hour tariff. The company expects the facility to reduce energy costs by $0.10 to $0.20 per pound from Q4 onward, and October was described as the first month in which the operation was not reliant on diesel generators.
- Planned Solar Capacity ExpansionIvanhoe plans to increase Kamoa-Kakula solar capacity from 60 megawatts to 120 megawatts by late 2027 and then to 150 megawatts by mid-2028 through an additional 30 megawatts from two IPPs. Kipushi is also evaluating a 10-megawatt hybrid solar PV and battery-storage facility targeted for Q2 2028.
- Open-Pit Strategy Adds Production FlexibilityKamoa-Kakula plans to commence multiple shallow, high-grade open-pit starter pits in Q1 2027. Between 2027 and 2028, the company expects to mine approximately 3.5 million tonnes at 2.5% copper across four pits. The open pits are described as low-capital, low-technical-risk sources of ore that can help fill concentrator capacity and rebuild stockpiles.
- Longer-Term Phase 4 Expansion PotentialLarger open pits are expected to support a Phase 4 concentrator expansion adding between 5 million and 6.5 million tonnes per annum of processing capacity. The company said this could return the complex to steady-state production of 500,000 tonnes of copper, with open pits expected to provide about 40% of overall feed after the Phase 4 expansion.
- Improved Kamoa-Kakula Mining and Recovery MetricsQ3 mining and milling rates reached a 12-month high equivalent to 14 million tonnes, up approximately 17% to 18% quarter-on-quarter, while mining rates increased 20% quarter-on-quarter. Stoping increased 84% quarter-on-quarter. Project 95 improved recoveries at the Phase 1 and Phase 2 concentrators by approximately 5%; Q3 recovery averaged 89%, with recent recoveries reaching 91% to 92%.
- Record Ivanhoe Adjusted EBITDAIvanhoe Mines' adjusted EBITDA increased to a record $241 million from almost $180 million in Q2 and $87 million in Q3 of the prior year. The result included contributions from Kamoa-Kakula and the strong improvement at Kipushi, despite exploration expenditure increasing to $44 million from $15 million in Q2.
- Improved Cash Position and Lower Net Leverage RatioIvanhoe ended September with $643 million of cash and cash equivalents, up from $635 million at the end of Q2. Including Ivanhoe's attributable share of Kamoa-Kakula, cash and cash equivalents were $785 million. Although pro forma net debt increased to almost $1.7 billion from $1.5 billion, the net leverage ratio declined from approximately 2.48x to 2.26x, or 1.75x using annualized Q3 EBITDA.
- Platreef Development ProgressPlatreef's Shaft 3 was successfully handed over at the end of March and has capacity to feed both the Phase 1 and Phase 2 concentrators. Phase 1 is expected to reach commercial production late this year or very early next year, while Phase 2 concentrator completion is targeted for Q4 2027. Phase 2 is expected to provide 3.3 million tonnes per annum of milling capacity.
- Western Forelands Resource GrowthWestern Forelands contained copper resources increased 30% to approximately 12 million tonnes across inferred and indicated resources. The company said it continues to discover copper at an industry-leading cost of less than $10 per tonne and described Western Forelands as the largest and highest-grade discovery over the last decade.
- Expansionary and Infill Exploration ProgressWestern Forelands exploration includes 63,000 meters of infill drilling to support future mine planning and a 2027 scoping study, while expansionary drilling continues in several zones. Ivanhoe also completed approximately 6,000 meters of drilling in Zambia and 17,000 meters in Kazakhstan during Q3, confirming IOCG-style mineralization in Zambia and a significant 270-meter weak chalcopyrite intersection in Kazakhstan.
- Health and Safety Campaign LaunchedIvanhoe launched the One Ivanhoe, One Road to Zero campaign focused on zero harm, healthy people, every shift. The three-phase strategy includes gap analysis, implementation, verification, and auditing, with initial focus on training, fatal-risk controls, safety culture, fall-of-ground risks, and equipment handling.
MX:IVNN Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Mar 09, 2027 | 2026 (Q4) | 1.19- | 0.74 | ― | ― |
| Nov 03, 2026 | 2026 (Q3) | 1.300.74 | 0.37 | 100.00% (+0.37) | |
| Jul 29, 2026 | 2026 (Q2) | 0.930.56 | 0.56 | 0.00% (+0.00) | |
| May 06, 2026 | 2026 (Q1) | ―0.00 | 1.86 | -100.00% (-1.86) | |
| Feb 18, 2026 | 2025 (Q4) | 0.590.74 | 1.3 | -42.86% (-0.56) | |
| Oct 29, 2025 | 2025 (Q3) | 0.170.37 | 1.67 | -77.78% (-1.30) | |
| Jul 30, 2025 | 2025 (Q2) | 0.760.56 | 1.86 | -70.00% (-1.30) | |
| Apr 30, 2025 | 2025 (Q1) | 1.351.86 | 1.11 | 66.67% (+0.74) | |
| Feb 20, 2025 | 2024 (Q4) | 1.541.30 | 0.95 | 37.25% (+0.35) | |
| Oct 30, 2024 | 2024 (Q3) | 1.671.67 | 1.48 | 12.50% (+0.19) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
