

Elemental Royalties (A980) Q2 2026 Earnings Report
DE:A980 Q2 2026 EPS Results
- Actual EPS
- EUR 0.04
- Consensus EPS
- EUR 0.09
- Beat/Miss
- Missed by -EUR 0.05
- One Year Ago EPS
- EUR 0.00
DE:A980 Q2 2026 Revenue Results
- Actual Revenue
- EUR 21.27M
- Expected Revenue
- EUR 20.24M
- Beat/Miss
- Beat by +EUR 1.02M
- YoY Revenue Growth
- +161.58%
Earnings Announcement Details
- Quarter
- Q2 2026
- Date
- 08/11/2026
- Time
- After Close
- Conference Call
- Tuesday, August 11, 2026
Elemental Royalties's next earnings date is estimated for November 25, 2026, based on past reporting schedules.
Q2 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q2 2026 Earnings Slide Deck
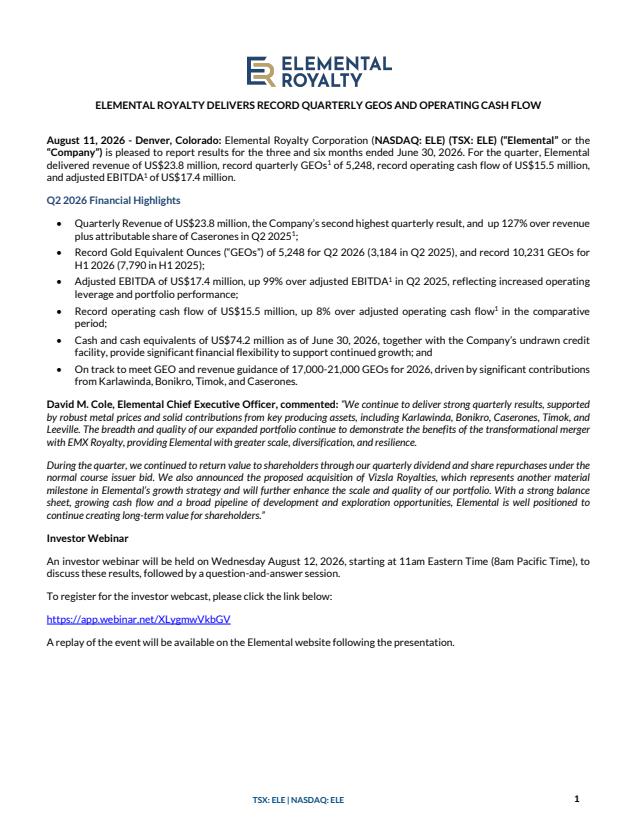
Q2 2026 Earnings Call Summary
The call conveyed a strongly positive operational and financial picture with substantial year-over-year growth in revenue, GEOs sold, EBITDA and cash generation, meaningful portfolio upgrades and corporate milestones (listings, index inclusions, dividend, NCIB, larger cornerstone assets). Near-term execution risks include pending regulatory approval for the Vizsla transaction, planned cash outlays (~$60M Vizsla + ~$25M Chapi) that will reduce the current cash balance, elevated near-term G&A from integration activities, and concentration of revenue among top assets. Management provided clear plans to reduce costs and maintain flexibility, and described a strong balance sheet and credit facility to support further growth.
Management guided 2026 GEOs at 17,000–21,000 and said the company is tracking to the upper end (21,000) after selling 5,250 GEOs in Q2 and ~10,000 GEOs in H1; H1 revenue was ~$48M (Q2 ≈$24M), adjusted EBITDA was $17.4M (~74% of revenue) and operating cash flow $15.5M, with $74M cash and $96M working capital at quarter‑end; they expect G&A to fall to a low ~$4M/quarter (annualized ~$16–18M), target adjusted EBITDA margin >80% in 2027, and see GEO growth to ~25,000 in 2028 and ~30–35,000 by 2029–2030; corporate guidance includes closing the Vizsla (Panuco) deal in Q3 (≈$60M cash on close), a $150M credit facility (+$50M accordion), continued dividends (option to take in Tether Gold) and an NCIB up to 5%, while funding accretive M&A from cash/credit and occasional equity as needed.
- Strong Q2 Revenue GrowthQ2 revenue of approximately $24.0M, a 127% increase year-over-year; H1 revenue of ~$48M, putting the company on track to meet or exceed 2026 guidance (previous guidance cited up to ~$85M for the year).
- Material Increase in Gold Equivalent Ounces Sold5,250 GEOs sold in Q2, a 65% increase versus the prior year; H1 total ~10,000 GEOs and management is tracking toward the upper end of 2026 guidance (17,000–21,000 GEOs). GEOs are calculated using actual average realized prices for the quarter.
- Improved Profitability and Cash GenerationAdjusted EBITDA of $17.4M (up nearly 100% YoY) and record operating cash flow of $15.5M in Q2 (operating cash flow up ~8% YoY due to prior-year timing). Adjusted EBITDA margin ~74% of revenue with a target >80% by 2027.
- Solid Balance Sheet and Liquidity PositionCash of ~$74M at quarter end (prior to ~$25M Chapi investment and expected ~$60M cash to close Vizsla); working capital ~$96M; credit facility upsized to $150M with $50M accordion and lower cost of capital; management expects to remain in a strong financial position post-close.
- Portfolio and Scale EnhancementsTop-6 cornerstone asset average value increased from ~$40M (mid‑2025) to ~$170M after recent acquisitions; ~3x increase in total number of royalties year-over-year; portfolio roughly 2/3 gold and 1/3 copper, with ~200 earlier-stage royalties providing embedded optionality.
- Strategic Acquisitions and Corporate MilestonesAgreement to acquire Vizsla Royalties (uncapped life-of-mine 2%–3.5% NSR on Panuco) expected to close in Q3 pending Mexican antitrust approval; completed Chapi investment (adds immediate cash flow and equity exposure); NASDAQ listing, TSX uplist, S&P/TSX Global Gold and Russell 2000 index inclusions; maiden dividend introduced and two quarterly dividends paid; NCIB approved up to 5%.
- High-Quality Asset Updates and Growth CatalystsKarlawinda generated ~USD 3M in Q2 and H1 each, expansion on track to increase production to ~150k oz/year with a ~30% reserve increase and ~48% resource increase; Caserones drilling program (~100 km / ~100,000 m) ongoing; Timok, Leeville, Bonikro and others are reliable contributors (management notes ~80% of revenue from top 5 assets).
- Capital Allocation DisciplineBalanced returns of capital: initiated maiden dividend, allowed dividend election in Tether Gold or cash, and early NCIB activity (share repurchases of ~$2M); management emphasizes accretive use of balance sheet and first use of credit facility financing for deals, with equity issuance as a potential tool for very large transactions.
DE:A980 Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Nov 25, 2026 | 2026 (Q3) | 0.07- | 0.05 | ― | ― |
| Aug 11, 2026 | 2026 (Q2) | 0.090.04 | 0 | ― | |
| May 13, 2026 | 2026 (Q1) | 0.100.02 | 0.18 | -90.00% (-0.16) | |
| Mar 24, 2026 | 2025 (Q4) | 0.09-0.18 | 0 | ― | |
| Nov 12, 2025 | 2025 (Q3) | 0.150.05 | 0 | ― | |
| Aug 18, 2025 | 2025 (Q2) | 0.150.00 | 0 | ― | |
| May 20, 2025 | 2025 (Q1) | ―- | -0.01 | ― | |
| Apr 16, 2025 | 2024 (Q4) | 0.150.18 | -0.09 | 300.00% (+0.27) | |
| Nov 18, 2024 | 2024 (Q3) | 0.040.00 | -0.09 | 100.00% (+0.09) | |
| Aug 19, 2024 | 2024 (Q2) | 0.040.00 | -0.09 | 100.00% (+0.09) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
