

TeamViewer AG (TMV) Q2 2026 Earnings Report
CH:TMV Q2 2026 EPS Results
- Actual EPS
- CHF 0.25
- Consensus EPS
- CHF 0.18
- Beat/Miss
- Beat by +CHF 0.07
- One Year Ago EPS
- CHF 0.25
CH:TMV Q2 2026 Revenue Results
- Actual Revenue
- CHF 168.36M
- Expected Revenue
- CHF 173.48M
- Beat/Miss
- Missed by -CHF 5.12M
- YoY Revenue Growth
- -1.55%
Earnings Announcement Details
- Quarter
- Q2 2026
- Date
- 07/28/2026
- Time
- Before Open
- Conference Call
- Tuesday, July 28, 2026
TeamViewer AG's next earnings date is estimated for November 3, 2026, based on past reporting schedules.
Q2 2026 Earnings Call Audio
No earnings call audio is available for this earnings event.
Q2 2026 Earnings Slide Deck
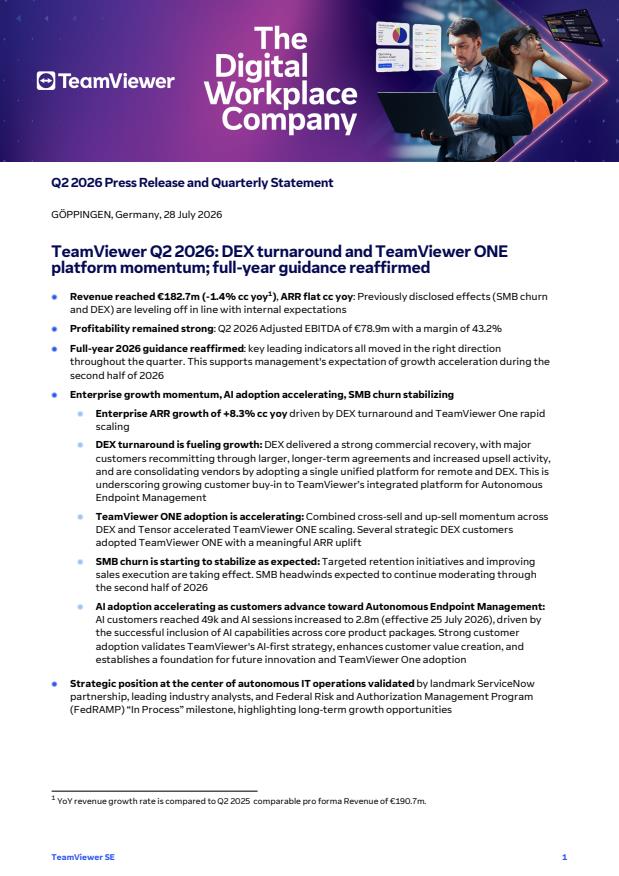
Q2 2026 Earnings Call Summary
The call conveyed a constructive operational inflection: enterprise momentum, platform adoption (TeamViewer ONE), rapid AI adoption, strategic validation via a ServiceNow partnership and FedRAMP progress were highlighted as major positives. However, SMB remains a near-term headwind, revenue was slightly down year-over-year, FX pressures and weaker upfront multiyear payments pressured cash flow and adjusted EBITDA. Management reiterated full-year guidance, emphasized improving leading indicators, and outlined actions to continue deleveraging and invest in growth.
TeamViewer reiterated its full‑year 2026 guidance, forecasting constant‑currency revenue growth of 0–3% versus pro‑forma 2025 and expecting ARR growth to accelerate in H2, while targeting an adjusted EBITDA margin of around 43%; Q2 actuals included ARR of EUR 737m, revenue of EUR 183m (‑1.4% y/y CC), adjusted EBITDA of EUR 79m (43.2% margin; 44.4% excluding FX), adjusted EPS of EUR 0.27 and net income +33% y/y, with gross profit EUR 168m (92% margin), pretax cash from operations EUR 66m and levered free‑cash‑flow conversion of 52%; management warned of FX headwinds (Q2 revenue FX drag ~2.8 pp, adjusted EBITDA impacted ~5.4 pp, spot rates imply ‑2.1 pp for Q3 and ‑2.4 pp for full year) and reiterated a deleveraging path from Q2 net debt EUR 833m / 2.5x leverage toward ~2.3x (guidance range ~2.0–3.0x) by year‑end, with free cash flow expected to be seasonally stronger in H2.
- Enterprise ARR Growth and Platform MomentumTotal enterprise ARR grew +8% year-over-year in constant currency, driven by the DEX turnaround and stronger customer engagement. Customers with >€200k ARR grew +11% YoY CC, and enterprise revenue increased +3% YoY to €59m, demonstrating accelerating adoption of TeamViewer ONE across large accounts.
- Strong ProfitabilityAdjusted EBITDA was €79m with a margin of 43.2%; adjusted EBITDA margin would have been 44.4% excluding FX headwinds. Although adjusted EBITDA declined 6% YoY, the company maintained an industry-leading margin while investing in growth.
- Improved Bottom-Line and EPSNet income increased +33% year-over-year and adjusted EPS was €0.27 for Q2, reflecting improved profitability despite top-line headwinds.
- ARR and Revenue ScaleARR was broadly stable year-over-year in constant currency at €737m. Reported revenue was €183m (down 1.4% YoY in constant currency), showing resilience in subscription scale amid transitional dynamics.
- AI Adoption and Product InnovationAI usage accelerated significantly: more than 500,000 AI-powered support sessions in June (up from ~300,000 in March), over 2.8 million AI-powered sessions cumulatively, and customers using AI rose to ~49,000 (from 26,000 in Q1). An August release will introduce automations to convert proven resolutions into scalable workflows.
- Strategic ServiceNow PartnershipAnnounced a multiyear strategic partnership with ServiceNow to integrate TeamViewer's endpoint and DEX capabilities with ServiceNow's AI orchestration, expanding market access (ServiceNow serves ~8,800 large enterprise customers) and creating a joint go-to-market and technology route to market.
- Regulatory & Market Access Milestone (FedRAMP)TeamViewer DEX received 'FedRAMP in process' designation and was listed on the FedRAMP marketplace, an important step toward U.S. federal authorization that expands addressable market in regulated industries.
- External RecognitionMultiple analyst and peer recognitions reinforce market position: Gartner named TeamViewer a leader in the 2026 Magic Quadrant for DEX (third consecutive year), IDC named TeamViewer a leader, Frost & Sullivan and PAC recognitions for Frontline, plus leading positions on G2 and TrustRadius.
- Deleveraging Progress and Liquidity ActionsNet debt improved by €37m quarter-over-quarter to €833m and net leverage was 2.5x with a clear path to the year-end target of ~2.3x. Company extended a €75m RCF maturity to 2031, secured a €40m bilateral facility (EIB-backed), and initiated a Schuldschein placement to optimize funding and repay acquisition-related bridge debt.
CH:TMV Earnings History
| Report Date | Fiscal Quarter | Forecast / EPS | Last Year's EPS | EPS YoY Change | Press Release |
|---|---|---|---|---|---|
| Nov 03, 2026 | 2026 (Q3) | 0.20- | 0.31 | ― | ― |
| Jul 28, 2026 | 2026 (Q2) | 0.180.25 | 0.25 | 0.00% (+0.00) | |
| May 06, 2026 | 2026 (Q1) | 0.200.27 | 0.27 | 0.00% (+0.00) | |
| Feb 10, 2026 | 2025 (Q4) | 0.140.29 | 0.2 | 40.91% (+0.08) | |
| Oct 21, 2025 | 2025 (Q3) | 0.140.31 | 0.23 | 36.00% (+0.08) | |
| Jul 29, 2025 | 2025 (Q2) | 0.300.25 | 0.15 | 68.75% (+0.10) | |
| May 06, 2025 | 2025 (Q1) | 0.270.27 | 0.15 | 83.54% (+0.12) | |
| Feb 12, 2025 | 2024 (Q4) | 0.240.20 | 0.17 | 22.22% (+0.04) | |
| Nov 06, 2024 | 2024 (Q3) | 0.250.23 | 0.14 | 66.67% (+0.09) | |
| Jul 31, 2024 | 2024 (Q2) | 0.170.15 | 0.18 | -20.00% (-0.04) |
The table shows recent earnings report dates and whether the forecast was beat or missed. See the change in forecast and EPS from the previous year.
