Rocket Lab (RKLB) is set to report its third-quarter 2026 results on November 9. The company operates through two business segments: Space Systems, which develops and supplies satellites and spacecraft components, and Launch Services, which provides dedicated rocket launch services. Space Systems drives revenue, while Launch Services remains key to long-term growth.
Ahead of the results, Key Performance Indicators (KPIs), including revenue by segment, gross profit, backlog, and cost per launch, will provide insight into the company’s growth and operating performance. For Q3, the firm has set a revenue target of $250 million to $265 million and expects GAAP gross margins of 29% to 31%.
In the second quarter of 2026, Rocket Lab posted record revenue of $234.07 million, up 62% year over year. Its total backlog also reached a record $2.36 billion as of June 30, 2026.
Meanwhile, Wall Street expects Rocket Lab to post a loss of $0.07 per share, wider than the $0.03 per share loss reported in the prior-year period. Revenue is forecast to jump 65.8% year-over-year to $257.21 million.
Space Systems Leads Sales and Profit
Space Systems is now Rocket Lab’s largest source of revenue. In Q2 2026, the unit brought in $189.48 million, up from $97.85 million in the same quarter last year. By contrast, Launch Services generated $44.59 million, down from $46.65 million a year ago.
Space Systems also led in gross profit, with $65.47 million in Q2 2026, more than three times the $19.11 million from Launch Services.
The gap is also seen in the firm’s order book. As of June 30, 2026, Space Systems had a backlog of $1.42 billion, while Launch Services had $940.2 million.

Launch Costs Show a Drop
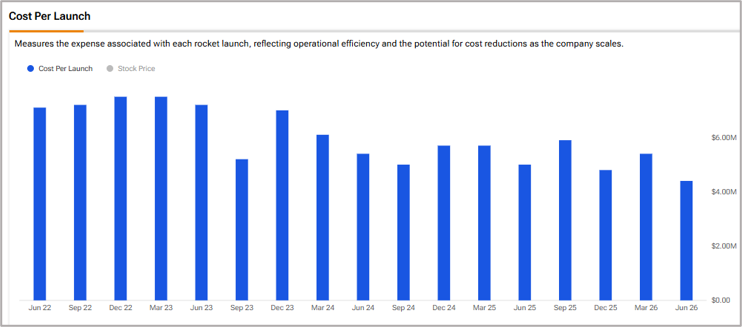
While Launch Services generates less revenue than Space Systems, its cost per launch has come down. In Q2, the cost stood at $4.4 million, down from $5 million in Q2 2025 and $7.5 million in Q1 2023. Lower launch costs can help the firm improve margins as it carries out more launches.
Neutron Delay and Iridium Deal
Rocket Lab has pushed the first launch of its Neutron rocket to 2027 due to issues with carbon-fiber parts used in its fuel tanks. The delay could push back new launch plans and add to development costs.
The pending acquisition of Iridium Communications (IRDM) is another key factor. The deal is expected to close by mid-2027, subject to the remaining regulatory approvals and closing terms. It would give Rocket Lab access to Iridium’s satellite network and telecom business, adding a new source of recurring revenue.
Should You Buy RKLB Stock Ahead of Results?
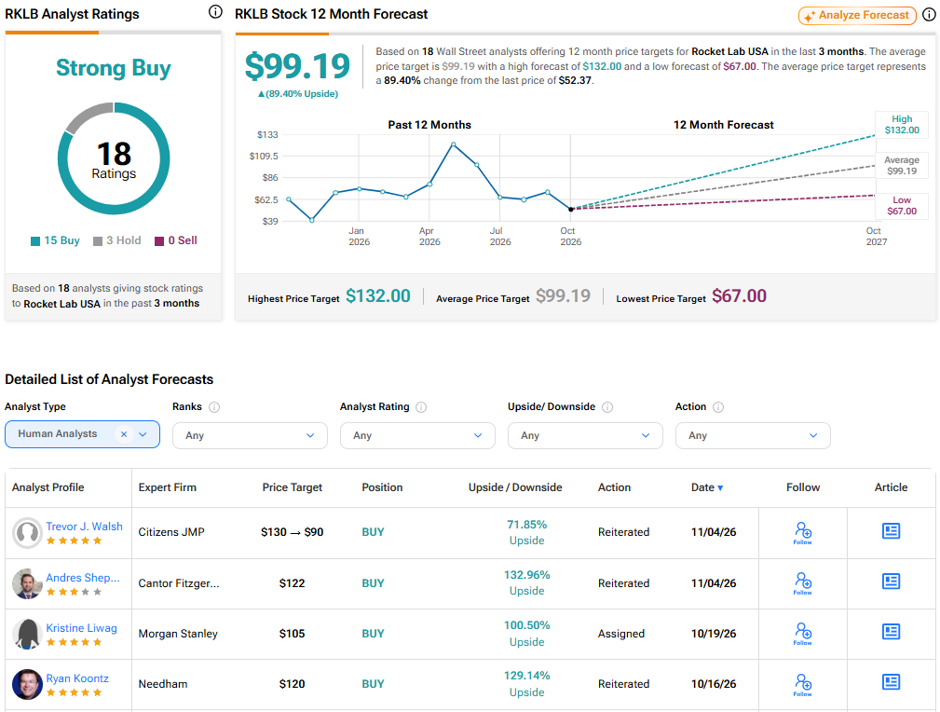
On TipRanks, RKLB has a Strong Buy consensus rating based on 15 Buys and three Hold ratings. The average Rocket Lab price target of $99.19 implies 89.4% upside potential from current levels. Year-to-date, RKLB shares have dropped 28.4%.