


Intel (INTC) stock rose over 4% in Monday’s pre-market trading after J.P. Morgan analyst Harlan Sur upgraded his rating from Underweight (equivalent to Sell) to Neutral. The 5-star analyst said the chipmaker’s risk-reward profile has become “much more balanced” after the stock fell about 36% from its June peak. He upgraded the rating to Neutral as “the stock approached his $85 price target,” which remains 5.4% below its latest closing price of $89.85.
Meanwhile, the company will report its Q3 earnings on October 29. Wall Street expects Intel to report adjusted earnings per share (EPS) of $0.40, up 73.91% from $0.23 in the prior-year period. Revenue is forecast to rise 20.87% year over year to $16.50 billion from $13.65 billion.
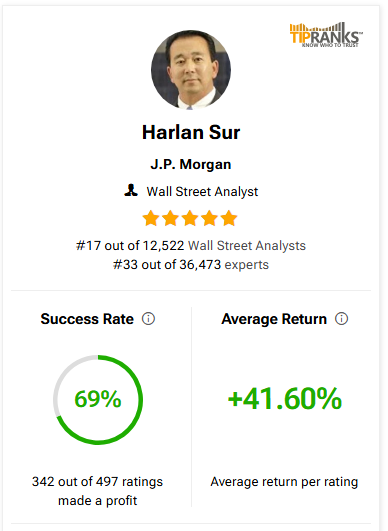
Sur is a five-star analyst on TipRanks, ranking #17 out of the 12,522 analysts tracked. He has a 69% success rate and an average return per rating of 41.60%.
Intel Continues to Lose CPU Market Share
Sur said Intel has lost ground to rivals since JPMorgan downgraded the stock in November 2022. Over that period, the Philadelphia Semiconductor Index (SOX) outperformed Intel by 37%. Broadcom (AVGO) and Advanced Micro Devices (AMD) outperformed Intel by 115% and 148%, respectively.
Intel has also lost market share in its core businesses. Its share of server CPU revenue fell from 77% to 53%, while its PC CPU share dropped from 81% to 68%. Sur expects further declines over the next few quarters, especially in server CPUs.
However, Sur sees better execution under CEO Lip-Bu Tan. He said Intel has improved its work on client and data center chips, along with its manufacturing process. Still, its external foundry business remains small. Annualized revenue from outside foundry customers was below $1 billion in the first half of 2026, compared with about $150 billion at Taiwan Semiconductor Manufacturing (TSM).
JPMorgan Sees Potential in AI and Custom Chips
Sur is also watching Intel’s plans for data center CPUs and its wider AI strategy. He sees potential in custom chips, known as ASICs, which could use Intel’s chip design skills and manufacturing capacity.
Although concerns remain about AI infrastructure spending, Sur expects rising demand from agentic AI workloads to support CPU sales. He also sees tight supply of advanced chips as a potential benefit for Intel. JPMorgan expects earnings estimates to rise through 2027, with its 2028 EPS forecast about 15% above Wall Street consensus.
What Is the Price Forecast for INTC Stock?
Intel has a Hold consensus rating based on 30 analyst ratings, including six Buys, 23 Holds, and one Sell. The average 12-month price target is $114.04, implying 26.92% upside from $89.85. The highest price target is $155, while the lowest is $80.
