


Caterpillar (CAT) stock’s pullback could offer a strong entry point, in my view. This is because the global construction equipment manufacturer is becoming less dependent on any single industrial upswing. Today, shares sit about 23.5% below June’s record high. However, Caterpillar exited Q2 with a record $72 billion backlog, marking a 92% year-over-year increase.
CEO Joe Creed said, “Strong order rates and a growing backlog reflect broadening momentum across all three of our primary segments.” The valuation requires the company to execute strongly ahead, but today’s demand mix looks longer-lived than the market’s old cyclical framing. Thus, my CAT stock forecast is bullish.

Caterpillar’s Infrastructure Demand Now Spans Several Cycles
Caterpillar’s infrastructure demand now spans several cycles, and that’s a game-changer for the company. An artificial intelligence (AI) data center needs far more than servers. Essentially, developers must prepare the site and connect it to roads, water, and the grid. Increasingly, they also need on-site generation because utility connections cannot arrive quickly enough. Caterpillar sells both the construction equipment and the engines, turbines, and generators.
The power opportunity is moving quickly. Power & Energy sales rose 17% to $8.2 billion in Q2, while power generation sales increased 29%. In Q1, Caterpillar also said it expects power generation sales to triple by 2030 from 2024 levels. Some customers are ordering as far out as 2030, and 59% of the backlog is due within 12 months.

One project demonstrates the scale. American Intelligence & Power ordered 2 gigawatts of Caterpillar generators for its West Virginia hyperscale campus, with deliveries through August 2027. The agreement also covers batteries, service planning, and parts support. This is long-term infrastructure, and not a one-quarter order.
However, AI is only one layer. Electrification needs grids. Reshoring needs factories and logistics. Also, critical minerals need mines. All pull through Caterpillar equipment.
I don’t believe that these waves will move in lockstep. I think that’s good, because it could make the combined opportunity more durable than a normal construction rebound.
AI and Services Can Reduce Cyclicality
AI and services can also reduce Caterpillar’s cyclicality from the inside. Its expanded Nvidia (NVDA) partnership brings AI computing into machines and factories, with the companies working toward autonomous construction fleets and smarter in-cab tools. Caterpillar has also demonstrated its first autonomous soil compactor, moving beyond giant mining sites.
The quarry rollout already seems to be commercial. After autonomous trucks hauled more than 3.5 million tons at Luck Stone’s Bull Run site, the customer expanded the system to two more quarries. Automation helps customers address labor shortages while improving consistency, utilization, and safety.
The already installed base provides a solid tailwind. Caterpillar generated $24 billion of services revenue last year and had more than 1.6 million connected assets.
Telematics, Customer Value Agreements, parts and repairs keep the relationship going after the original sale. These revenues are not recession-proof. Yet, they should be steadier than new-machine demand and deepen Caterpillar’s dealer-network advantage. The more Caterpillar’s backlog expands, the more valuable its connected devices and potential revenue will be.
So, I believe Caterpillar might remain cyclical to some extent. Still, its power projects are booked years ahead. Also, its growing service stream and more valuable machines should make a future downturn less severe than past equipment-led collapses.
CAT’s Premium Isn’t Far-Fetched
Meanwhile, I don’t believe CAT’s premium is far-fetched, despite the stock’s explosive rally in recent years. At today’s price, the latest consensus earnings per share (EPS) estimates of $27.19 for 2026 imply a forward P/E ratio of about 30x, while the EPS of $32.38 for 2027 implies a forward P/E ratio of roughly 25x, and the EPS of $38.95 for 2028 implies a 21x forward P/E. Those estimates call for EPS to grow about 19%–20% in 2027 and 2028.
Caterpillar’s valuation is well above the mid-to-high-teens P/Es common before the AI-infrastructure re-rating. So this setup looks quite different from the old “buy Caterpillar at a mid-teens multiple” opportunity I would have gone for in the past. It leaves little room for project delays, weaker commodity prices, recession, or slower data-center spending. Management also expects roughly $2.2 billion of tariff expense in 2026 before any additional recoveries.
However, the bullish case depends more on earnings growth than multiple expansion. Applying 23x–25x earnings to the 2028 estimate produces roughly $891–$968. I believe EPS can move even higher, faster, given the recent backlog evolution. A return to Caterpillar’s old valuation without the expected growth would hurt. Yet nothing really points to that scenario.
Cash returns remain strong and support upside too. Caterpillar raised its quarterly dividend 8% to $1.63 in June, marking its 32nd consecutive annual increase. The yield is only about 0.8%, but CAT also repurchased $1.5 billion of stock in Q2 and intends to return substantially all Machinery, Power & Energy free cash flow.
Is Caterpillar Stock a Buy, Sell, or Hold?
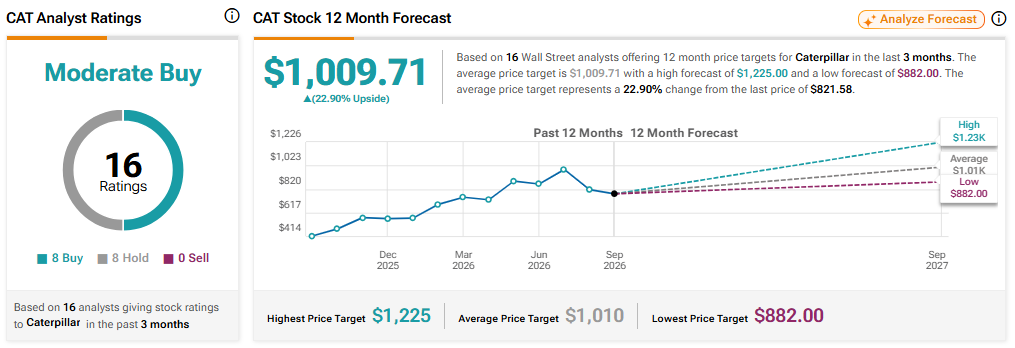
Wall Street currently rates Caterpillar a Moderate Buy, based on eight Buys and eight Holds. The $1,009.71 average price target implies roughly 23% upside from the current share price.
Conclusion
Caterpillar’s valuation is high, but the earnings opportunity has become broader and more visible. AI power, data-center construction, grids, mining, and reshoring are arriving together. Services and autonomy can smooth the equipment cycle, as well. With the stock nearly a quarter below its high, I believe the risk-reward now justifies a bullish view.