


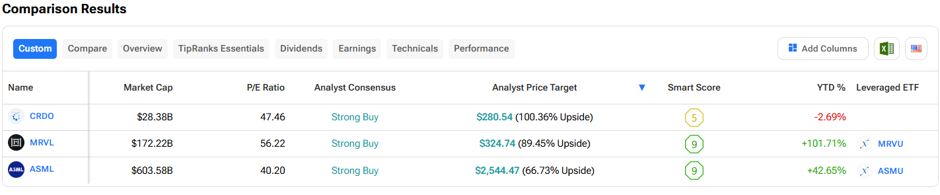
Using the TipRanks Stock Screener tool, we identified three high P/E stocks with Strong Buy consensus ratings and average analyst price targets implying at least 65% upside. Despite their premium valuations, analysts see further growth potential driven by AI demand and company-specific catalysts.
Why Do Some Stocks Have High P/E Ratios?
A high price-to-earnings (P/E) ratio does not necessarily mean a stock is overvalued. Some investors are willing to pay a premium for companies expected to deliver solid earnings growth. Strong industry trends and competitive advantages can also justify higher valuations. However, investors must assess whether future growth can support the current valuation.
Credo Technology (CRDO)
- P/E Ratio: 47.46x
- Average Credo Technology Price Target: $280.54 (100.4% upside)
Credo develops high-speed connectivity products that help transfer data quickly between GPUs and across AI data centers. Its products also help reduce power consumption while handling the growing data needs of AI applications. Rising investments in AI data centers are creating strong demand for its solutions.
Credo is scheduled to release its Q2 FY27 results on December 2. Wall Street expects Credo to post adjusted earnings of $1.29 per share, significantly higher than the $0.67 per share posted in the prior-year period. Revenue is forecast to jump 98.4% year-over-year to $531.84 million.
Marvell Technology (MRVL)
- P/E Ratio: 56.22x
- Average Marvell Price Target: $324.74 (89.5% upside)
Marvell develops custom chips and networking products used in AI data centers. Major cloud companies are investing heavily in custom AI chips to reduce their dependence on standard GPUs. Marvell helps these companies design such chips and provides the networking technology needed to connect them across large data centers.
Marvell is scheduled to report its Q3 FY27 results on November 26. Wall Street expects Marvell to report adjusted earnings of $1.10 per share, up from $0.76 per share in the year-ago period. Revenue is projected to surge 52.2% year-over-year to $3.15 billion.
ASML Holdings (ASML)
- P/E Ratio: 40.21x
- Average ASML Price Target: $2,544.47 (66.7% upside)
ASML makes advanced machines used to manufacture semiconductor chips. It is the leading supplier of EUV lithography machines, which are essential for producing the most advanced chips used in AI processors and data centers. As demand for advanced chips continues to grow, ASML is expected to benefit from increased spending on chip manufacturing.
ASML recently reported strong fiscal third-quarter results. Adjusted earnings came in at $14.40 per share, easily beating the consensus estimate of $12.17 and significantly higher than $6.38 reported in the prior-year period. Revenue surged 52.8% year-over-year to $13.42 billion and also surpassed the consensus of $13.14 billion.